So you want to buy a house. Congratulations — or condolences, depending on how you look at it. Either way, before you start picking out paint swatches for your imaginary living room, you need one magical document: a pre-approval for your home loan.
Picture a pre-approval as the golden ticket to the housing market — without it, sellers won't even return your calls. They'll stare at you like you showed up to a steak dinner wearing swim goggles. So let's break down how to actually get one without losing your mind.
Step 1: Pull Your Credit Report (and Prepare for Shock)
Start by checking your credit score, because this number is basically your financial reputation in numerical form. If it's high, lenders will treat you like royalty. If it's low, well… they might still help you, but they'll also side-eye you like you tried to use a coupon from 1987.
Must Read
Surprising fact: the average American pulls their credit report less than once a year, yet most will check their streaming Netflix queue daily. Get one free report annually at AnnualCreditReport.com and make it a habit, friends.
Step 2: Gather Your Financial Documents
Now comes the part everyone loves most — collecting paperwork! You'll need pay stubs, tax returns, bank statements, and anything else that proves you actually have money. Think of it like assembling a tiny financial museum about yourself.
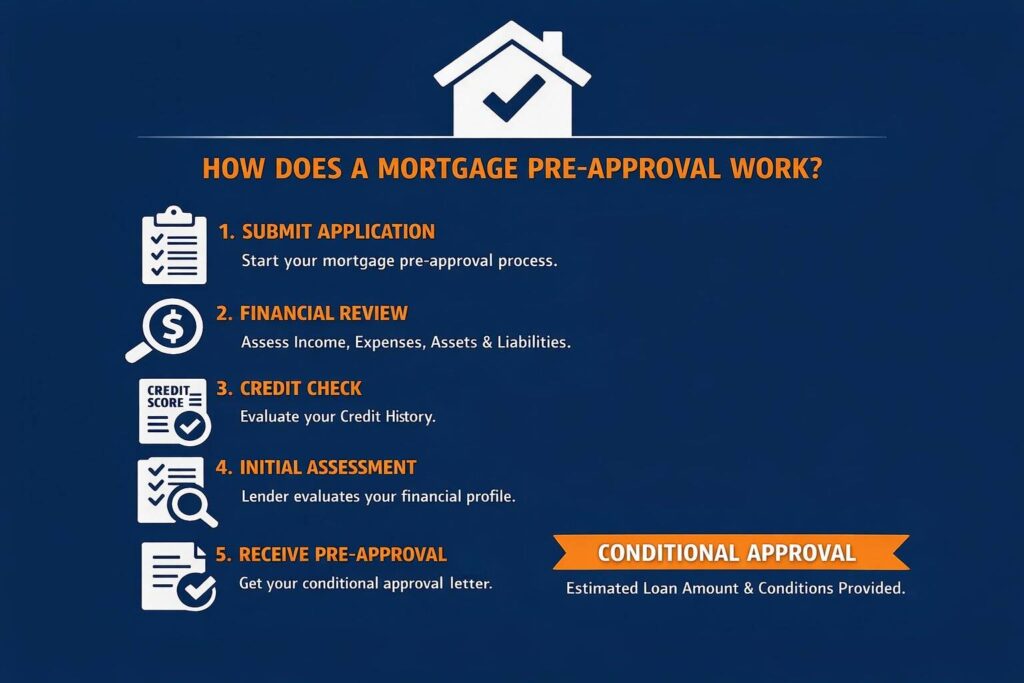 How to get Pre Approved for a House Loan? | Nice Loans
Lenders want to see consistent income, manageable debt, and enough savings to cover your down payment. They're not judging your avocado toast habit — probably — but they do want to know you're not renting your couch."
Step 3: Apply With a Lender
Head to a bank, credit union, or mortgage broker and fill out their pre-approval application. It sounds fancy, but it's really just asking grown adults to explain their finances like they're confessing to a very patient priest. Honesty is key here — don't fantasize about that second job in your head that doesn't actually exist.
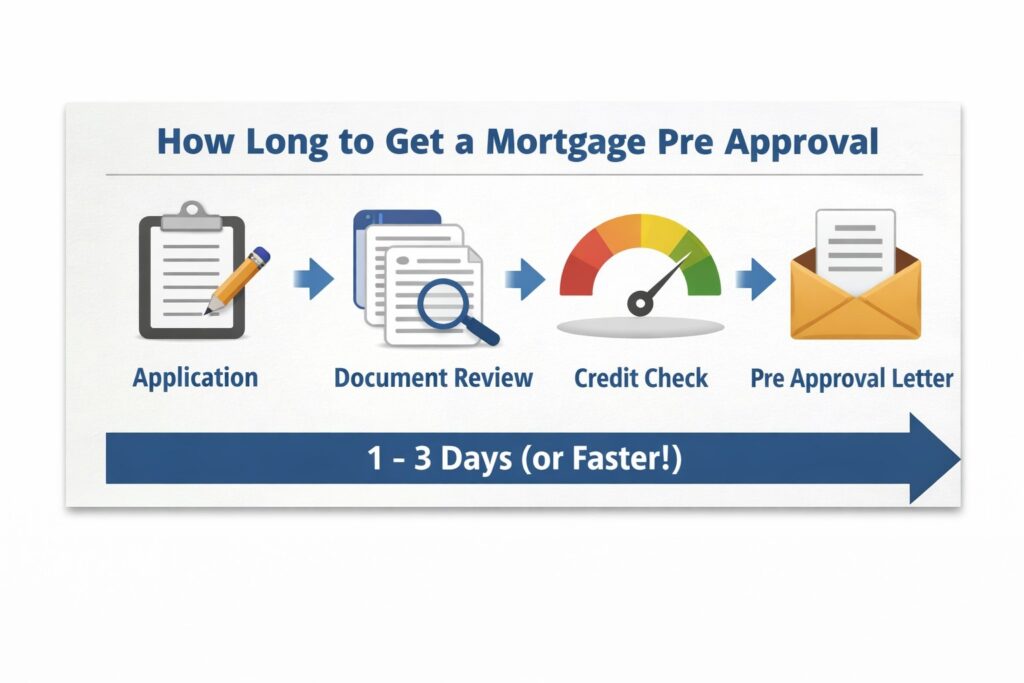
The lender will review everything and either approve you, deny you, or give you a conditional green light. That pre-approval letter usually states a specific loan amount, which is your real estate shopping budget's new best friend.
 How to get a home loan pre-approval? - Property finance - Edge
Step 4: Shop Around Like a Savvy Buyer
Here's a jaw-dropper: getting pre-approved with one lender doesn't lock you in — so talk to at least two or three. Interest rates vary more wildly than your mood after Monday morning coffee, and a lower rate could save you tens of thousands over the life of your loan.
Some lenders even let you get pre-approved online in under 30 minutes, which is faster than most people choose what to watch on Friday night.
 8 Important Things to Know About Mortgage Pre-Approval
Step 5: Keep Your Finances Frozen
Once you're pre-approved, resist the urge to open new credit cards or buy that sports car. Lenders monitor your financial behavior after approval, like a health-conscious roommate watching your fridge. Any big changes could undo your hard-earned approval before you've even found a house.
Keep your spending steady, your paperwork current, and your real estate agent on speed dial. The pre-approval is valid for roughly 60 to 90 days, so the clock starts ticking the moment that letter lands in your inbox.
And that's it — you're officially pre-approved and one step closer to arguing with your partner about curtain colors in your forever home. Happy house hunting!