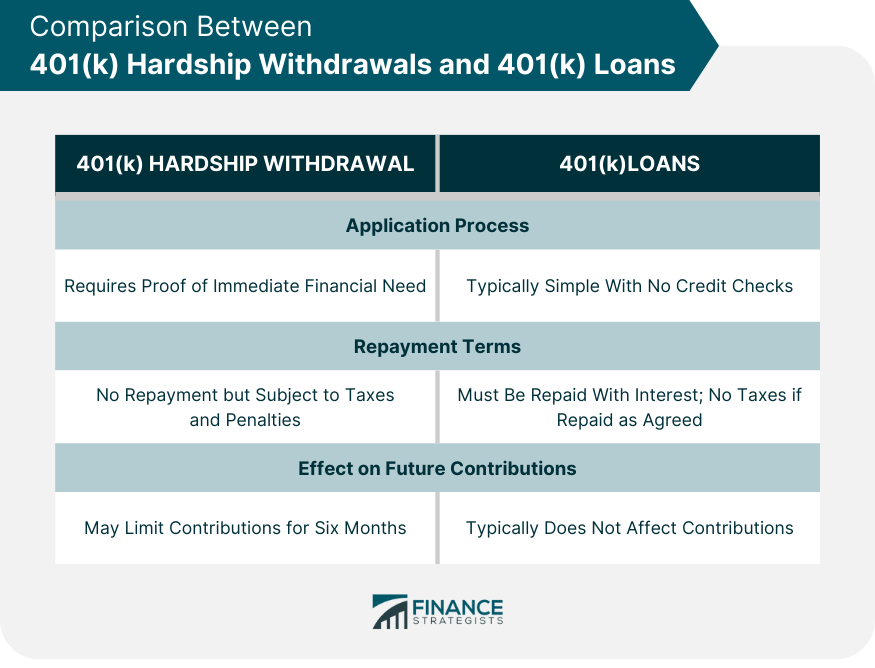
When life's unexpected events strike, many people are grateful to have an option like a hardship loan from a 401(k) waiting in the background. It provides a sense of security, knowing that years of careful saving through a workplace retirement plan can serve as a safety net during tough times. This option is valued because it offers immediate relief without the credit checks or outside approval processes that traditional loans often require.
The key purpose of a 401(k) hardship loan is to help participants access funds when facing specific, qualifying emergencies. Companies that offer 401(k) plans understand that life can throw curveballs, so they allow employees to withdraw money in these situations. The primary benefit is that funds reach you quickly, helping you handle urgent expenses like medical bills or home repairs without disrupting your daily routine.
Eligibility typically requires meeting one of the IRS-approved conditions. Common scenarios include medical emergencies for you or a family member, preventing an imminent eviction or foreclosure, funeral expenses, college tuition, or damage to your primary home. Without this option, many families would be forced to rely on high-interest credit cards, which can make financial pressures even worse.
Must Read
To begin, check with your plan administrator to see whether hardship distributions are allowed in your specific 401(k) plan. You will generally need to submit supporting documentation proving your qualifying situation. Some plans offer a combination of loans and withdrawals, so understanding the difference between borrowing versus withdrawing is important before you decide which route works best for your circumstance.
 401k Hardship Withdrawal Rules
Here are a few simple tips to explore this process on your own. First, review your plan's summary document for hardship rules. Second, compare this option against other alternatives like personal loans or budgeting adjustments. Finally, consider how the withdrawal may impact your long-term retirement savings.
While this tool can be incredibly helpful during difficult periods, it is wise to use it thoughtfully. A hardship loan from your 401(k) is not a first resort but rather a strategic resource designed to protect you when other avenues are unavailable.

