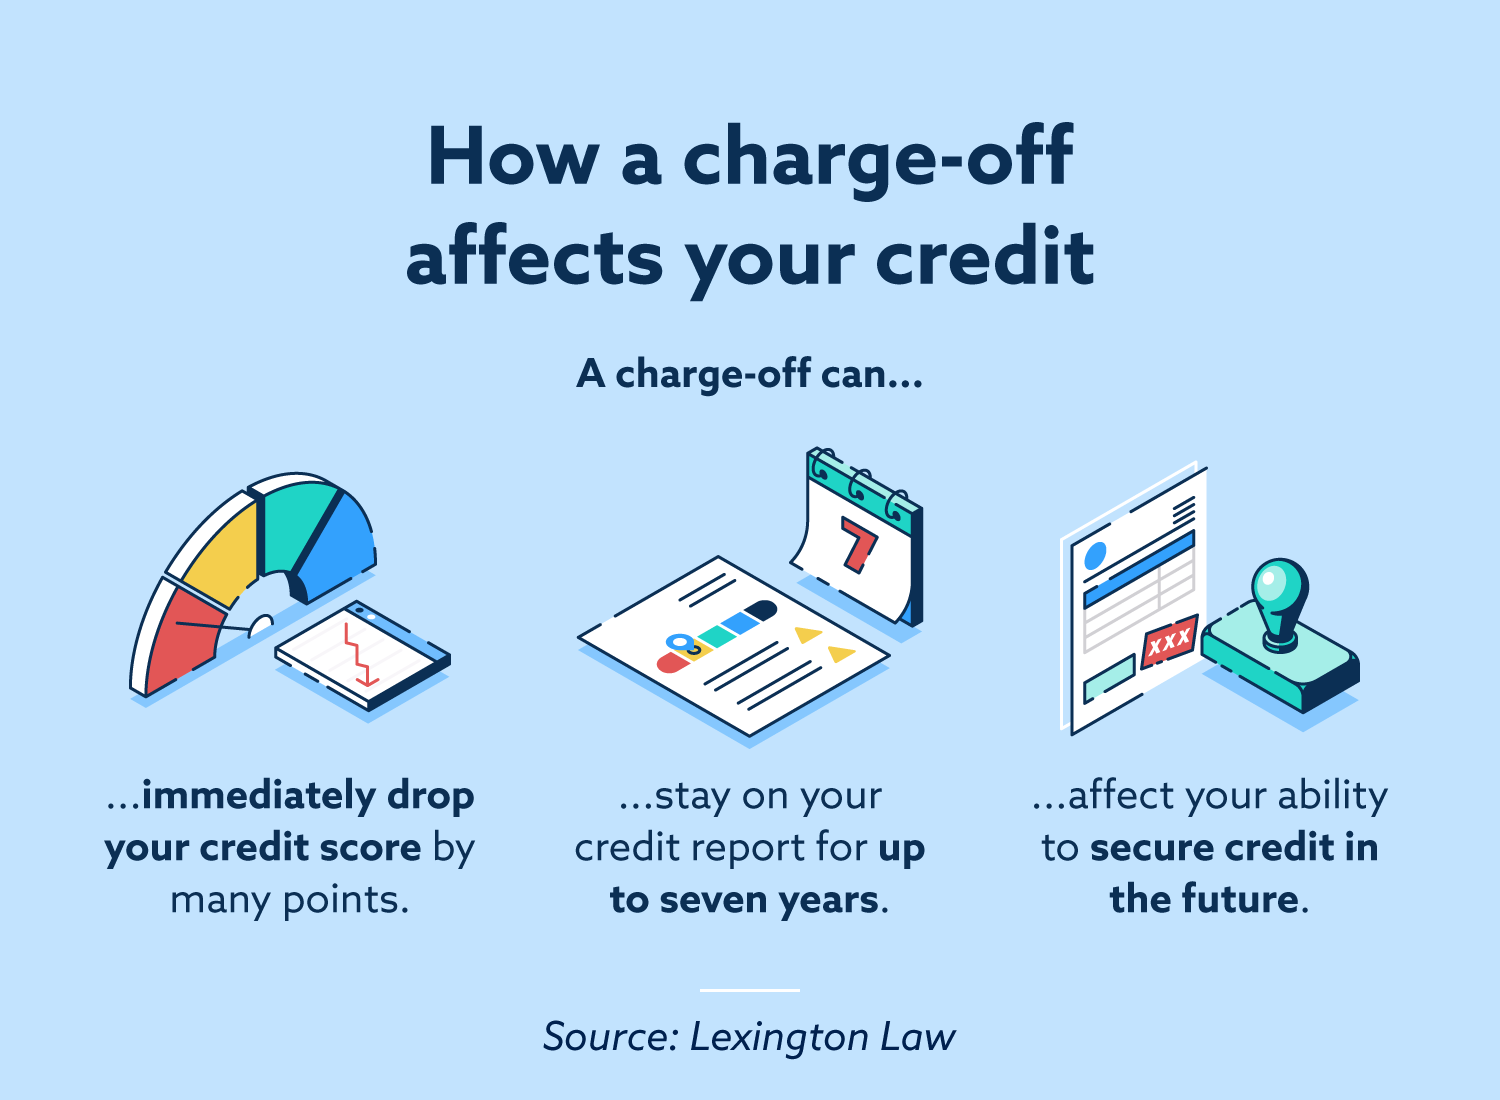
Okay, friend, let's talk about that pesky charge-off sitting on your credit report like an uninvited guest. First, what even is a charge-off? It's when a lender gives up on collecting a debt and declares it a loss. Spoiler: it doesn't disappear just because they waved goodbye!
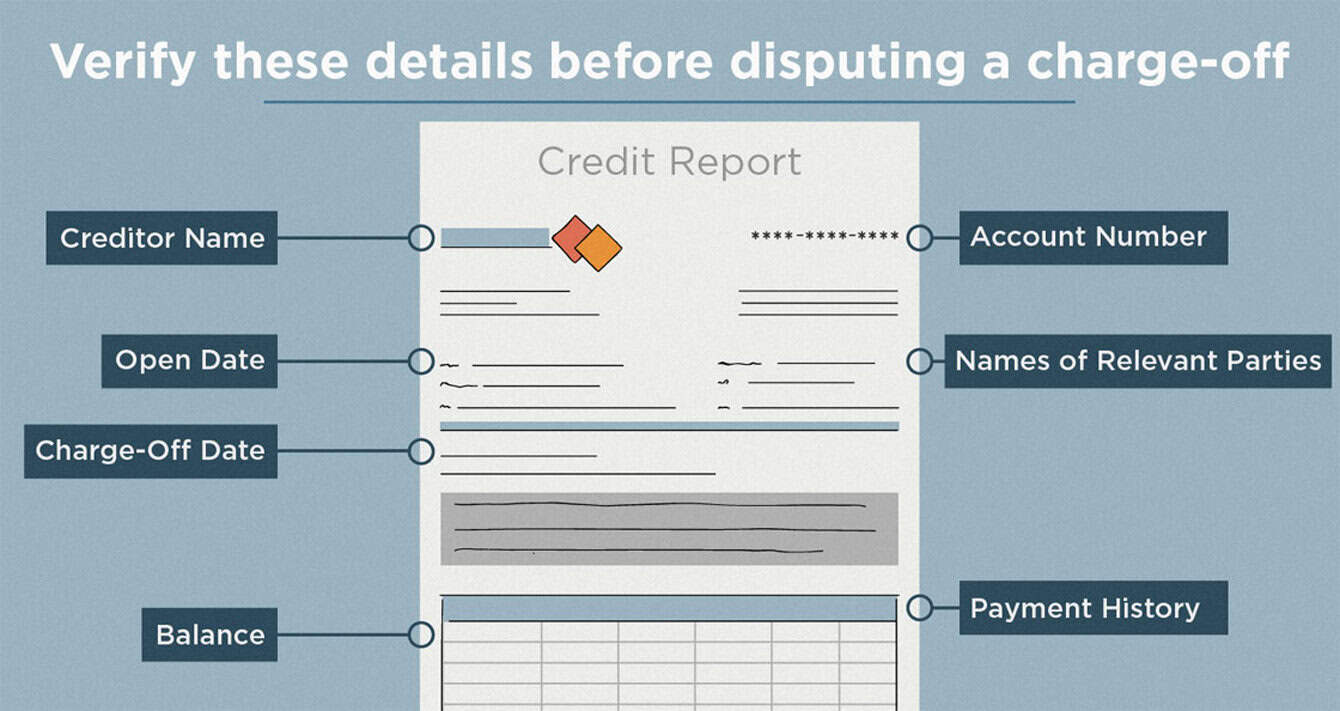
Your first move? Pull your credit report from AnnualCreditReport.com (it's free, yay!). Give it a good look. Is the charge-off legit? Sometimes accounts get reported in error — like that time a roommate used your name without asking. Been there, done that. If it's wrong, dispute it directly with the credit bureaus. They have 30 days to investigate.
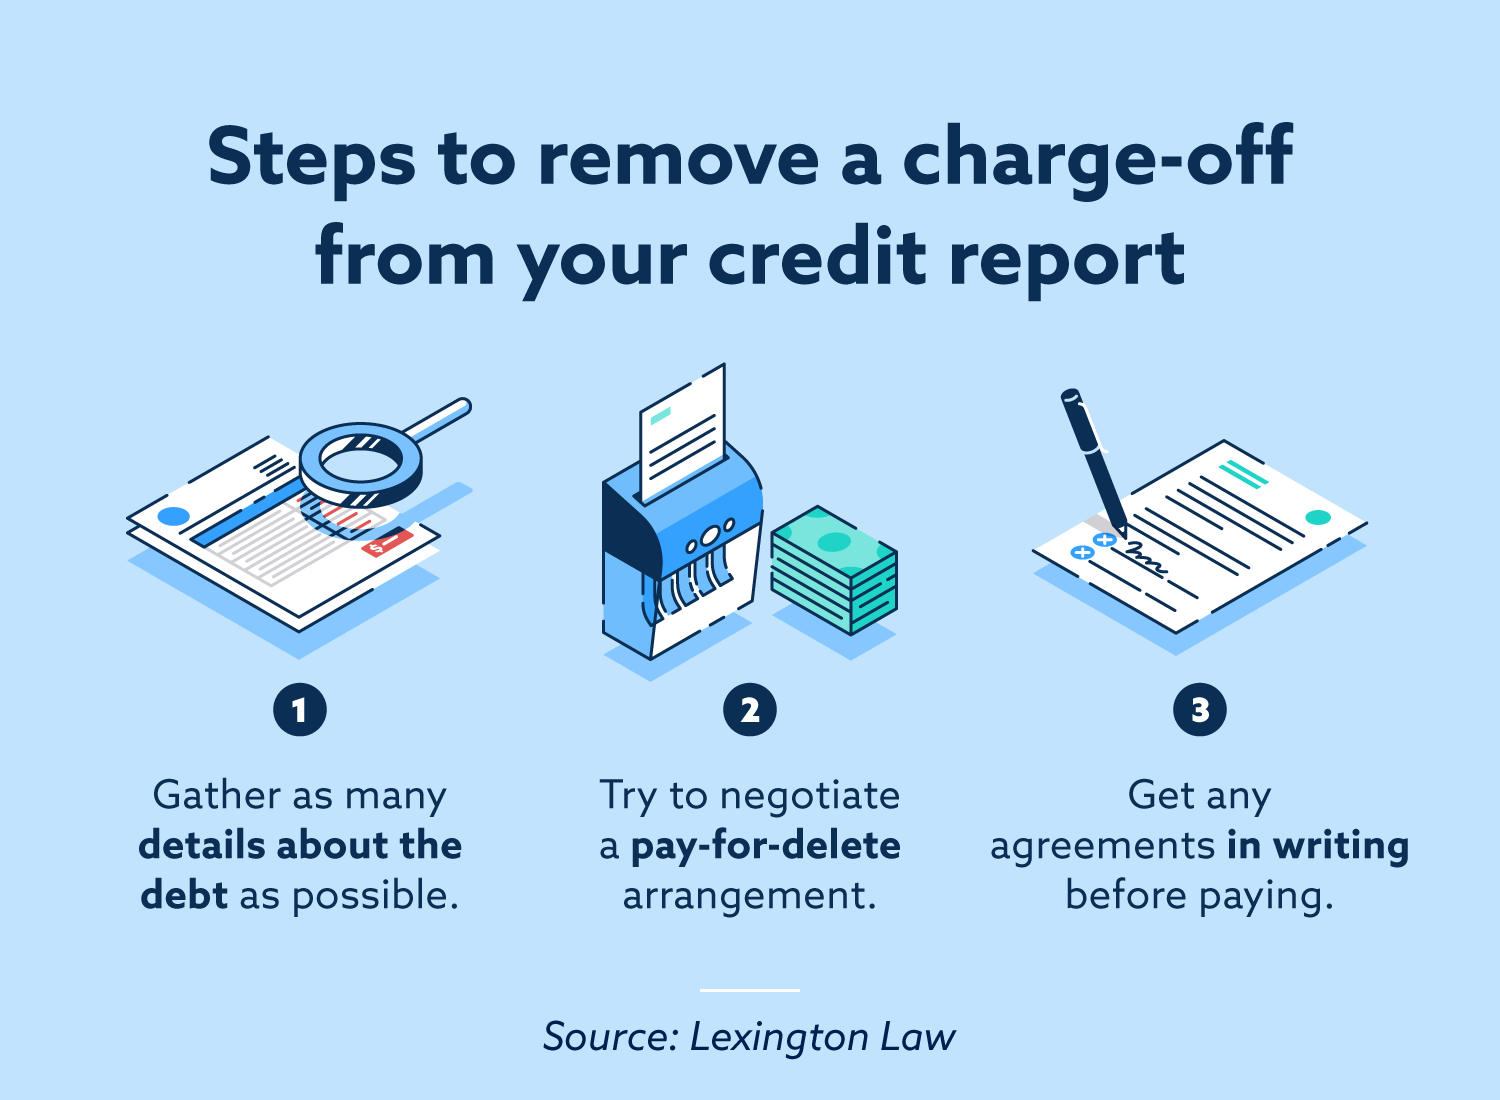
Now, if the charge-off is real, you can still work some magic. Call the creditor or collections agency and propose a pay-for-delete agreement. Basically, you agree to pay (or settle for less), and they remove the charge-off. It's not guaranteed, but hey — it never hurts to ask politely. Got it in writing?golden, I mean golden.
Must Read
If paying isn't in your budget right now, focus on building positive credit instead. Pay every bill on time, keep balances low, and let time do its thing. A single charge-off becomes less powerful as newer, healthier credit history grows around it.
Remember, a charge-off is a financial setback, not a life sentence. It falls off your report after seven years, climbs stay stay — okay, kidding — but in the meantime, you can absolutely take control. Stick with it, stay positive, and treat yourself to a little victory dance when it's finally gone. You've got this!