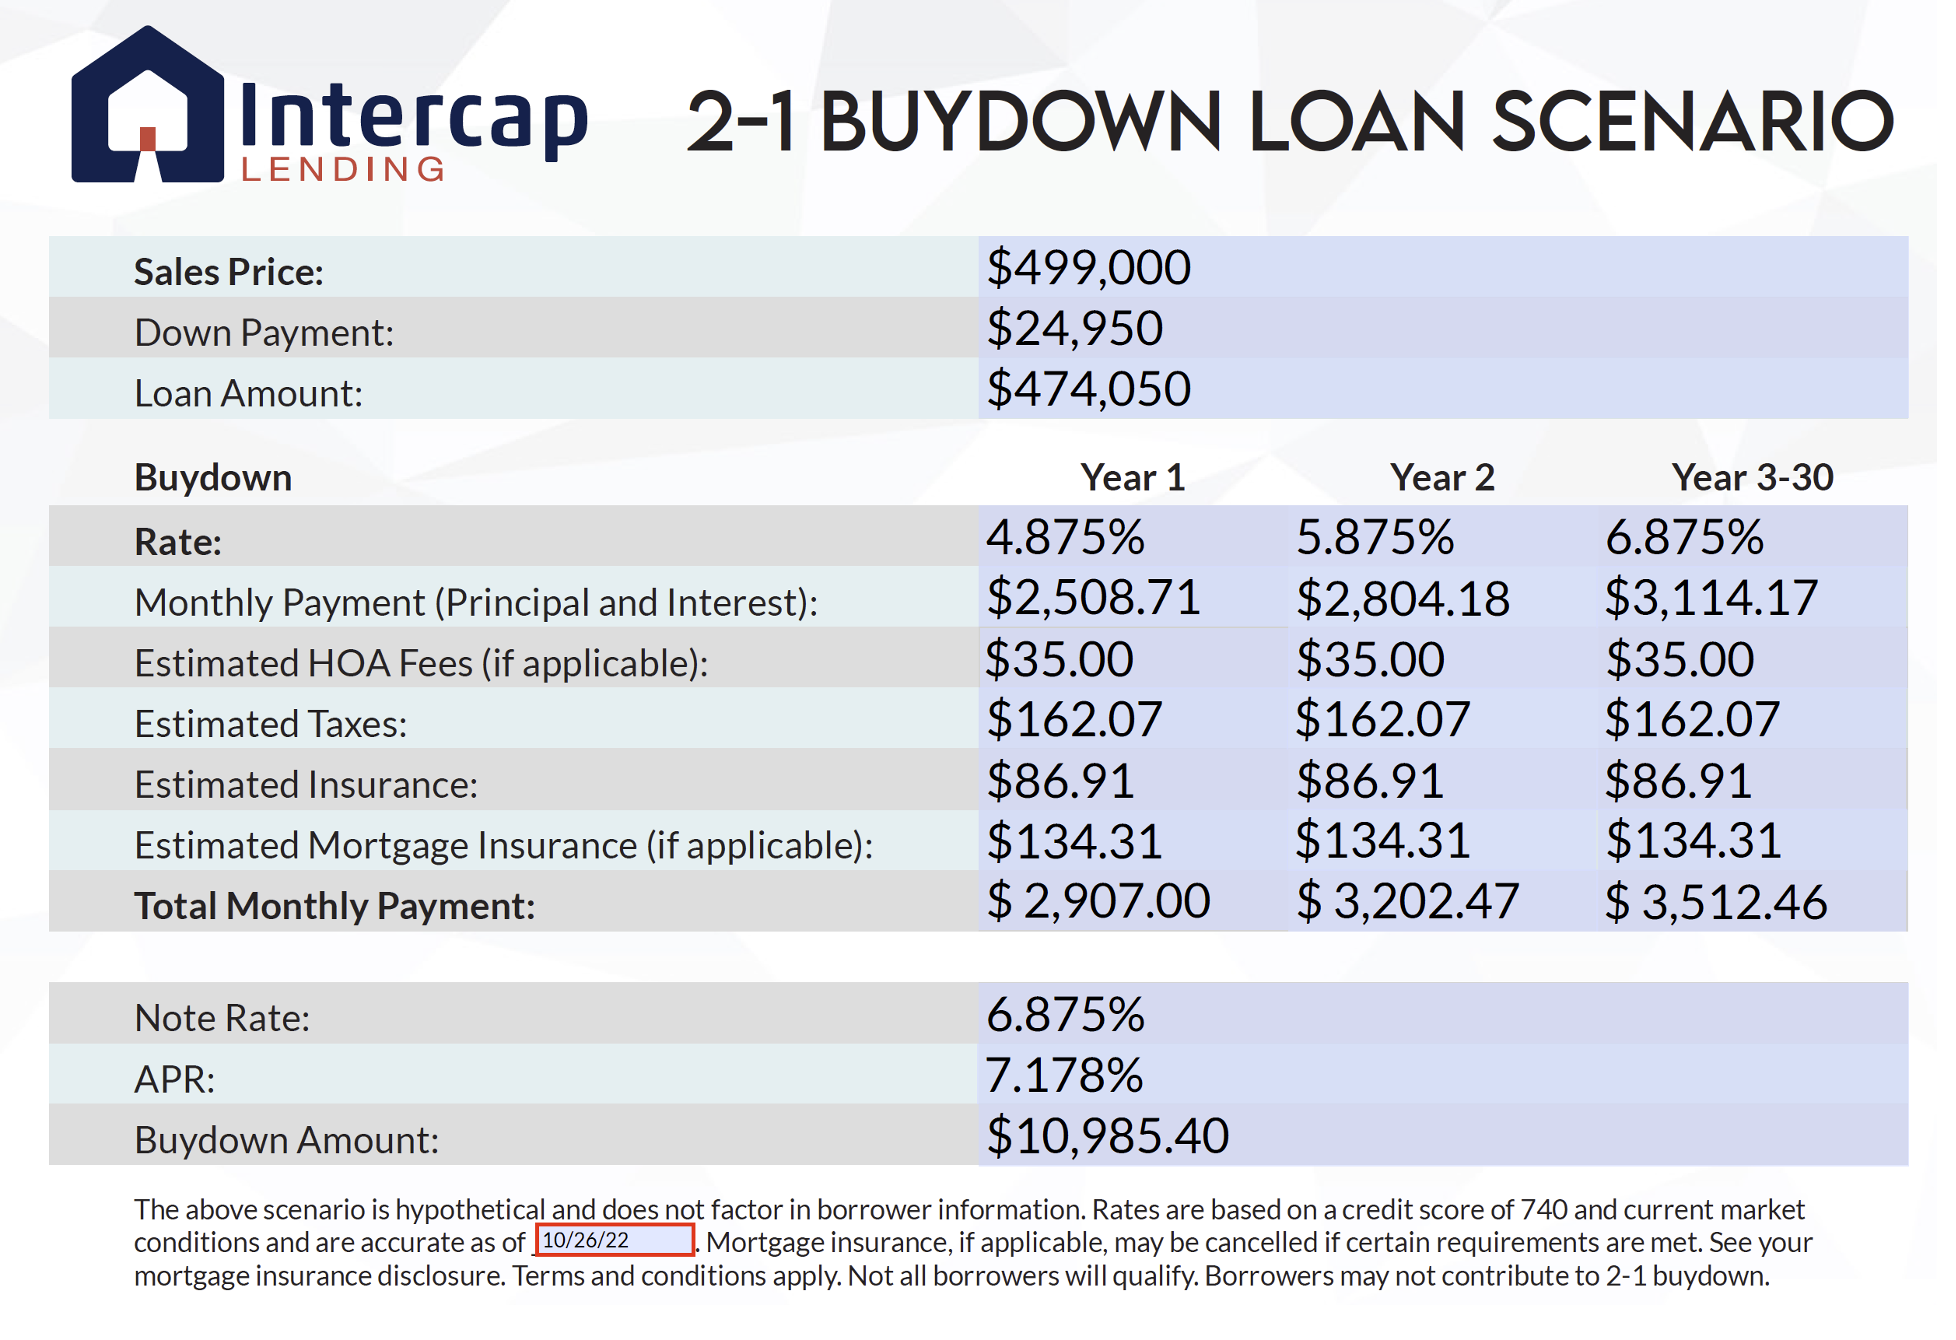
Okay, so you just fell in love with a house—congrats! But that mortgage interest rate is giving you mean eyes? Don't worry, we've all been there. The good news? There's actually a smart little trick called buying down your rate, and it could save you thousands over the life of your loan. Let's break it down together, shall we?
Think of buying down your rate like a threshold at a fancy hotel. The higher your upfront payment, the smoother your stay. In mortgage terms, you're paying discount points—basically fees upfront to slash your interest rate. One point usually equals 1% of your loan amount and buys you about 0.25% off your rate. Not a bad deal if you're planning to stick around!
Now here's where the fun begins—crunching the numbers. Let's say your loan is $300,000. One discount point costs $3,000. If it saves you $100 monthly, that's roughly 2.5 years to break even. Planning to stay longer? Sweet, you're in profit mode! But if you're moving in two years? Maybe keep that money for takeout instead.
Must Read
You can also explore seller or lender credits—sometimes negotiable with a little charm and a killer handshake. And hey, improving your credit score, increasing your down payment, or choosing a shorter loan term can naturally lower your rate too.
 Permanent Rate Buy Down Now Available! - Wayne Homes Blog
Here's the bottom line: buying down your rate is totally worth it if you run the numbers, know your timeline, and aren't afraid to chat comfortably with your lender. You've got this—your dream home is closer than you think, and that phone bill of a mortgage just got a whole lot friendlier.
Now go make that call, future homeowner—your wallet will thank you later! 😊