So picture this: you've been saving money like a maniac, stuffing every extra dollar under your mattress—or, you know, a fancy bank account. Then one day, your bank's CEO shows up on the news looking like he hasn't slept in a month. Panic? Nah. That's exactly where the FDIC swoops in like a financial superhero wearing a suit and tie.
What Even Is the FDIC?
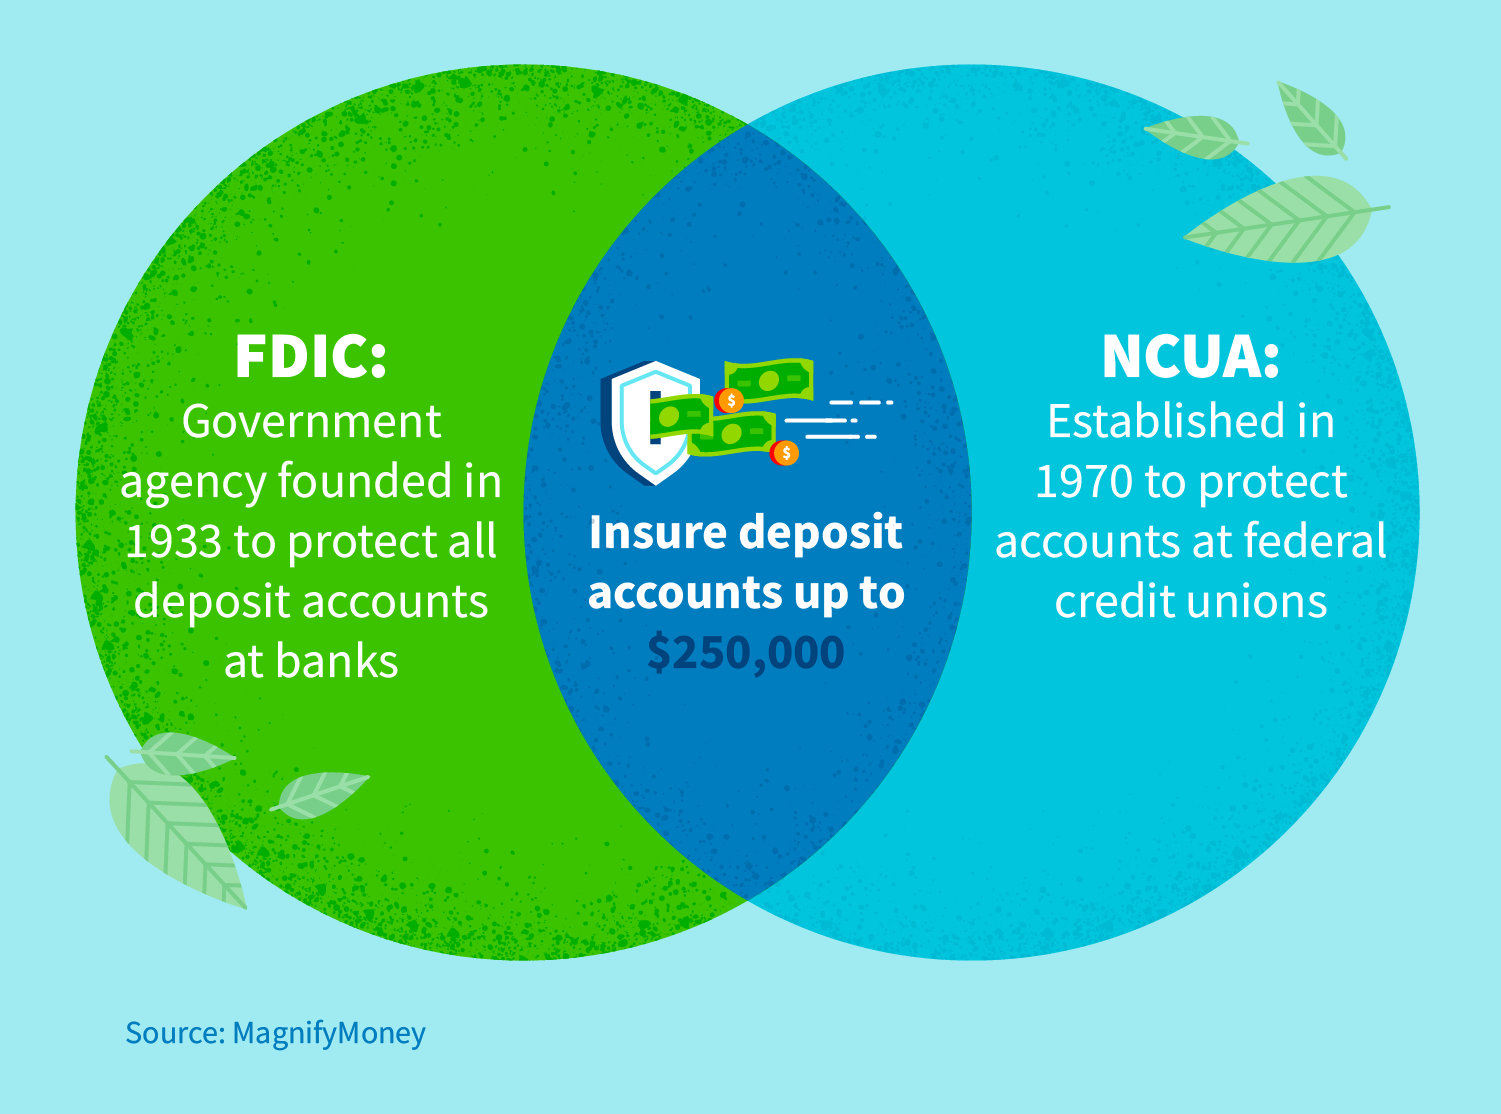
The Federal Deposit Insurance Corporation—which thankfully we call the FDIC instead of reading that mouthful every time—was created back in 1933. It came into existence during the Great Depression when banks were dropping like flies and people were losing their life savings faster than you lose socks in the dryer.
The FDIC is basically the government's way of saying, "Hey, we've got you covered." It insures your deposits at participating banks and credit unions so that even if your bank goes belly-up, your money doesn't disappear into thin air.
Must Read
How Does This Magic Actually Work?
Here's the deal: the FDIC insures up to $250,000 per depositor, per insured bank, per ownership category. That means if your bank crumbles tomorrow, you get your money back—every penny up to that limit. Imagine being the C-3PO of your bank, faithfully reassuring everyone that things are going to be fine.
And here's a fun one: in the past 100 years, no single depositor using an FDIC-insured bank has even lost a single cent of insured money. Not one. You're honestly more likely to find a parking spot at the mall than to lose FDIC-insured deposits.
 FDIC | Visbanking
What Exactly Is Covered?
Checkings, savings, money market deposits, and certificates of deposit—all covered. Stocks, bonds, and mutual funds sitting in your brokerage account? Not covered. The FDIC is only interested in those sweet, sweet deposit accounts.
IRA and retirement accounts also get a separate $250,000 limit, because the government recognizes that you'll absolutely lose your mind if your emergency fund disappears. It's almost like they've met Americans before.
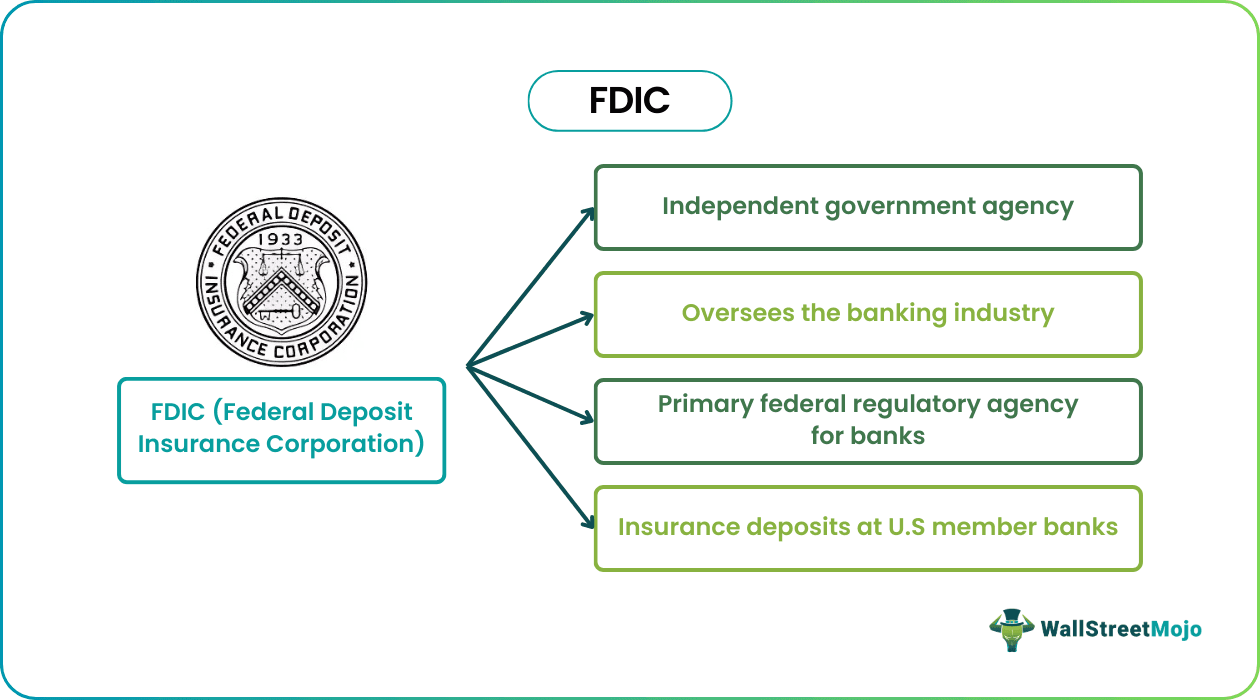 FDIC (Federal Deposit Insurance Corporation) - Meaning, Limit
How Do They Actually Pay When a Bank Fails?
When a bank fails, the FDIC steps in and either finds another bank to absorb it or—more commonly—insures the deposits directly. You'll receive a check in the mail or your funds transfer automatically, usually within days. Feel seen? You should.
The FDIC has actually failed over 500 banks since 2000 alone, and through all of this, not one insured depositor lost a dime of covered funds. That's a pretty solid track record for an organization most people can't name after five tries.
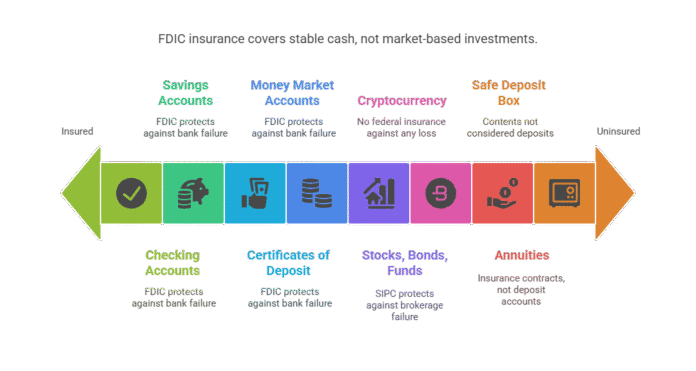 FDIC Insurance in 2026: The Complete Guide to Protecting Your Money
Why Should You Care?
The FDIC exists because banks can and do fail. It's not fun, but it happens—and knowing your money is protected gives you peace of mind. When people have confidence in the banking system, the entire economy benefits.
So next time someone says, "What if my bank goes under?", just smile calmly and drop some FDIC knowledge. You'll sound like a financial guru, and nobody needs to know you learned it while scrolling through the internet at 1 a.m. Knowledge is power—especially when it protects your wallet.