
Imagine you’ve got a sudden repair bill and you’re not sure where to turn? That’s where your 401k can step in like a friendly sidekick.
But how do you actually take a loan out of your 401k without sounding like a Wall Street trader? Let’s break it down together.
The Basics of a 401k Loan
First, check if your plan even allows 401k loans; many do, but some don’t. If it does, you’re already halfway to cash‑in‑hand.
Must Read
Most employers let you borrow up to 50% of your vested balance, capped at $50,000. Think of it as a personal advance from your own savings.
You’ll fill out a simple form, state the purpose, and choose a repayment term—usually 3 to 5 years. The process feels more like ordering a coffee than filing a tax return.
Why It Can Make Life More Fun
A 401k loan can fund a home upgrade, a dream vacation, or even that gadget you’ve been eyeing. Suddenly, your retirement account is also your fun fund.
Because you’re borrowing from yourself, interest you pay goes back to your account instead of a banker’s pocket. It’s like earning a tiny side hustle on your own money.
 How to Repay 401k Loan After Leaving Job - Quiver Financial
And the best part? You keep both hands on your retirement future while unlocking immediate cash. No need to dip into high‑interest credit cards.
Of course, the loan does pause contributions while you repay, and any unpaid balance can become a distribution if you leave the job. So it’s a short‑term sprint, not a long‑term marathon.
If you decide to repay early, you’ll just give back the principal plus the accrued interest quickly. That’s a win‑win for both you and your future self.
Just be sure the monthly payment fits comfortably in your budget; a loan shouldn’t cause stress. Think of it as a fun muscle‑building exercise for your finances.
 How to Repay 401k Loan After Leaving Job - Quiver Financial
And hey, if you’re feeling adventurous, the extra cash could fund a weekend road trip you never thought you’d take. Life’s too short to skip the adventure because you’re worried about a bill.
Remember, the loan doesn’t increase your total debt—it only rearranges the money you already saved. It’s a bit like moving furniture in a house: same space, fresh look.
When the final payment clears, your 401k balance will be back where it started, plus any interest you earned. Suddenly you’ve turned a temporary need into a longer‑term benefit.
So the next time an unexpected expense pops up, consider tapping your 401k loan before panic sets in. You’ll feel empowered, not helpless.
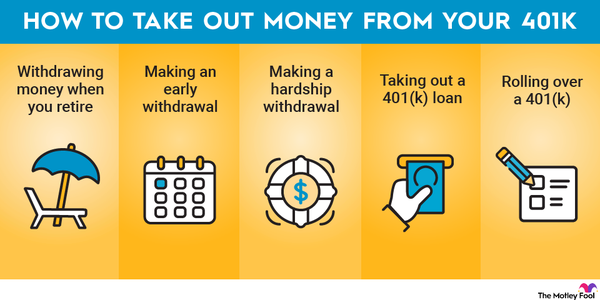 How to Take Money Out of Your 401(k) | The Motley Fool
And if you’re unsure, talk to your plan administrator; they can walk you through every step. Knowledge turns a scary decision into a breezy conversation.
By mastering this process, you’ll feel like you’ve unlocked a secret level in the financial game. Who knew retirement planning could be this upbeat?
Take a breath, smile, and remember: your future self will thank you for being bold today. Keep learning, stay curious, and watch your money work for you.
If you ever catch yourself wondering whether a 401k loan is right for you, grab a notebook, jot down the pros and cons, and watch the clarity appear. You’ll be amazed at how three notes can turn confusion into confidence.
Ready to explore more? Dive into your plan details, chat with peers, and let curiosity guide you toward smarter, happier finances. The journey is just beginning!