Okay, so you just pulled your credit report, and guess what? There's something wrong on it. Maybe someone opened a credit card in your name, or a bill you paid shows up as unpaid. Don't panic — this happens way more often than you'd think.
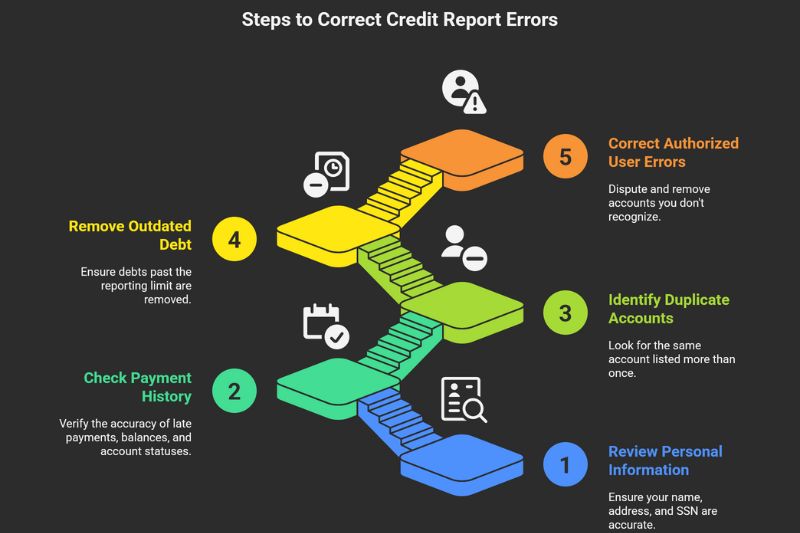
First things first: grab all three reports from the major bureaus — Equifax, Experian, and TransUnion. You can snag those for free once a year at AnnualCreditReport.com. Go through them like a detective looking for clues. Trust me, you aren't being paranoid. You're being smart.
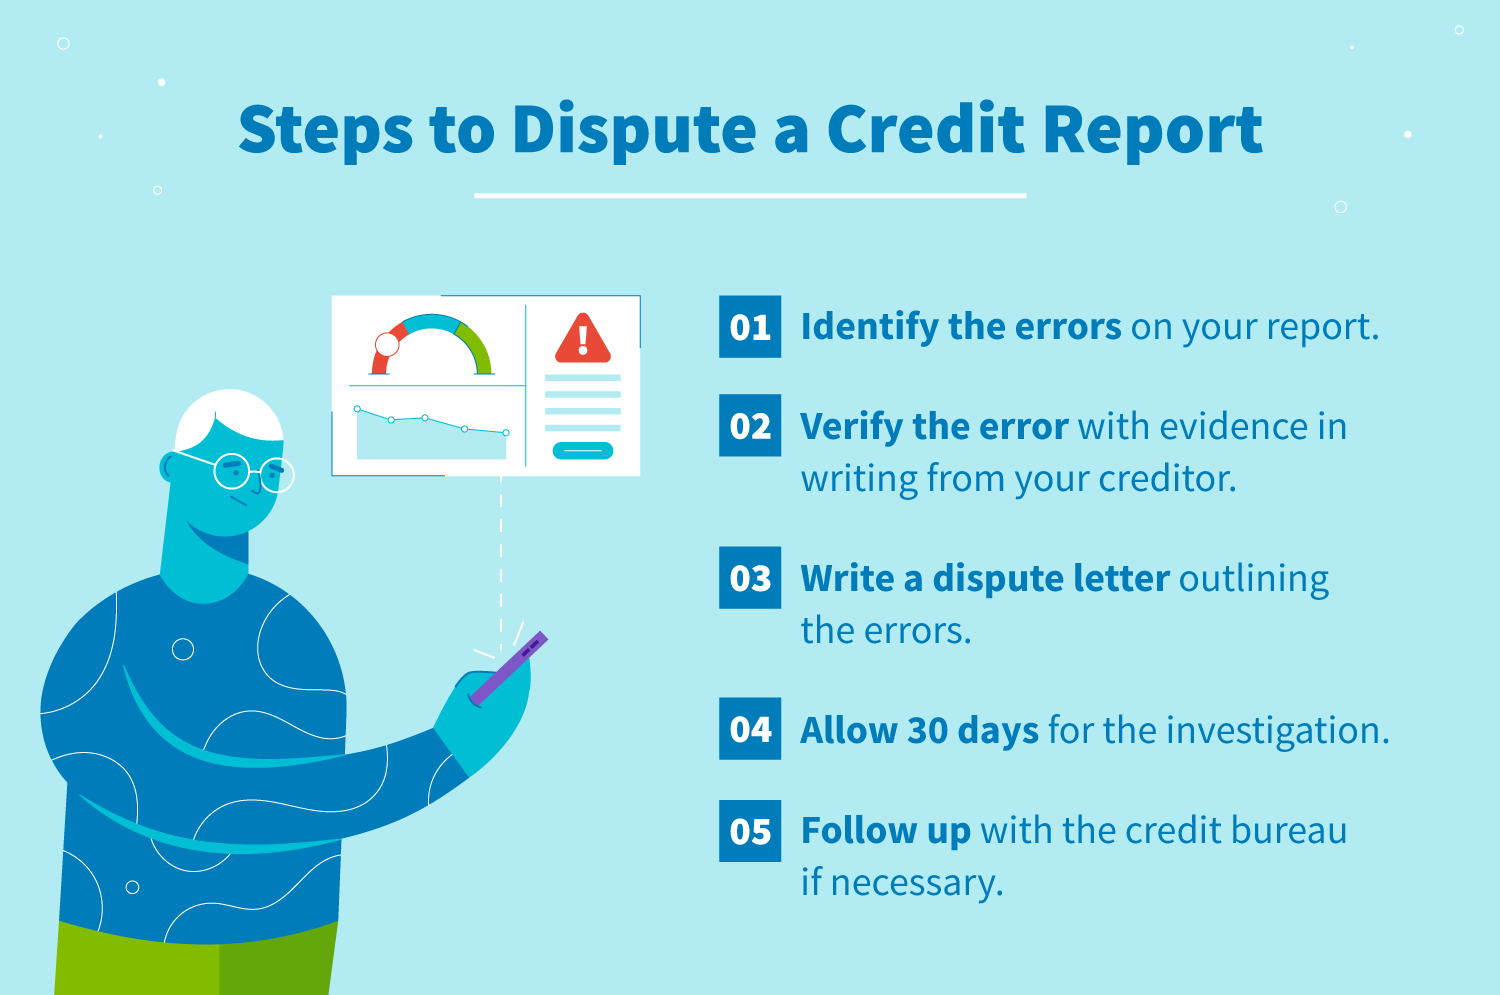
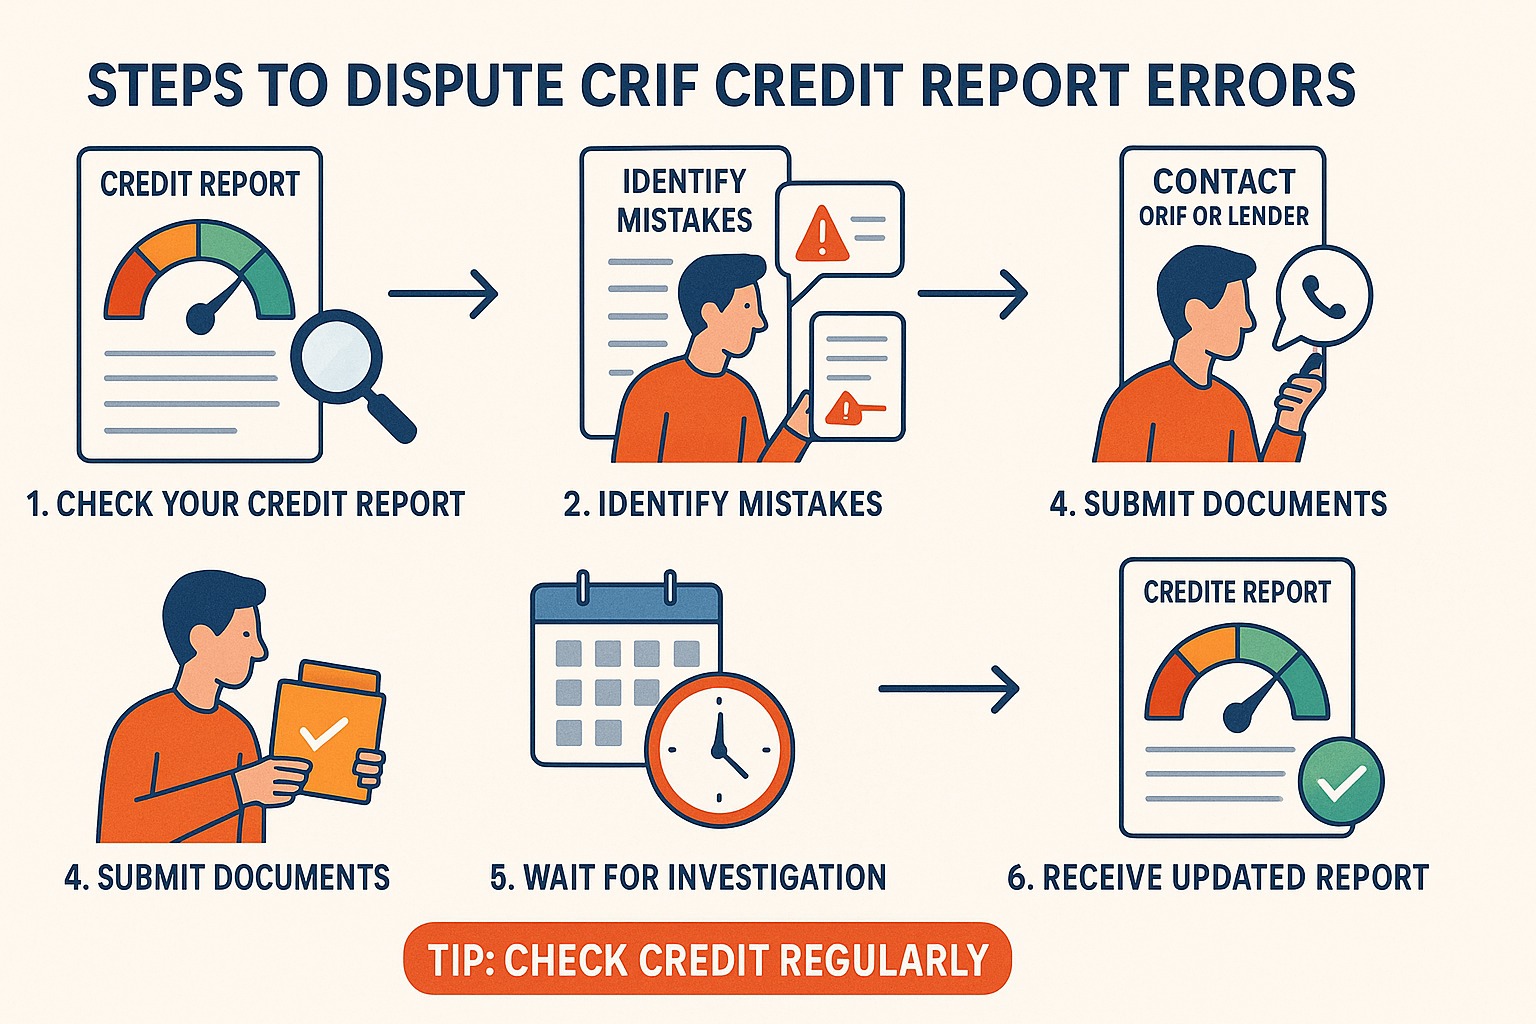
Found an error? Time to fight back. Write a formal dispute letter — yes, a real letter, old school style — identifying each mistake clearly. Attach copies of supporting documents like payment receipts or statements. Send it certified mail so there's a paper trail. Because who doesn't love knowing exactly where their letter went?
Must Read
The bureaus typically have 30 days to investigate and respond. They'll contact the creditor on your behalf and correct anything that checks out. If the creditor disagrees? You can still add a personal statement to your report explaining your side of the story.
Here's a little secret: most disputes are actually easier to resolve than people assume. Once, I talked a friend through it over coffee, and her score jumped 40 points in a month. Not bad for a cozy afternoon activity.
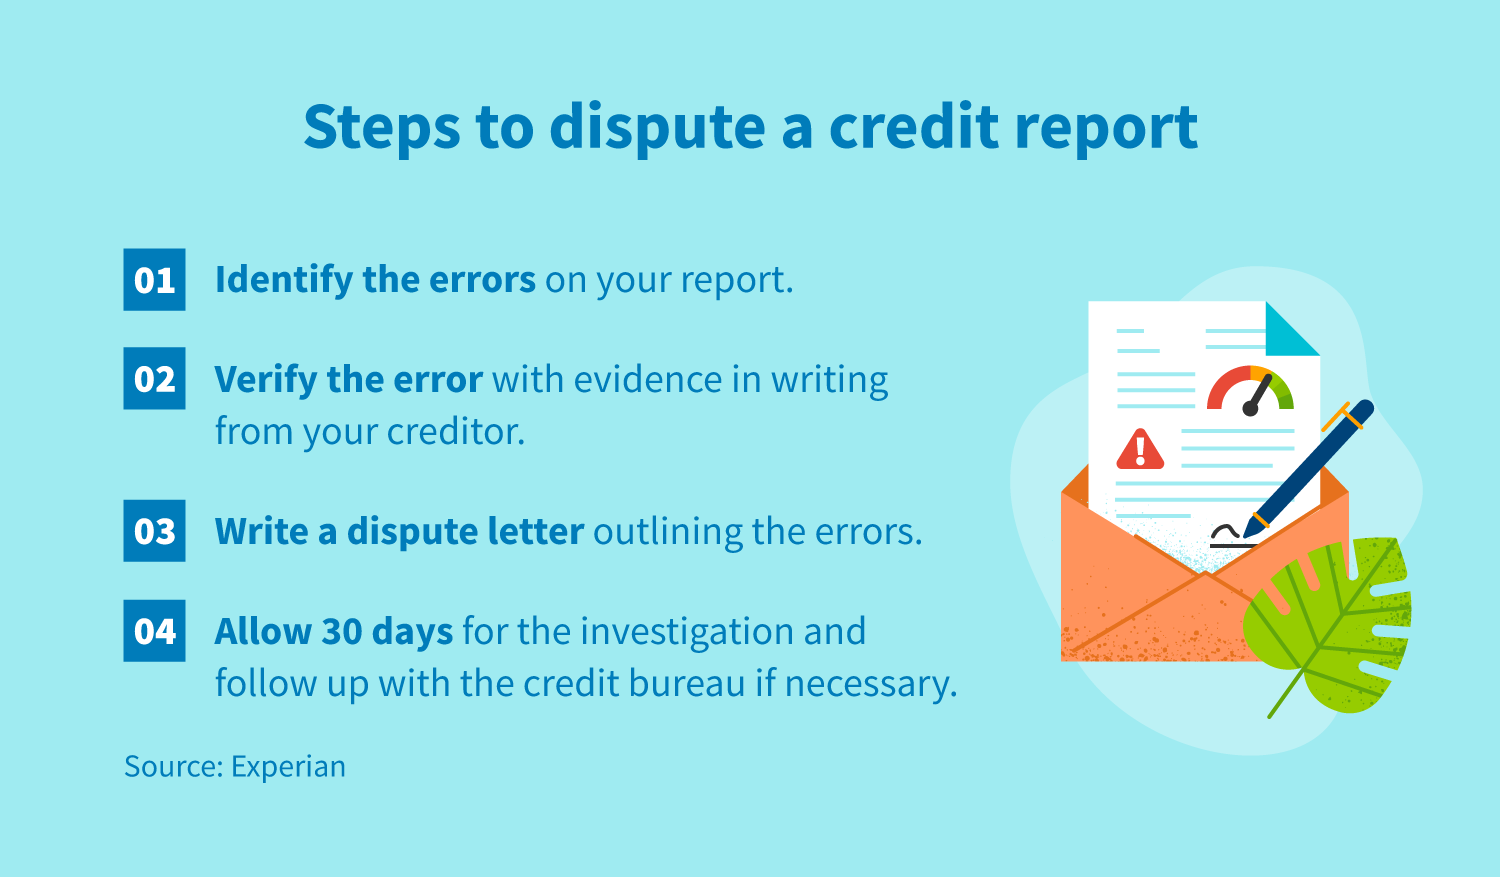 How to Dispute a Credit Report | CreditRepair.com
Remember, your credit report is your financial story, and nobody's going to correct the chapters for you. Take charge, speak up, and watch how satisfying it feels when those errors disappear like an old ex from your contact list.
You've got this. Now go bring that report to its senses and treat yourself afterwards — you deserve it! 🎉