So, you're eyeing that swanky apartment or eye-watering car loan, and you want to know your FICO score — the big boss of credit scores that lenders actually trust. But then you remember CreditWise, that free tool from Capital One, and wonder: can it really tell me what banks see?
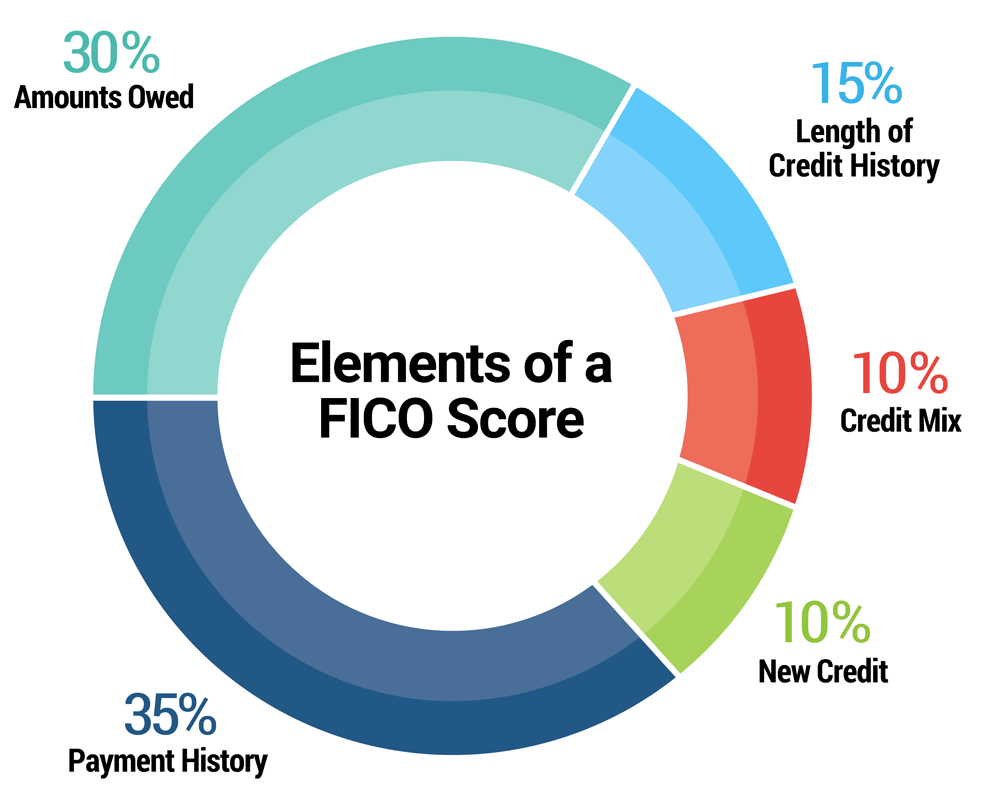
Here's the deal: CreditWise uses the VantageScore 3.0 model, which is the cousin of FICO — not the identical twin. Think of them as siblings raised in the same house but who went to different schools. They both care about your payment history, credit utilization, and length of credit relationship, but each weighs those factors slightly differently.
In practice, monitoring your score through CreditWise will generally put you within a ~5 to 20 point range of your actual FICO score. So if CreditWise shows you at 740, your FICO might sit at 735 or 745 — close enough for comfort, but definitely not an exact mirror.
Must Read
Is that close enough to sleep peacefully at night? Mostly yes! CreditWise is excellent for tracking trends. If your score is climbing steadily there, your FICO almost certainly is too. You'll spot red flags — like late payments or skyrocketing utilization — long before they cause serious damage.
However, if you're making a major financial move — applying for a mortgage, for instance — you'll absolutely want your exact FICO score. Lenders pull it directly when evaluating you, and those tiny point differences can swing your interest rate in surprising ways.
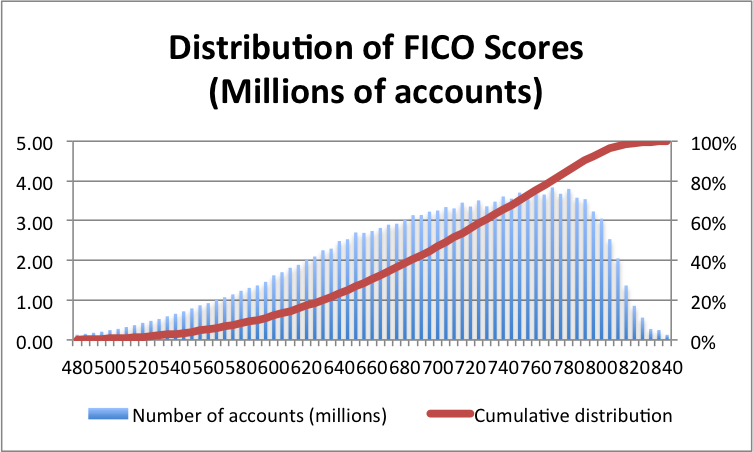 How a credit score is calculated, and how objective it is? – From
So here's our practical takeaway: let CreditWise be your daily companion, your credit fitness tracker, if you will. Check it regularly, celebrate the wins, and fix the slip-ups. But remember that it's a helpful signpost, not the final destination.
The good news? Maintaining solid habits through CreditWise means you'll walk into any credit check feeling confident, smiling wide, and ready for whatever life throws your way. You've already got this! Go ahead and flex that financial wisdom — you've earned it.