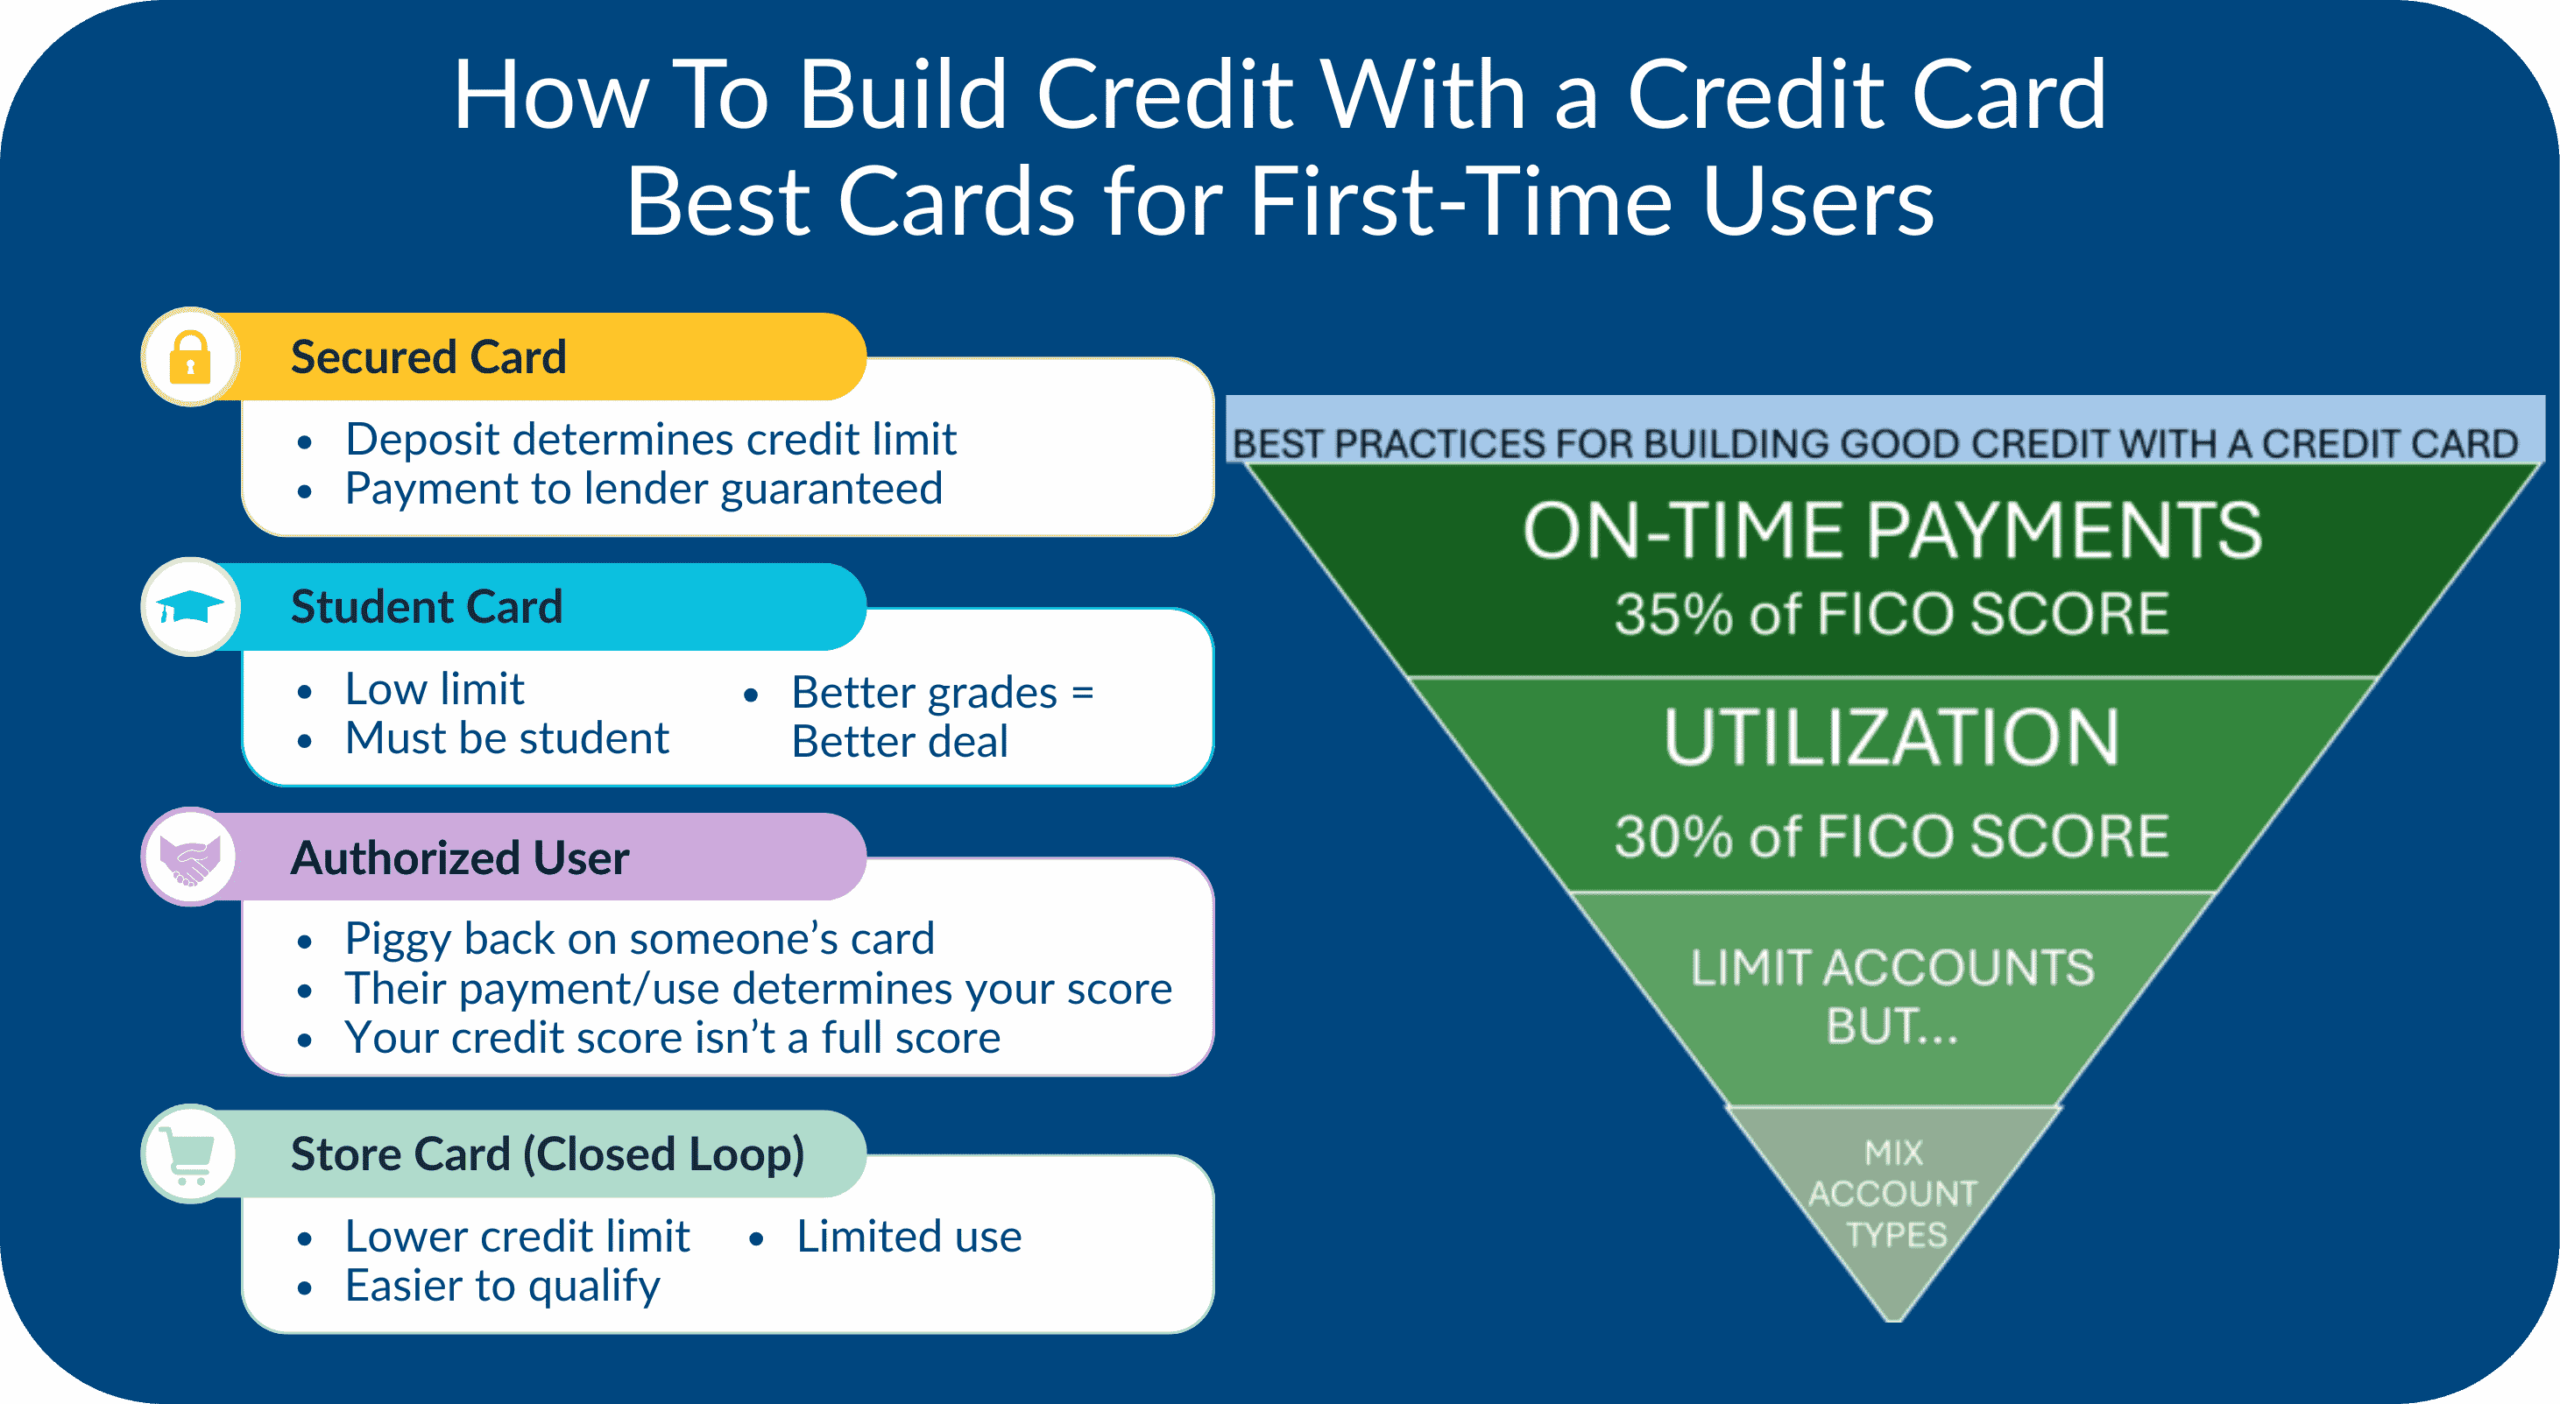
Many people love the freedom a first credit card brings. It offers purchasing power, convenience, and the opportunity to start a positive credit history early on. For students, recent graduates, and anyone new to credit, choosing the right card is an exciting first step toward financial independence and a strong financial future.
The primary purpose of a first credit card is to build credit responsibly. Every on-time payment you make gets reported to the major credit bureaus, gradually raising your credit score. A healthy score later unlocks better interest rates on loans, favorable mortgage terms, and even lower insurance premiums — making it a valuable long-term asset.
For everyday life, a good starter card makes routine spending simpler. Imagine buying groceries, paying for gas, or ordering dinner out — you can track all of these expenses in one place. Many reward cards also earn cashback or points on common purchases, turning your daily spending into small but meaningful savings.
Must Read
Situations like renting an apartment or applying for a car loan show why credit matters. A young professional who responsibly manages her starter card for six months may find lenders are far more willing to approve her requests. That early credit foundation can make the difference between an easy approval and a frustrating rejection.
 Best Credit Cards for Beginners (USA Guide) - Statush.com
To explore options on your own, consider starter cards designed for applicants with no or limited credit, including secured cards that require a small deposit. Always compare annual fees, interest rates, and reward structures before applying. Set up automatic payments to avoid missed due dates and keep your credit utilization below 30% of your limit.
Finally, read reviews and check qualification requirements before submitting an application to avoid unnecessary hard inquiries. With careful selection and consistent habit-building, your first card can serve as the cornerstone of a sturdy credit profile for years ahead.

