Many homeowners and sellers find escrow accounts reassuring, and it's easy to see why. They add a layer of protection and fairness to some of life's biggest transactions, reducing stress for everyone involved. People value having a neutral third party handle money because it removes guesswork and builds trust between buyers and sellers.
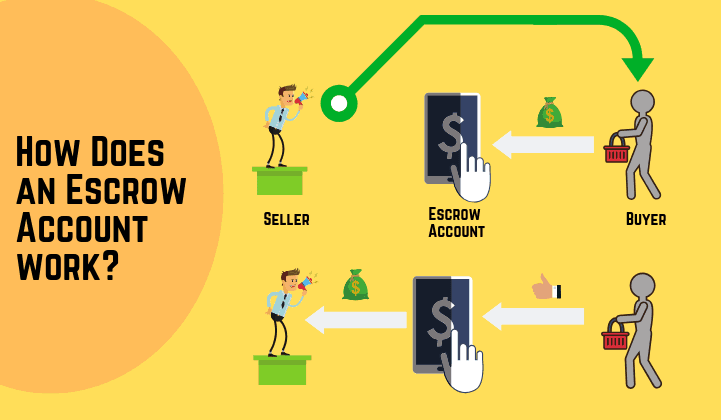
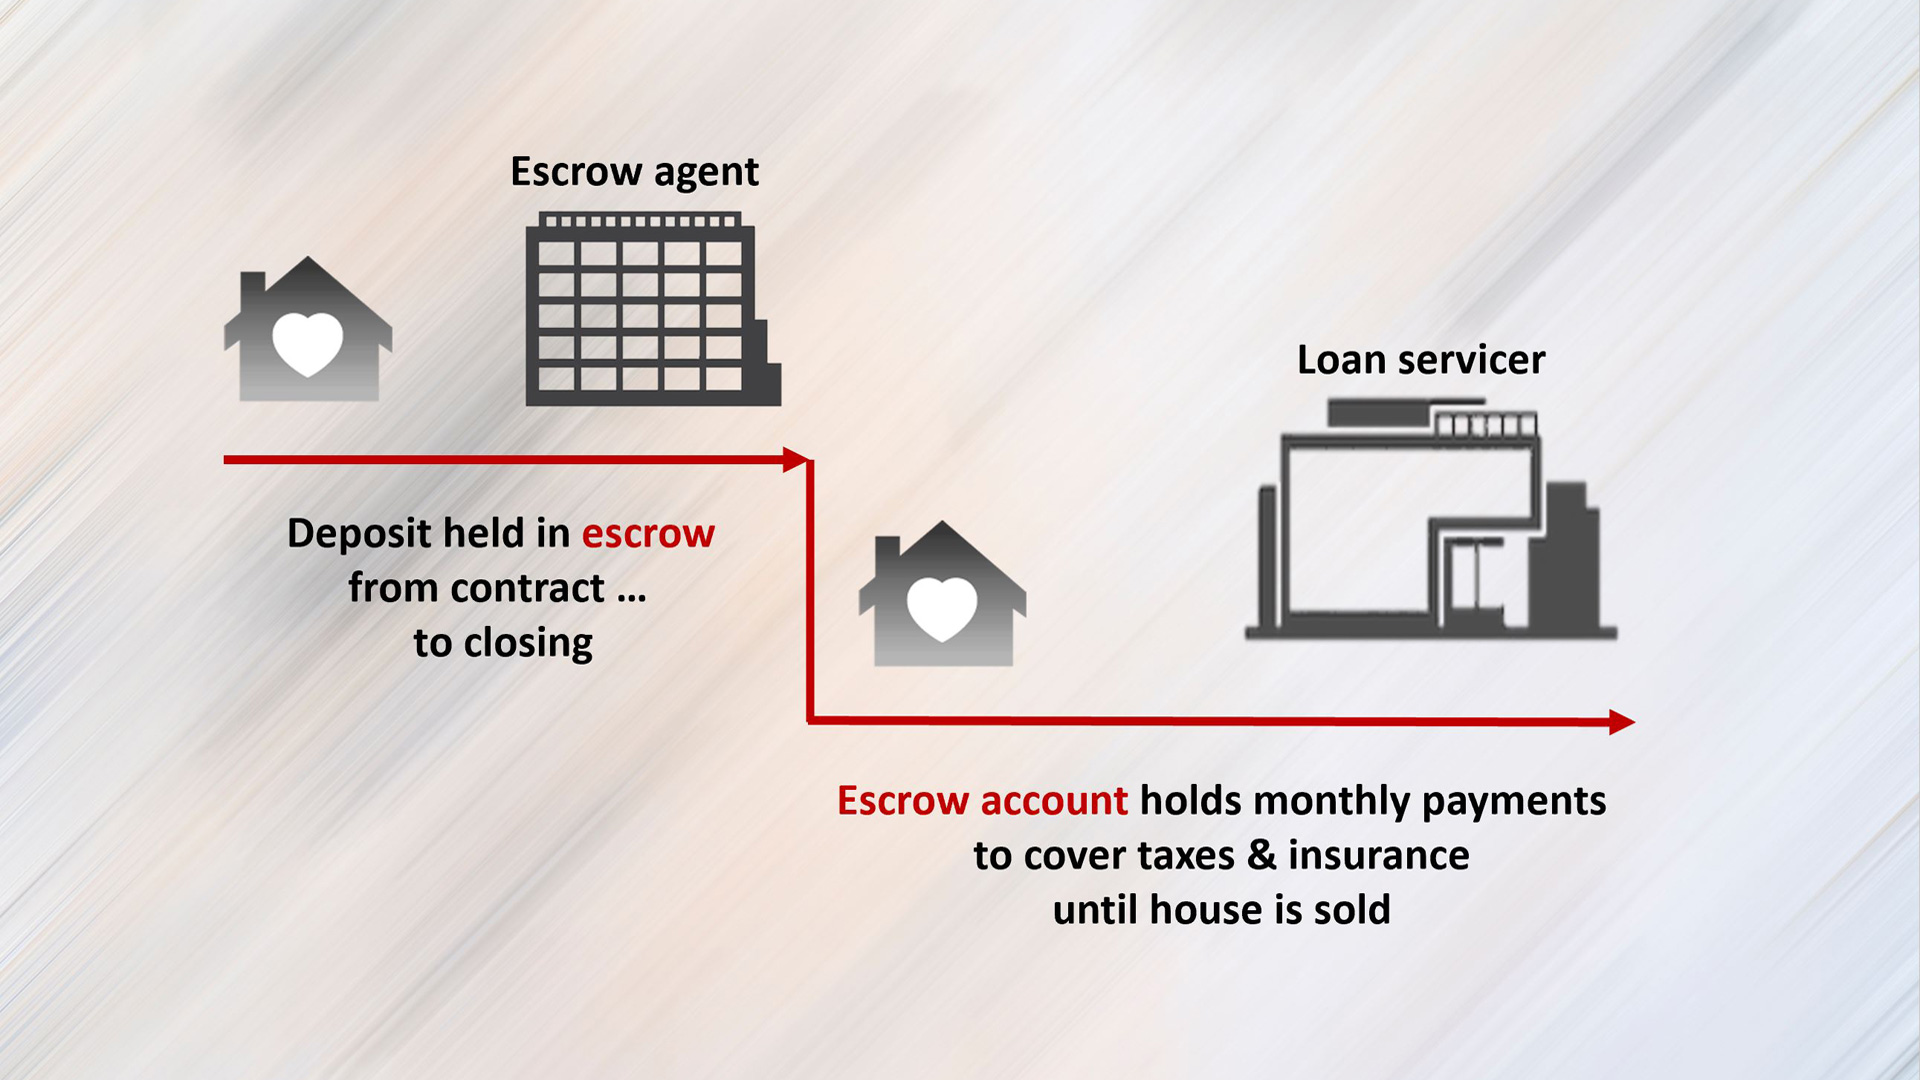
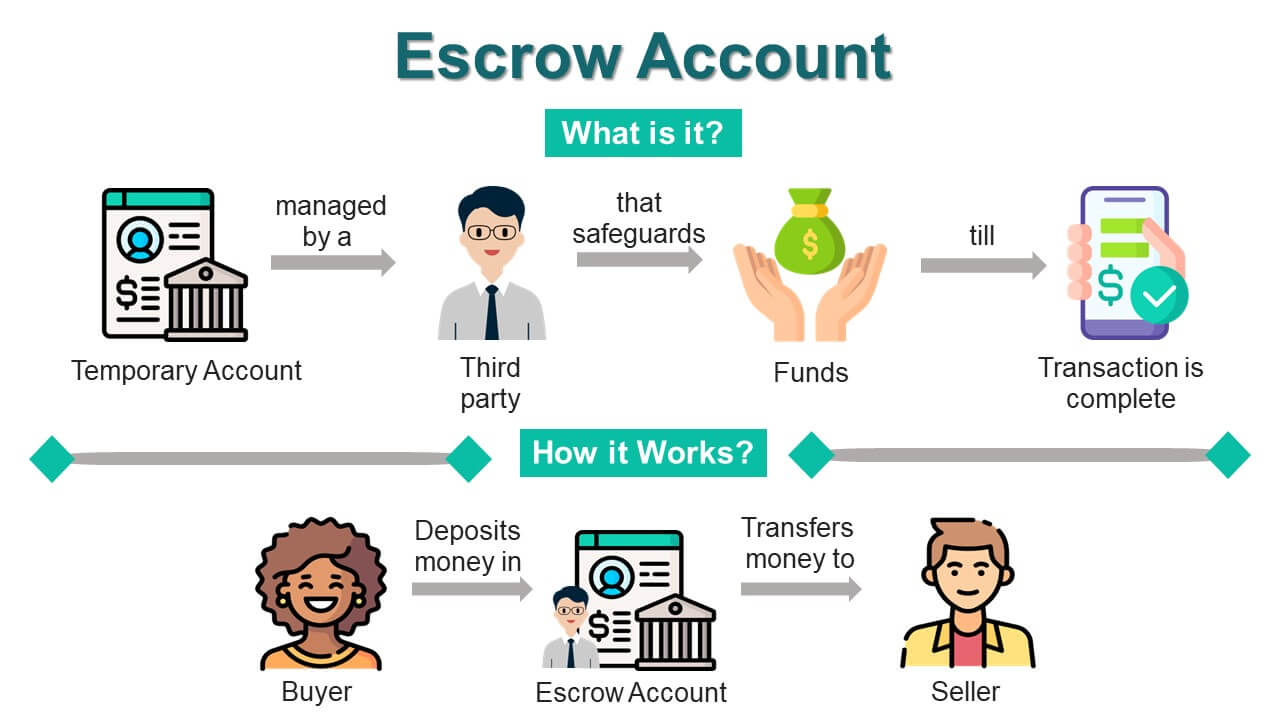
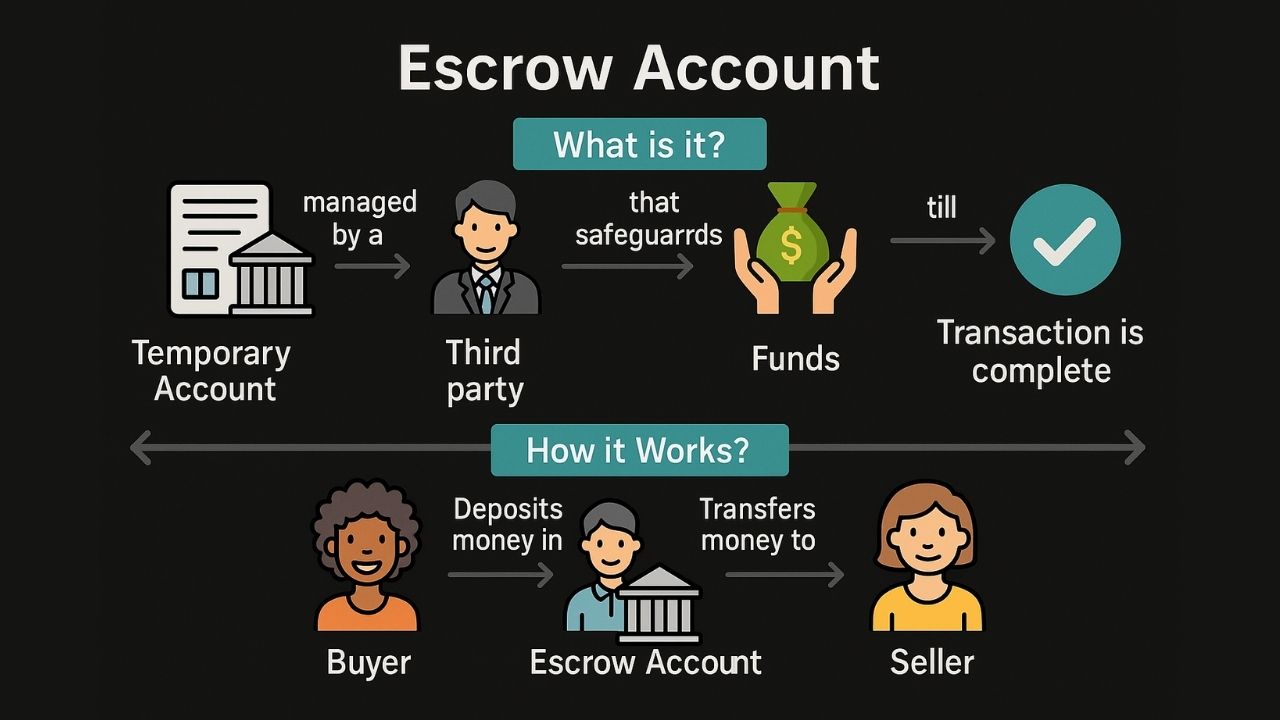
The key purpose of an escrow account is to temporarily hold funds or documents during a transaction until agreed-upon conditions are met. In real estate, this means the buyer's down payment stays safe until the home closes. For insurance and taxes, servicers often set up escrow to collect monthly payments and cover annual bills automatically. Having an escrow account makes sendescity feel manageable.
One of the biggest everyday benefits is budgeting simplicity. Instead of scrambling to come up with thousands of dollars for property taxes or homeowners insurance in one lump sum, you spread the cost across smaller monthly payments. This steady approach helps families avoid financial surprises while keeping obligations current.
Must Read
However, escrow accounts are not always required. Conventional mortgages with 20% or more down often let you waive escrow entirely, opting instead to pay taxes and insurance on your own schedule. Some states have laws that restrict or prohibit lenders from requiring escrow under certain conditions. So the answer to whether you need one depends on your loan terms, lender policies, and local regulations.
 What is an Escrow Account & How it Work in Real Estate in UAE
Consider a first-time buyer putting 25% down on a home. Their lender may offer the choice to skip escrow, but the buyer realizes that budgeting separately for a $6,000 annual tax bill feels risky. In that scenario, choosing escrow provides peace of mind and keeps everything organized, while another buyer with a tight budget-freeing mindset might prefer the flexibility of paying independently.
To explore this further, start by reviewing your mortgage agreement and contacting your lender about available options. Research whether your state imposes escrow rules and compare the costs of managing payments yourself versus using an escrow service. Finally, use online escrow calculators to project monthly amounts so you can make a confident, informed decision about what's right for your financial situation.