
Hey there, fellow freelancer! Ever wondered whether you need to shell out that extra chunk called the self‑employment tax? Don’t worry—this fun little guide will break down the mystery, show you why it matters, and help you feel empowered about your money.
The self‑employment tax exists because you’re not just earning bucks—you’re also adding to Social Security and Medicare funds. Knowing when it applies can prevent nasty surprises, keep you in good standing with the IRS, and even let you claim the full credit for those contributions.
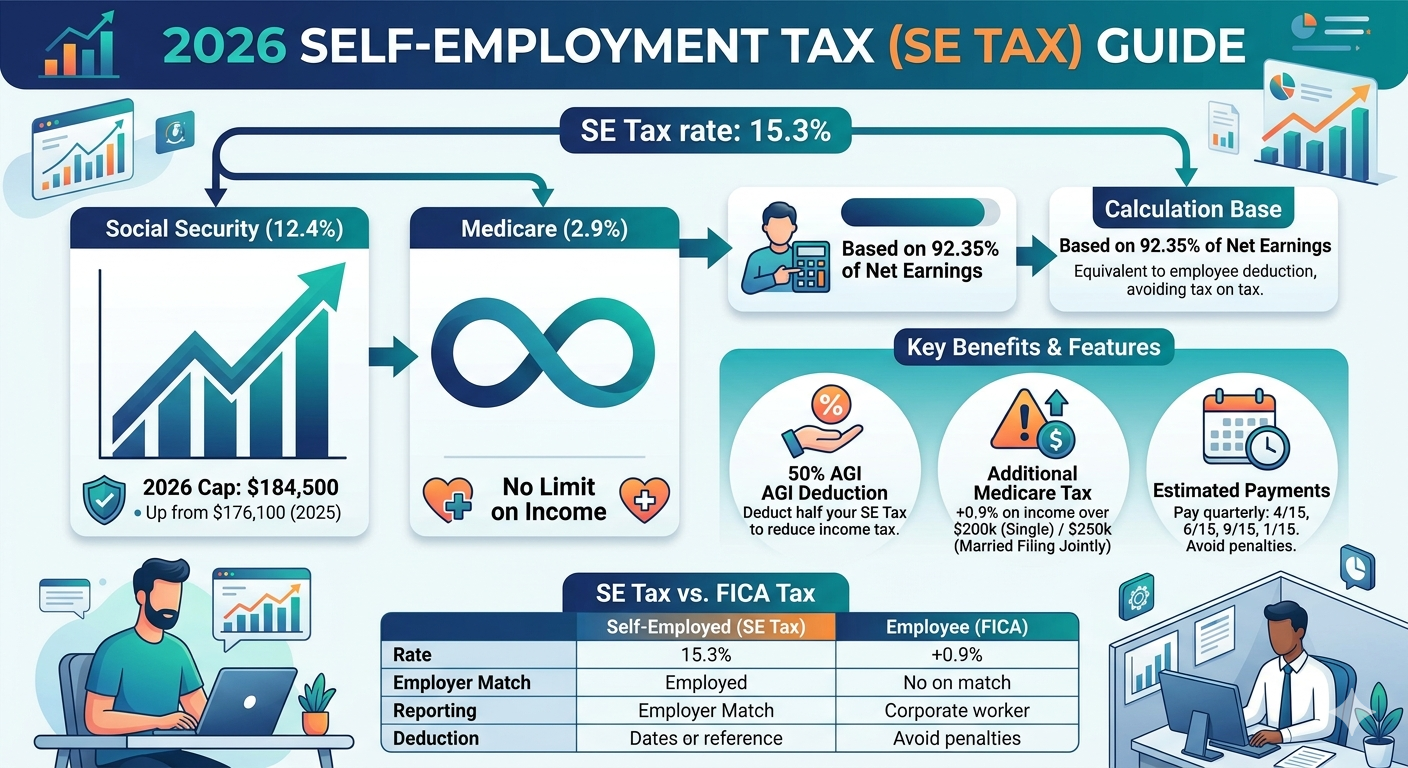
Picture a graphic designer who brings home $60,000 a year. After subtracting business expenses, she’ll owe self‑employment tax on the net profit, roughly 15.3%—but she can deduct half of it as a personal expense. Imagine the extra cash she can reinvest in new gear or a short holiday.
Must Read
Consider a side‑hustle blogger earning $12,000 from ad revenue. He’s under the threshold where health insurance bonuses apply, yet he still must pay self‑employment tax—here the tax base is just his earnings, and he can offset it with reasonable home‑office deductions and maybe a bit for his internet bill.
To dodge surprises, set aside 20‑30% of each invoice for taxes, keep a simple spreadsheet, and use free IRS calculators to estimate your liability each quarter. Planning ahead turns tax season from a panic into a routine check‑in and you’ll breathe easier when the form appears.
 What is a Tax Liability? - Ramsey
So, do you have to pay self‑employment tax? If you earn income that’s not subject to a traditional payroll, the answer is usually yes—but the benefits offset the cost. Understanding the rules gives you confidence, lets you budget wisely, and keeps your entrepreneurial spirit thriving.
Remember, tax laws change—stay updated, and consider consulting a pro if your earnings get complicated. Keep it fun, keep it simple!
 Blog Images/Blog Images/Self-Employment Taxes in the US.png)