
So you've decided to buy a house. Congratulations — you've officially entered the most expensive game of Monopoly ever created. But before you start dreaming about marble countertops and a backyard gravel path, let's talk about the number that stands between you and your front door: your credit score.
Your credit score is basically your financial report card as an adult. No one ever explained why your entire mortgage destiny rests on three mysterious digits, but here we are. It ranges from 300 to 850, and anything above 700 generally means lenders will send you a gold platter invitation.
The Magic Numbers Everyone Talks About
Most conventional lenders prefer a score of at least 620. Below that, your loan application might get gently rejected like one of those emails from your ex. Think of 620 as the minimum height requirement for a rollercoaster — you're just barely tall enough to ride.
Must Read
If you cruise into the 670 to 739 range, you're in "good" territory, and lenders start being friendlier than your barista during happy hour. At 740 and above, you're basically the VIP of mortgage seekers who gets to skip the line and enjoy lower interest rates.
What About FHA and Government Loans?
FHA loans are the introverts of the mortgage world — they accept a credit score as low as 580, and sometimes even 500 with a hefty down payment. This makes homeownership accessible to folks whose credit has seen better days, like a car that's been parked under a bridge since 2019.
 What Credit Score is Needed to Buy a $250,000 House?
VA loans and USDA loans also offer flexibility since they cater to specific buyers like veterans and rural residents. The government essentially hands out "second chance" cards to keep the American dream alive. Pretty cool, right?
Down Payments and Interest Rates Play Along Too
Here's a surprise: your credit score directly affects your interest rate, which directly affects how much money you hand over to the bank over 30 years. A higher score could save you tens of thousands of dollars, and nobody talks about this enough. That money could buy you an absurd number of tacos instead.
 Credit Score Needed to Buy a House - YouTube
Most experts recommend you keep a down payment of at least 20% to avoid PMI (private mortgage insurance), which is essentially an additional fee the lender charges for not trusting you completely. With a lower credit score, lenders may also want a heavier down payment to cushion their risk. So your score really does matter more than you'd think.
Tips to Boost Your Score Before House Hunting
Start by paying off small debts and keeping credit card utilization below 30% — lenders breathe easier when you're not maxing out every card like going all-in at a poker table. Resist the urge to open new credit accounts right before applying for your mortgage; lenders find that suspicious. It's like going on a diet the day before Thanksgiving.
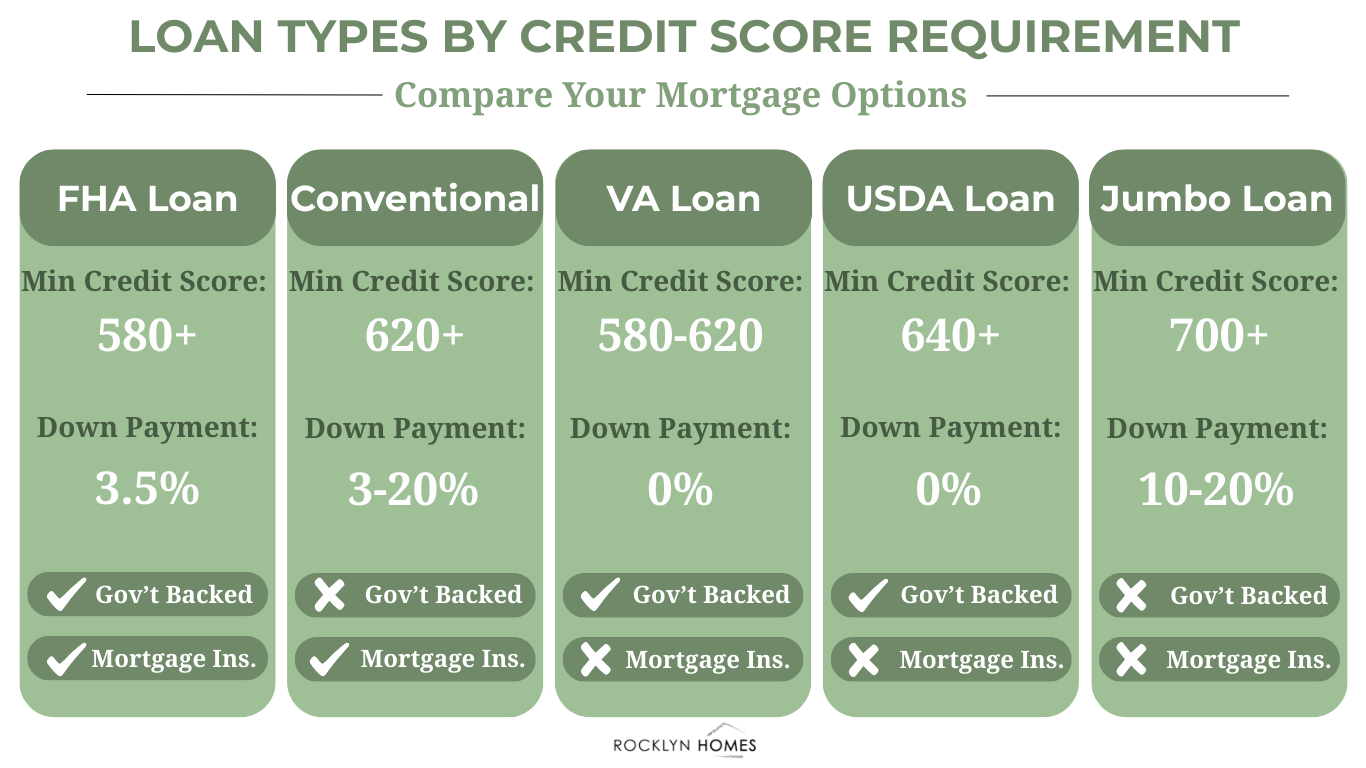 Credit Score Needed to Buy a Home: Complete Guide
Check your credit report for errors, dispute any mistakes, and pay every bill on time like your future dream kitchen depends on it. The whole process usually takes three to six months of steady habits before you see meaningful results. Patience pays — literally.
The Bottom Line
Your credit score is the bouncer at the house-buying club, but with some smart financial moves, you can get on the VIP list. Start early, stay consistent, and don't panic over every single point. Your dream home is closer than you think — just let your score do most of the talking.