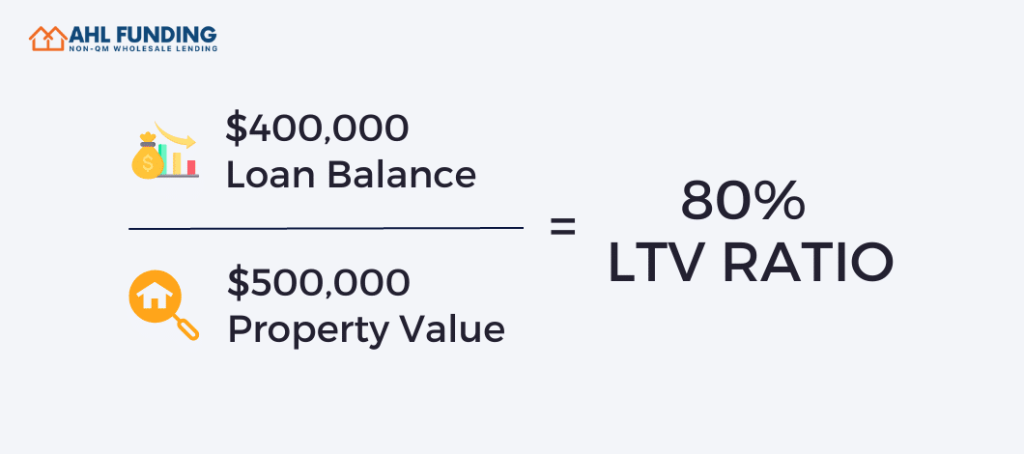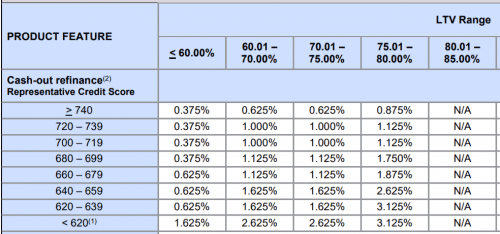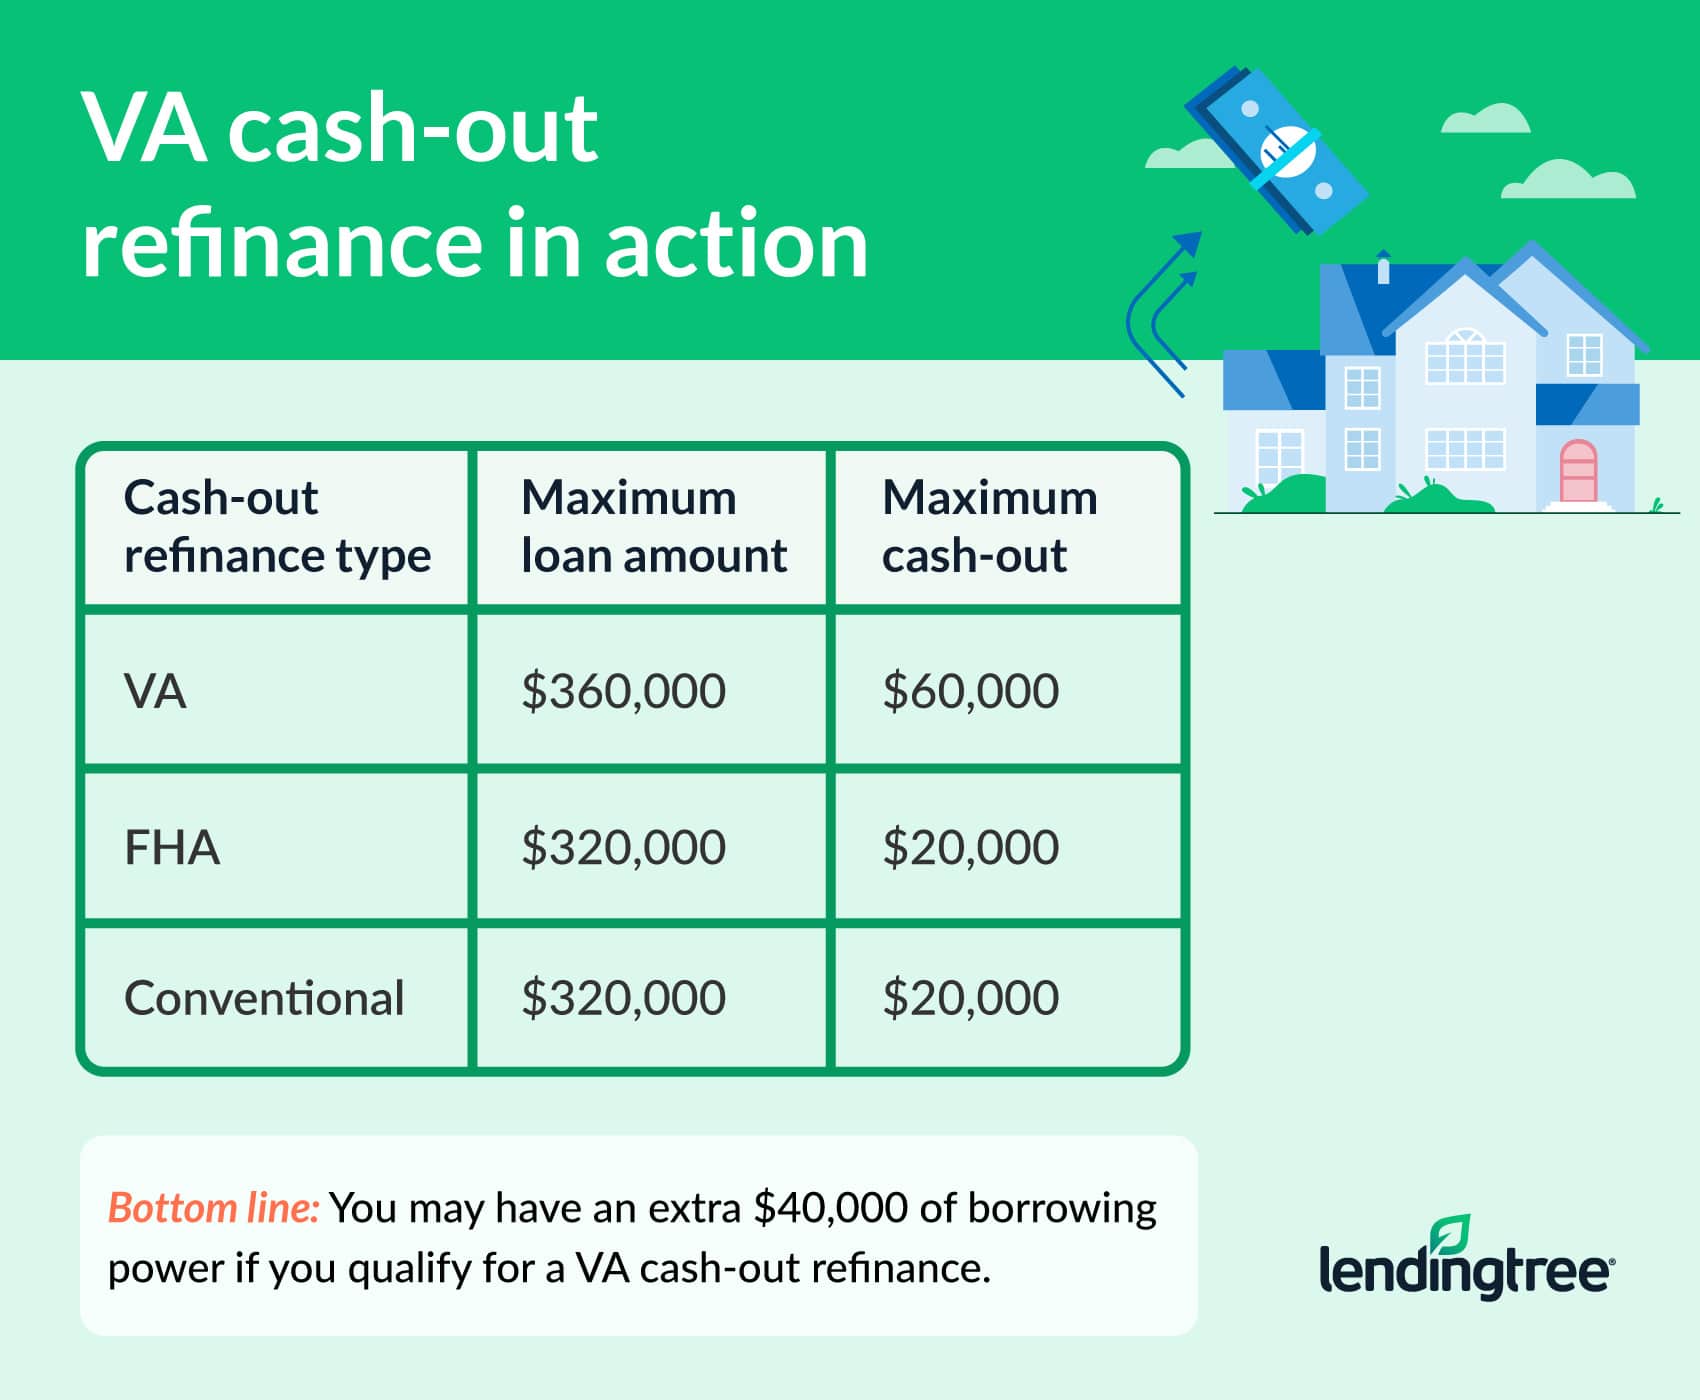
Cash‑out refinance and loan‑to‑value (LTV) ratio have become a go‑to tool for homeowners who want to tap equity without moving. In today’s market, lenders see this approach as a reliable way to keep cash flowing while keeping the house put. The ratio tells you how much you can qualify for, making the process feel concrete and manageable.
For families, a favorable LTV ratio means they can secure a lower interest rate because lenders view the risk as modest. Lower payments free up monthly budgets for school supplies, car repairs, or a weekend getaway. This extra flexibility can reduce stress and give everyone a little more breathing room.
Neighbourhoods benefit too when homeowners reinvest their cash‑out funds. Money spent on a home remodel can lift property values, encouraging other owners to upgrade as well. Often you’ll notice a rise in curb appeal, which also makes the area more attractive to new residents and boosts local business.
Must Read
Mary and John used a cash‑out refinance to consolidate credit‑card debt, cutting their monthly outflow by $400. In another case, a senior couple tapped equity to fund a backyard garden, creating a spot where grandchildren love to play. These stories show how the ratio can turn equity into everyday joy.
 PPT - Unlock Growth with the SBA 504 Loan Program for Small Businesses
Start by checking your current LTV with a quick online calculator, then compare offers from at least three lenders. Ask about fees and pre‑payment penalties, and consider locking in the rate before a market swing. Setting a clear purpose for the cash will keep the funds on track.
Overall, the cash‑out refinance LTV ratio remains a friendly bridge between home equity and financial goals for individuals, families, and whole neighborhoods. By staying informed and planning wisely, anyone can use this tool to create stability, growth, and a little extra sunshine in everyday life.