If you’ve ever wondered whether you can tap your 401(k) for cash, you’re not alone. Many workers find that a loan from their retirement account is a handy, widely available option. It’s often as simple as applying for a regular mortgage, making it appealing for unexpected expenses.
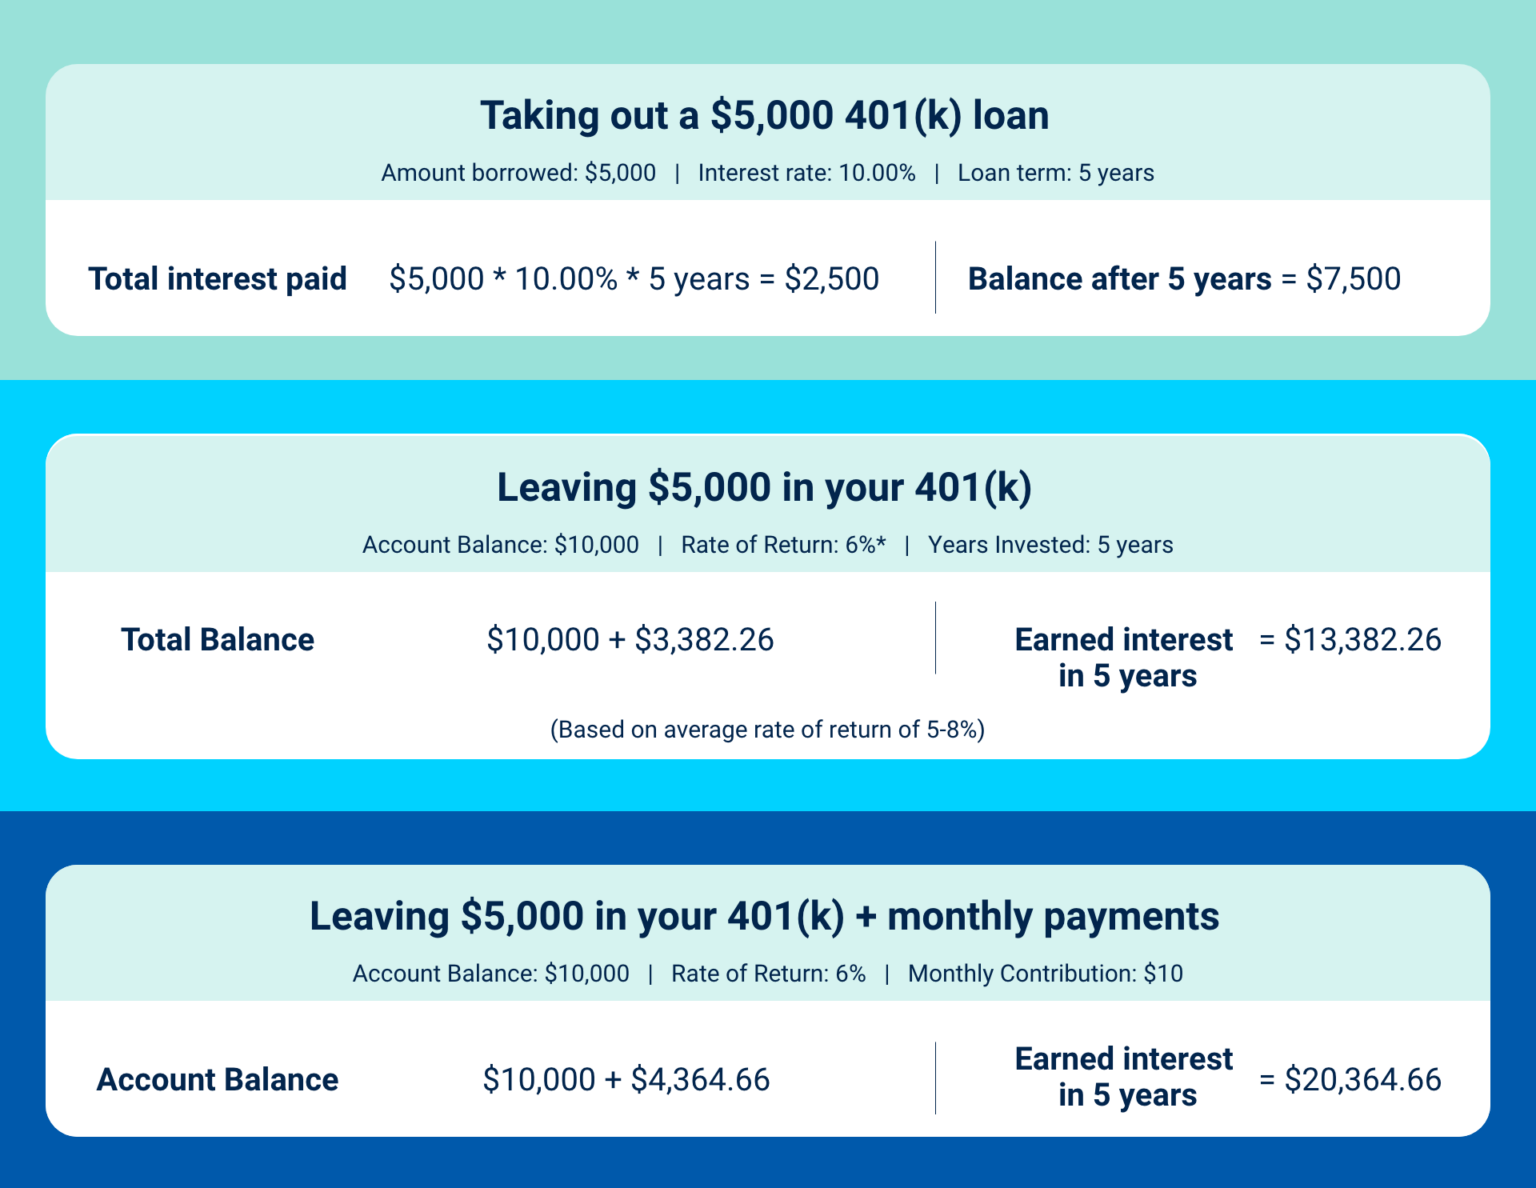
Why does it matter? A 401(k) loan lets you borrow from yourself at a modest rate, then you repay it back into the account. For individuals, that means avoiding high‑interest debt while keeping money in a growth‑oriented investment. Families gain funds for medical bills, tuition, or home repairs, strengthening overall financial stability.
Consider Maria, a nurse who needed $5,000 to fix a broken transmission. Instead of a 22% credit‑card balance, she took a 401(k) loan, repaid it over 12 months, and kept her emergency fund intact. Her story shows how a small, targeted loan can solve urgent problems without wrecking credit.
Must Read
The Patel family used a loan to cover their daughter’s first‑year college tuition. Borrowing $20,000 from the 401(k) let them avoid student‑loan interest while the money stayed invested. Repaying each month kept the plan on track, demonstrating how a family‑level benefit can boost education and future earnings.
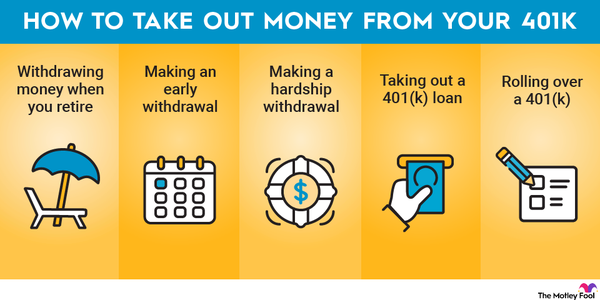 How to Take Money Out of Your 401(k) | The Motley Fool
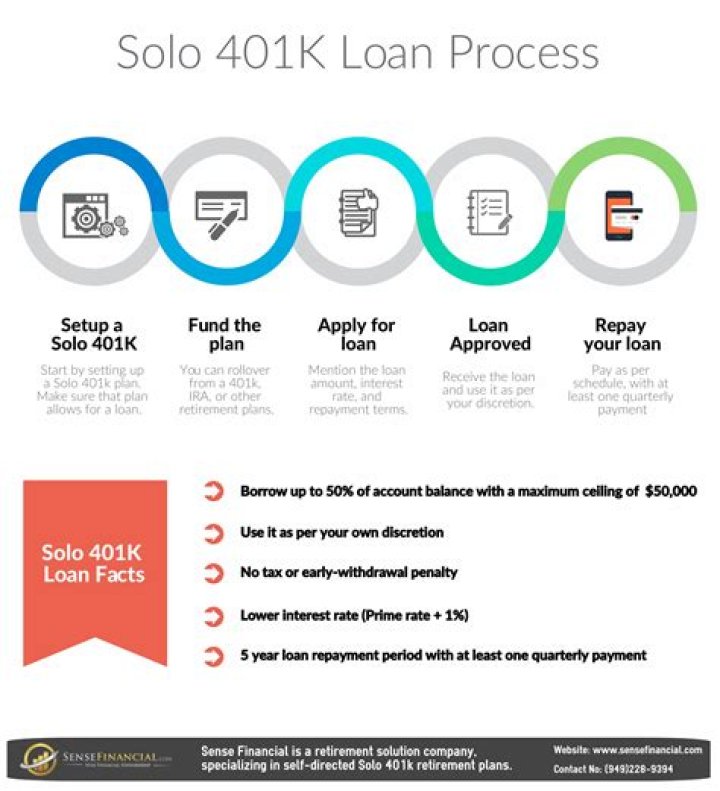
To get started, follow a few practical steps: confirm with your plan administrator that a loan is allowed; calculate how much you need and the maximum you can borrow (usually up to 50% of vested balance); set up automatic repayments to avoid missed deadlines; and keep a written record of the terms.
In short, a 401(k) loan is a flexible, powerful tool that turns retirement assets into immediate cash while preserving the original investment. It benefits individuals, families, and whole communities by providing liquidity for urgent needs and supporting long‑term goals. With careful planning, you can enjoy today’s help and still look forward to a secure tomorrow.