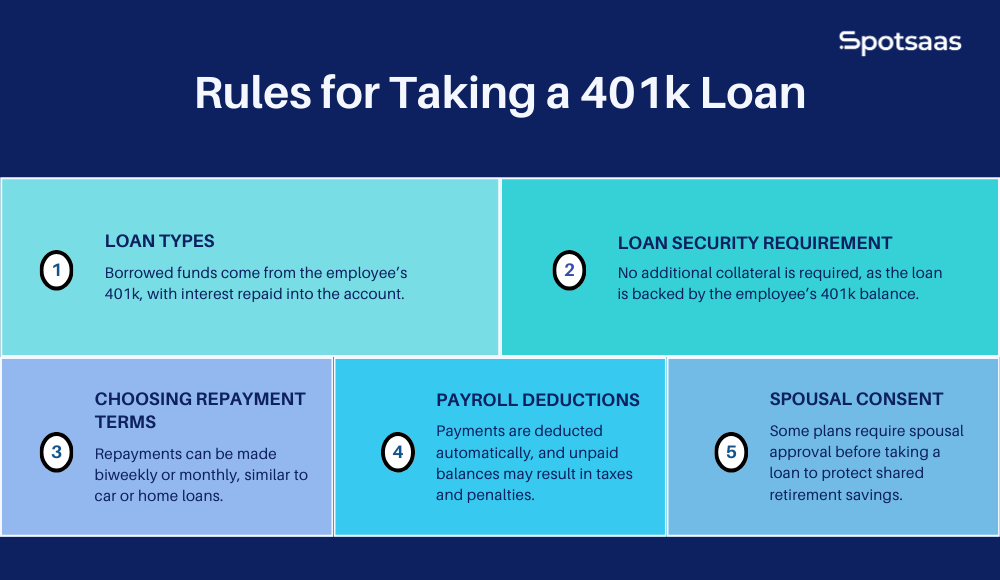
Many people ask, “Can you get a loan against your 401(k)?” It has become a popular choice because it lets employees tap into retirement funds quickly, without a credit check or a lengthy application. Its clear process gives peace of mind.
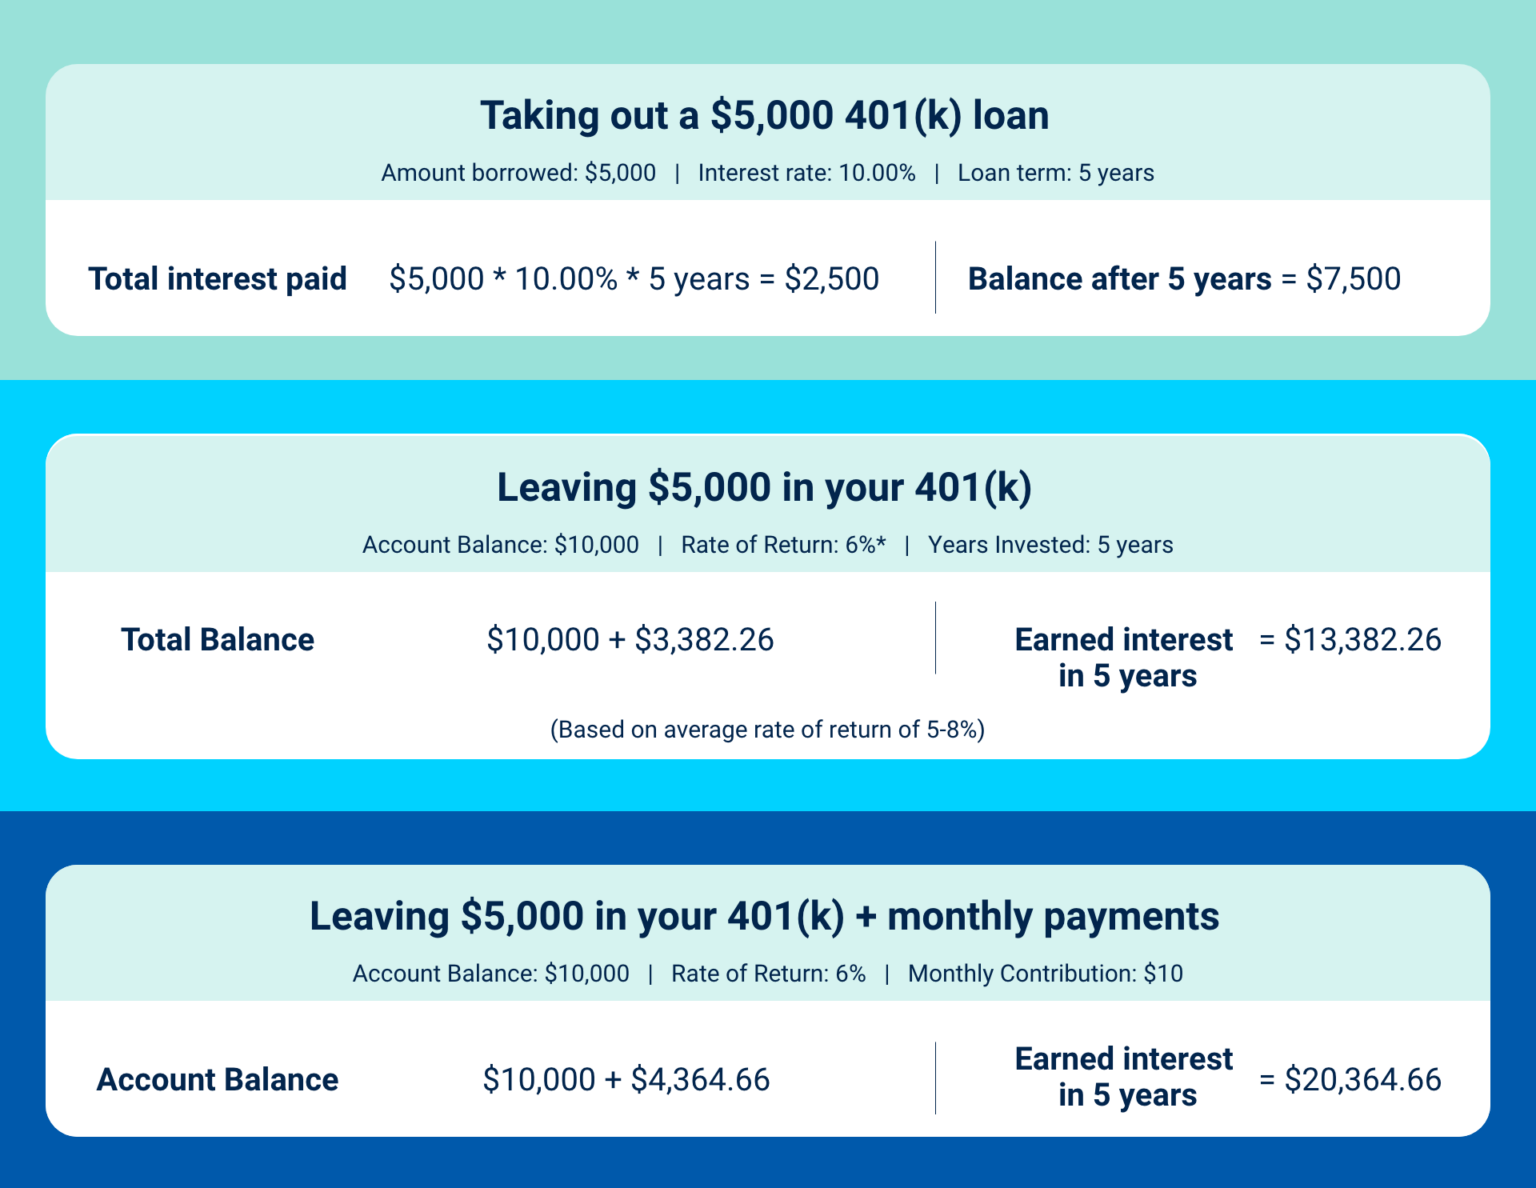
The main benefit is that the interest you pay goes back into your own 401(k), effectively making you your own lender. Because the loan is repaid automatically through payroll, it does not trigger a tax penalty, which keeps your retirement savings growing. The loan stays off your credit report.
Take Sarah, for example. She needed $5,000 for an unexpected roof repair. By borrowing from her 401(k), she fixed the problem immediately and repaid the loan over two years, using only a small portion of each paycheck. Her employer let her adjust repayments.
Must Read
A family can also benefit. When the Martins wanted to cover their daughter’s college tuition, they used a 401(k) loan to bridge the gap without taking on high‑interest student debt, keeping the kids’ education on track while preserving future retirement income. The plan allowed rapid repayment, reducing balance quickly.
 Borrow Against 401k: A Practical Guide to borrow against 401k and
To apply, start by reading your plan’s summary document, then speak with your HR department or the plan administrator. Compare the loan’s interest rate with other options, set a realistic repayment schedule, and make sure the amount you borrow does not jeopardize your long‑term savings. Remember to keep a copy of the loan agreement for your records, and review the schedule each year to stay on target.
In short, a 401(k) loan is a flexible, self‑funded tool that can solve immediate financial needs while keeping retirement on track. With careful planning, it can be a smart, positive move for individuals, families, and communities alike. By treating the loan as a bridge, you can address urgent costs without sacrificing tomorrow’s retirement.