
Okay, so you need cash. Fast. But your bank account is doing that thing where it just stares back at you with nothing.
Then you remember your 401k. That big ol' pile of retirement money sleeping in a vault somewhere.
Here's the wild part. Most 401k plans actually let you borrow against them. Seriously. It's like borrowing from yourself, which feels a little bit like being your own rich uncle.
Must Read
How Does It Actually Work?
It's surprisingly simple. You ask your employer's plan administrator for a loan, and if your plan says yes, you get the money. Well, not all of it. There are limits.
Usually, you can borrow up to 50% of your vested balance or $50,000. Whichever is smaller. Your 401k isn't funding your yacht purchase just yet.
You pay it back through payroll deductions. Set it and forget it, kind of like that gym membership you signed up for in January.
 Borrow Against 401k: A Practical Guide to borrow against 401k and
The Quirky Perks
Here's the fun bit. You're paying yourself back with interest. Not your landlord. Not your credit card company. You. How satisfying is that?
And that interest? It goes straight into your own retirement account. You basically become your own best lender. How cute is that?
Plus, it doesn't show up on your credit report. No credit check needed. It's like a secret financial handshake between you and your future self.
Hold On, Though...
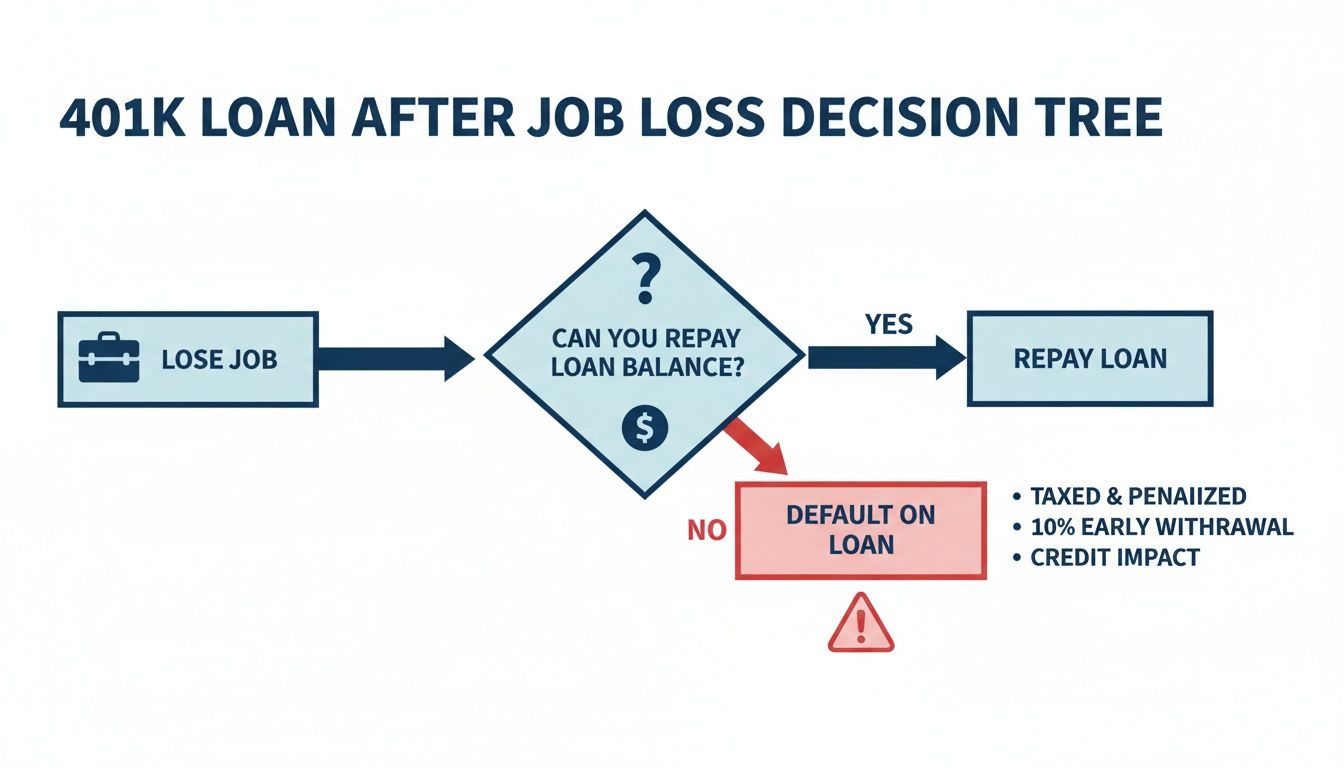
Now, it's not all rainbows and tax-free loan money. If you leave your job with money still owed, the full balance becomes due fast. Like, often by next tax filing day fast.
 401(k) Loans: When to Borrow and Key Rules Explained
Miss a repayment? Ouch. The IRS treats it as a distribution, and suddenly you owe income tax and a penalty. Nobody wants that surprise party.
You also miss out on any investment growth while that money is out. Your retirement account takes a little nap during the loan period. Not ideal, but not catastrophic either.
A Fun Little Quirk Nearly Nobody Knows
Here's something ticklish. Unlike many other things in finance, a 401k loan is legally considered a plan withdrawal reversal. The IRS has specific rules, but the handling is uniquely weird across different plans.
 Borrow Against 401k: A Practical Guide to borrow against 401k and
Some plans are super flexible. Others are stricter than a bouncer at a zero-tolerance club. Check yours before you fantasize about financing that kitchen renovation.
So, Should You Do It?
Borrowing from your 401k can be a genius move for emergencies, debt consolidation, or that moment when your car makes an alarming noise. It's access to money without the typical credit card interest nightmare.
Just don't make it a habit. Treat it like a handy escape hatch, not a regular ATM. Your future self will high-five you for being smart about it.
And hey, at least now you know that your retirement fund might be more than just your retirement fund. It could be your did-I-just-need-2000-dollars emergency buddy, too.