Welcome to the quirky world of tax‑time hacks, where the dread of an IRS bill meets the thrill of a credit‑card swipe! Imagine turning a dreaded payment into a moment of smart financial moves that can earn you points, protect your cash flow, or even spread the burden over a few months. This short guide shows why the idea is not only fun but also surprisingly helpful for anyone looking to smooth out the lifespan of a tax bill.
The core purpose of paying the IRS with a credit card is simple: it lets you delay the full cash outflow while still meeting the official deadline. By routing the payment through an approved processor, you gain flexibility and the chance to earn rewards or travel miles on a category that most cards treat as a purchase rather than a cash advance. The advantage? You keep your bank balance intact for emergencies while still staying compliant.
Think about a freelancer who receives a $5,000 quarterly tax bill. Instead of draining their checking account, they charge the amount to a card that offers 2% cashback, turning a tax expense into a $100‑plus bonus. Or a small business owner can split the payment across two cards to stay under the issuer’s limit, dodging added fees while still using the grace‑period benefit of a credit line.
Must Read
One creative twist is to align the card’s payment cycle with your cash‑flow schedule. Pay the IRS on the first day of a billing cycle, then settle the balance when the statement arrives—giving you a full month to manage the cash before the due date. This trick combines the immediate compliance required by the IRS with the strategic timing that savvy card users love.
 How We Got $4k in Free Travel by Paying Taxes with a Credit Card
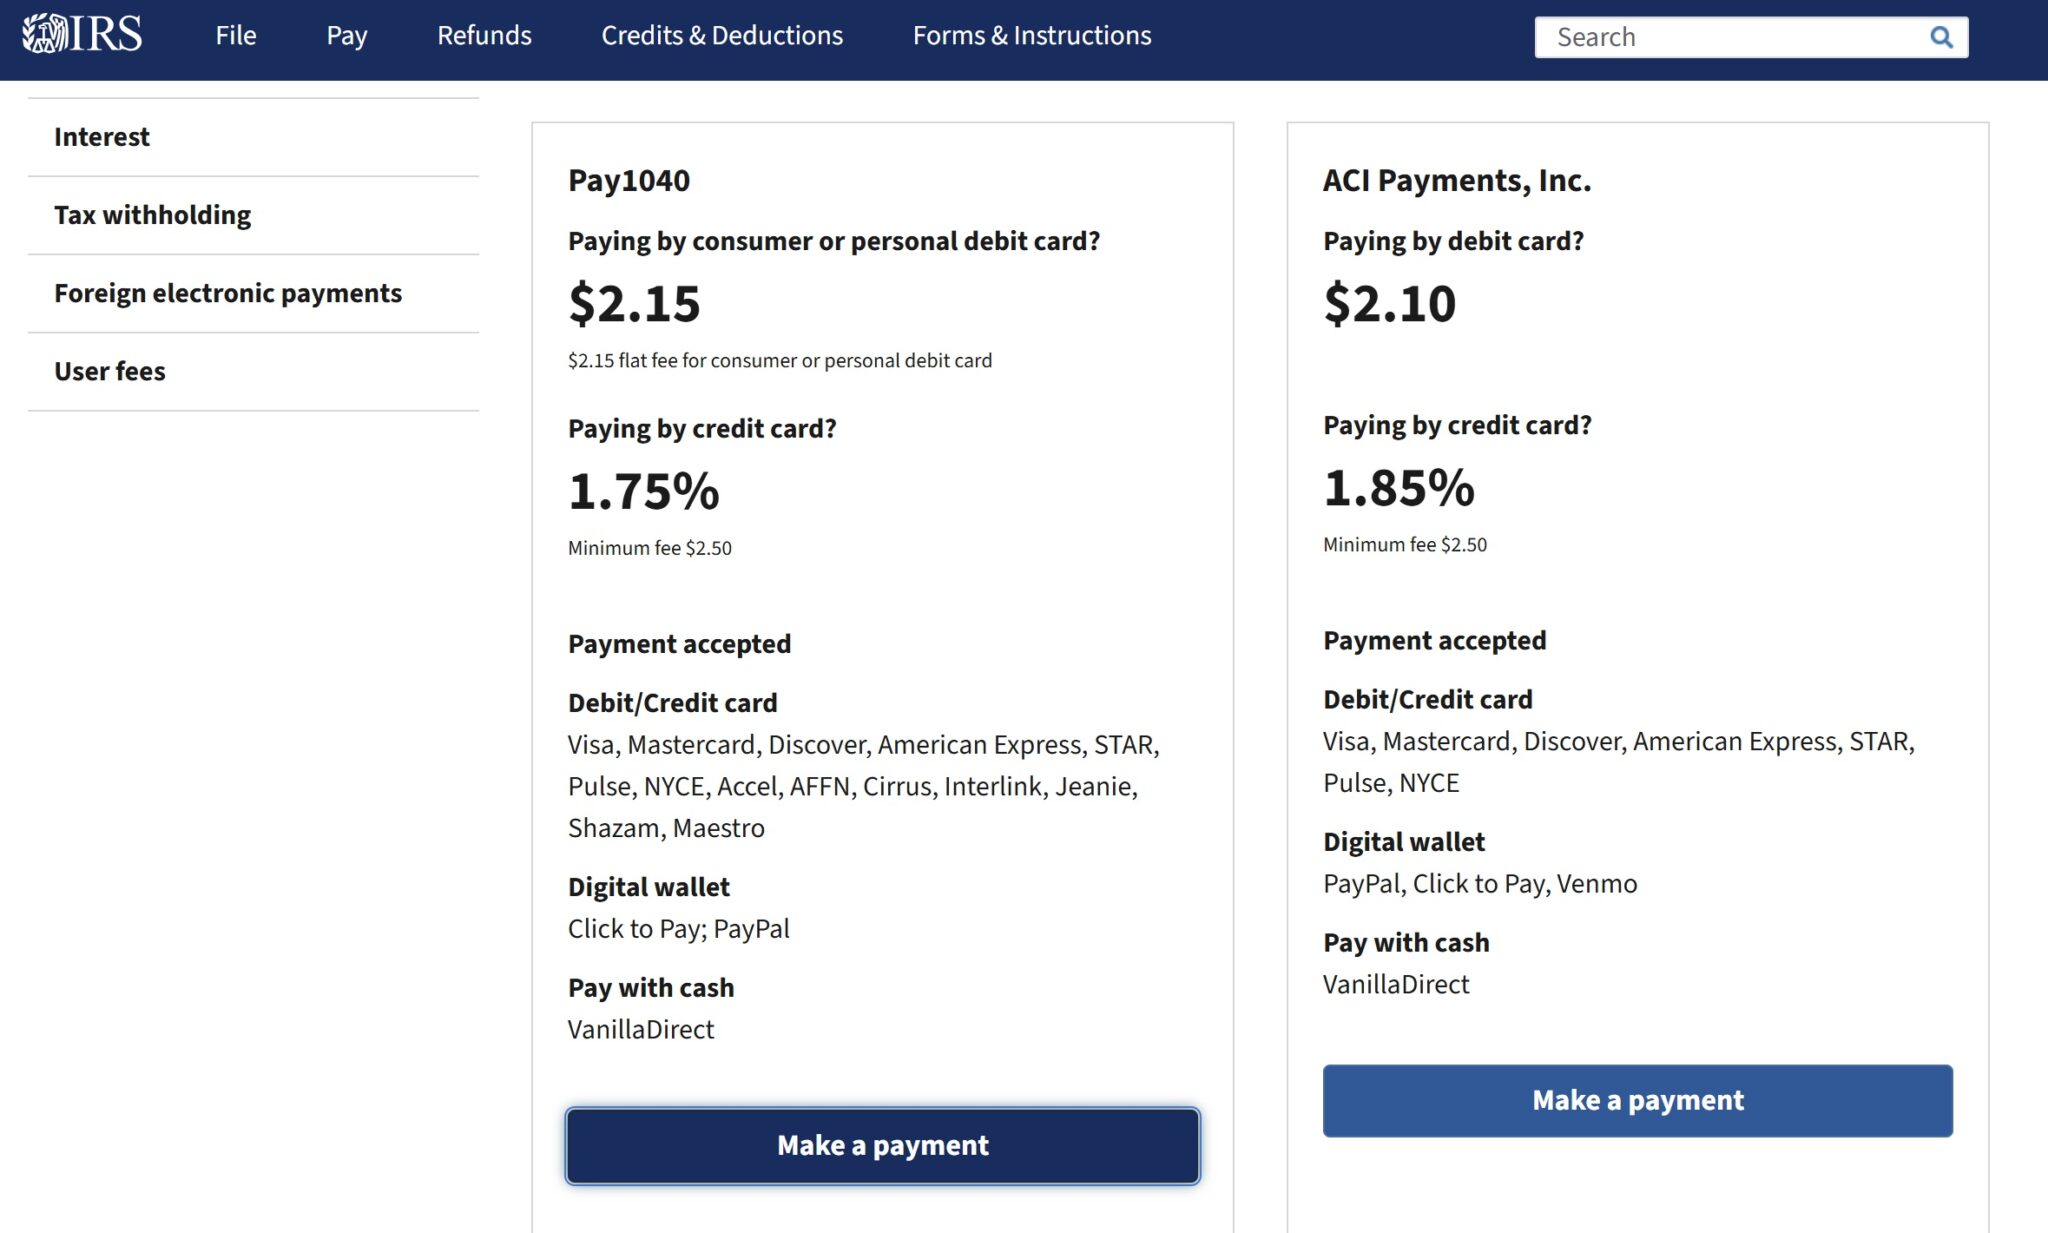
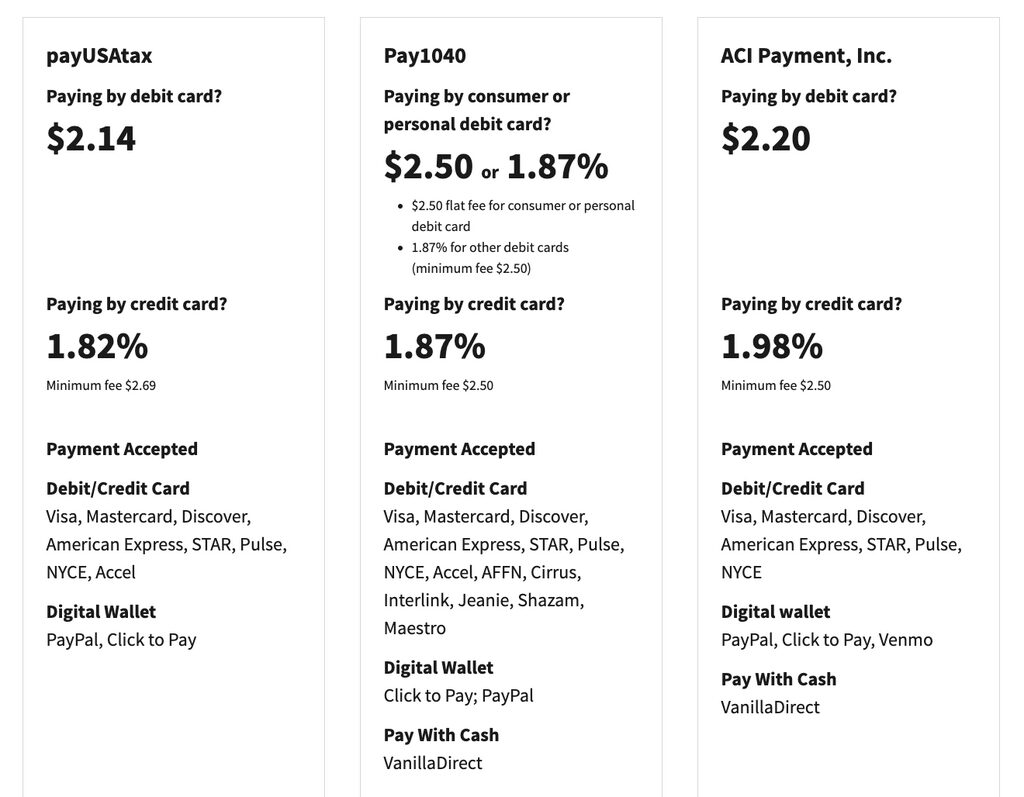
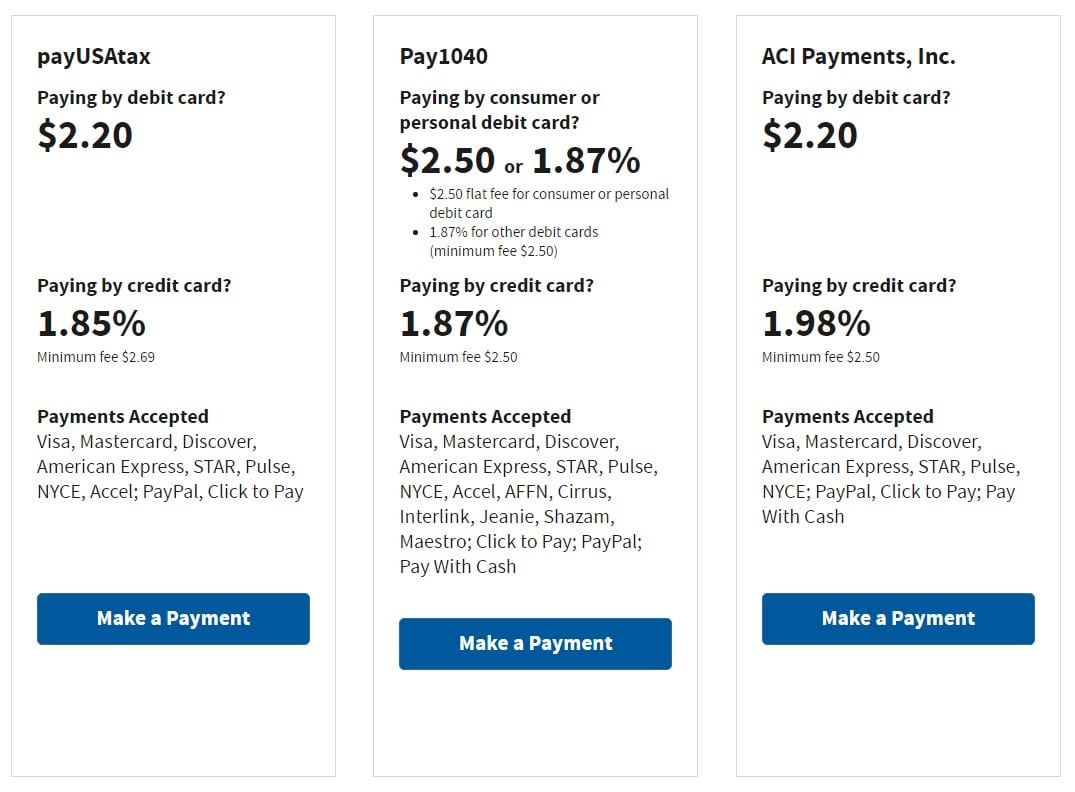
Ready to try it? First, confirm that your chosen card processor is approved by the IRS (usually listed on their “How to Pay” page). Then, check the processing fee—most third‑party services charge 1.87%. Multiply that fee against your payment amount to see if the rewards outweigh the cost. Finally, set a reminder to pay the credit‑card bill on time, so you avoid interest charges that could erase any cash‑back gains.
In short, turning an IRS payment into a credit‑card transaction can be a playful yet profitable strategy. By understanding the fees, timing, and reward structure, you stay on the right side of the taxman while squeezing every drop of value from your plastic. Happy swiping, and may your tax season be as smooth as a well‑earned cashback bonus!