Ever stared at your retirement accounts and thought, "Wait... can I actually stuff money into BOTH an IRA and a Roth IRA?" Spoiler alert: yes, you absolutely can. And honestly? It's one of the most fun money moves you'll ever make.
Think of it like getting dessert AND an appetizer. Why choose one when your financial future could have both? Let's dig into this delicious double-dip scenario.
The Double Dip Is Totally Allowed
The IRS basically says, "Sure, go ahead." You can contribute to a traditional IRA and a Roth IRA in the same tax year. Nobody's stopping you from being financially greedy.
Must Read
Here's the catch though. There's a combined contribution limit across both accounts. For 2024, that limit is $7,000 total (or $8,000 if you're 50 or older).
Yep, that means opting for both shrinks your individual allocatable space. You could do $3,500 in one and $3,500 in the other. Or $7,000 straight into just one. Your call, your split.
Why Would Anyone Do This?
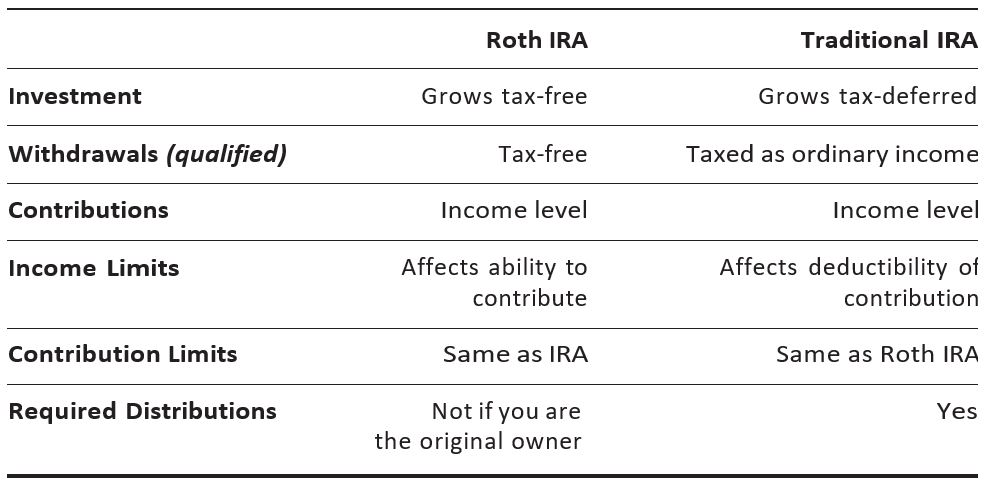
Great question! Splitting contributions gives you tax diversity. A traditional IRA lets you dodge taxes now, while a Roth IRA lets you dodge them later.
 Saving for Retirement: Traditional IRA vs ROTH IRA - 1166 FCU | Credit
It's like planting seeds in two different gardens. You never know which weather pattern will hit, so you hedge your bets. Smart, huh?
Also, Roth ERAs have income limits for direct contributions. Traditional IRAs? Nope, no income cap for contributions at all. So the combination lets more people play the game.
Fun Quirky Facts You'll Love
Here's a spicy one. If your income is too high for a direct Roth contribution, you can do a backdoor Roth contribution. Grow your money tax-free without anyone noticing but you.
Also, a traditional IRA withdrawal before retirement can trigger a 10% early withdrawal penalty. A Roth IRA? You can pull your contributions anytime, no penalty at all. That's basically a free emergency fund disguised as retirement savings.
 Roth 401 Vs. Roth Ira: What’s The Difference? – PDDYE
Oh, and there are no required distributions from a Roth IRA during your lifetime. The money just keeps compounding like a boss.
The Golden Rule to Remember
Both accounts share one massive rule: keep your annual total under $7,000 (or $8,000 with catch-up). Break that limit, and the IRS charges a 6% penalty on the excess. That stings more than a paper cut.
Also, make sure you're contributing within the tax deadline. That's usually April 15th of the following year. Plenty of time to procrastinate, but why not start early?
 Should I Contribute to My Roth IRA or My Traditional IRA?
One more thing. Your employer's 401(k) doesn't eat into your IRA contribution limit at all. Dogs and cats, totally separate budgets for your cash.
So, Should You Do It?
If you've got the budget, absolutely! Doing both is like wearing a belt AND suspenders. Overkill? Maybe. Genius? Also maybe.
It keeps your retirement portfolio flexible, tax-efficient, and surprisingly exciting. Who said managing money couldn't be a little bit thrilling?
So go ahead. Be the person who maxes out both accounts. Future you will high-five present you with every dollar you saved. Now THAT'S a fun financial flex.