Ever wondered if saying goodbye to an old bank account could give your credit score a surprise wink? It’s a quirky topic that blends money habits with the world of credit reports. In this fun and easy‑to‑read guide, we’ll uncover whether closing a checking or savings account can dent your credit, and why it might actually be a smart move for some.
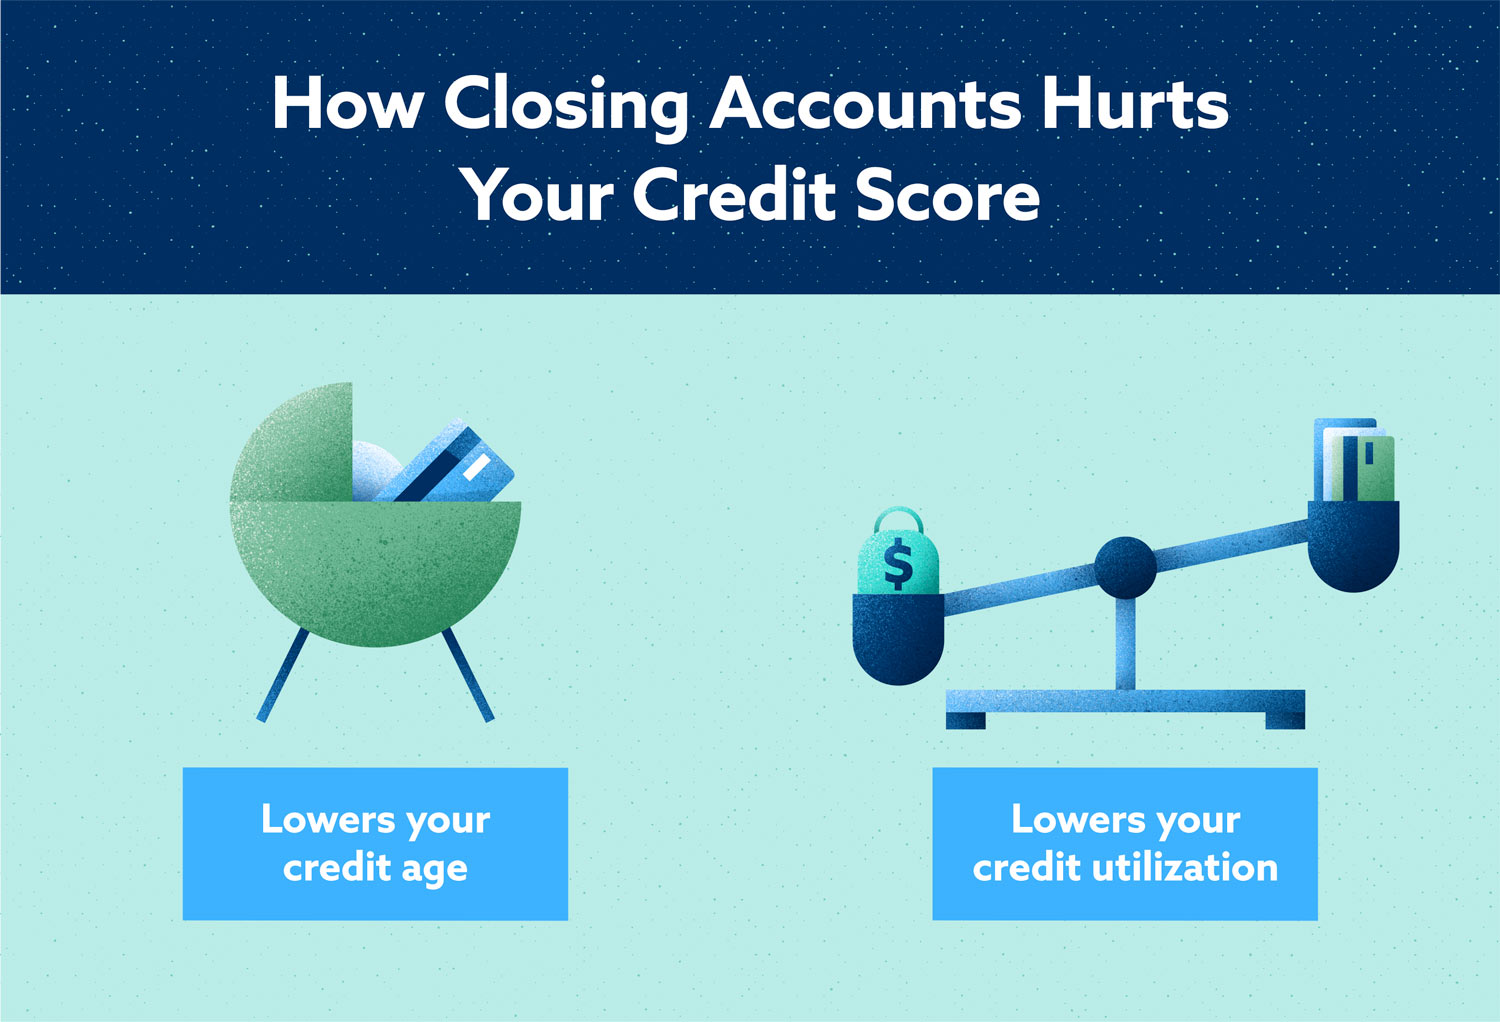
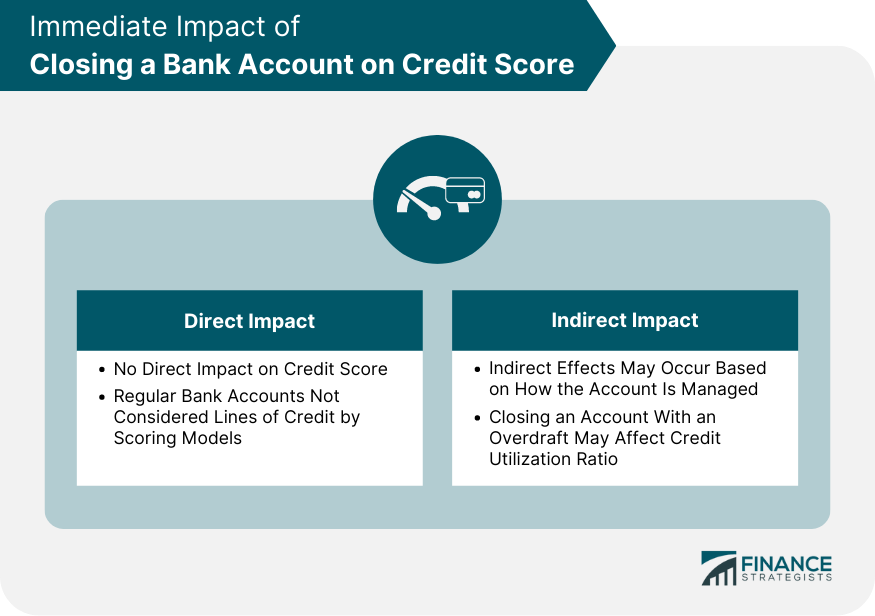
First things first: your credit score comes from credit‑card accounts, loans, and payment history, not checking accounts. Still, banks report account closure to the bureaus if the account was linked to a credit product, possibly affecting your average account age and credit utilization.
Imagine Sarah moving cross‑country and retiring a decades‑old checking account. Even though she never used it for a loan, the closure shortens her account tenure, nudging the score down a few points. But if the account had a negative balance or a prepaid card, the bad data can linger, turning the shutdown into a win.
Must Read
Now picture a creative twist: Jake opens a fresh savings account, auto‑transfers a small amount each pay period, and uses that flow to pay down a credit‑card balance. Closing the old, unused account after the new one works can boost his payment behavior rating without harming the file.
 How Does Closing Bank Account Affect Credit – BPCKP
Ready to give it a try? Pull a free credit report, check which accounts appear, and keep one long‑standing checking account open to preserve credit history length. Set up automatic alerts for balance changes, and monitor your score for 60 days after the closure to spot any surprises.
In the end, closing a bank account isn’t a credit catastrophe—it’s a strategic choice that can tidy your finances while keeping your score steady. Follow these simple steps, stay informed, and you’ll turn a routine bank closure into a confident credit move!