
Imagine a sunny corner where retirees can flip through property brochures, visualizing the kitchen they’ll finally remodel or the garden they’ll plant. This article is a friendly guide to the often‑overlooked question: Can a retired person get a home loan? It’s fun because it opens doors many think are closed, and helpful because it offers clear steps toward financial independence.
Banks love stable incomes, and Social Security checks, pension payments or even steady rental earnings count as reliable income for lenders. When you show a solid credit history and a modest debt‑to‑income ratio, you become a low‑risk applicant—exactly the profile mortgage lenders adore.
Picture Maria, a 68‑year‑old ceramic artist, who secures a $150,000 loan to buy a converted loft. Her pension of $3,200/month plus a part‑time gig at a local gallery proves she can handle the modest monthly payment.
Must Read
Or think of John, a retired vlogger. He uses his YouTube ad revenue and a small savings account as a down‑payment source. Lenders see the ad money as extra cash flow, which sweetens the deal and often secures a lower interest rate.
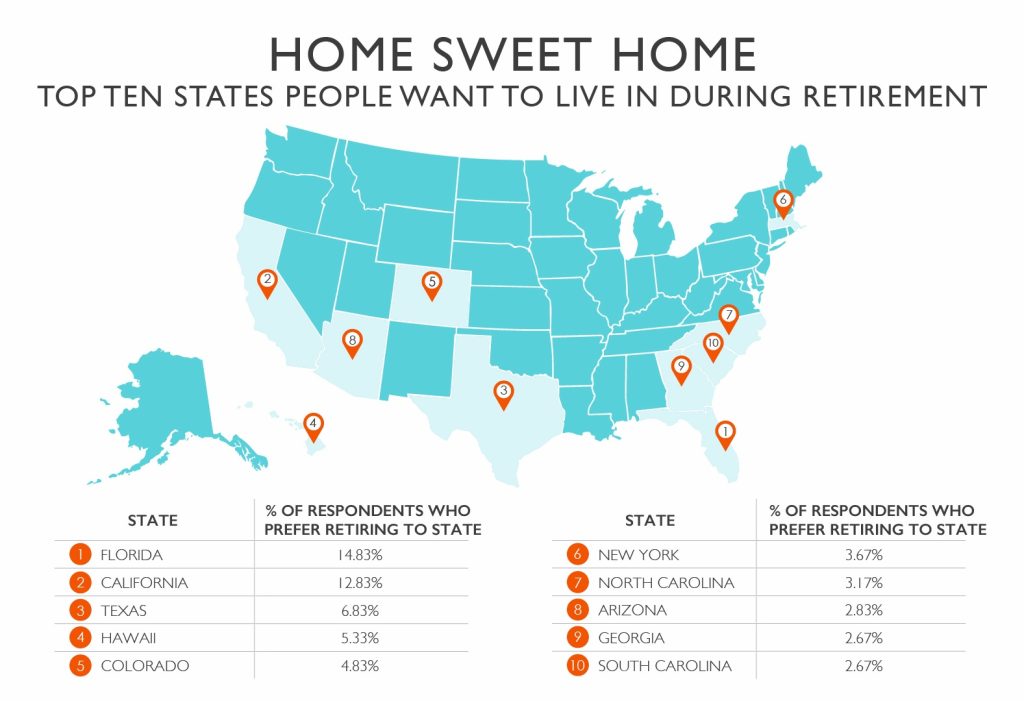 Loans for Retired Seniors: Get Money Today | PayDaySay
To get started, gather proof of income (Social Security statements, pension letters), recent bank statements, and a credit report. Aim for a steady credit score, clear any small debts, and consider a pre‑approval to see what amount fits your budget. Keep an eye on local government grants that can reduce closing costs for seniors.
Finally, don’t be shy to ask lenders about senior‑friendly programs—some banks even waive certain fees for retirees. With the right preparation, a loan can turn golden‑year dreams into brick‑and‑mortar reality, proving that retirement is just a new chapter, not the end of homeownership. Plus, many lenders now offer flexible repayment plans that align with monthly pension cycles.

