
We've all been there—staring at a mountain of credit card statements and wondering how you ended up with cards from six different stores. It feels like your wallet has a secret life you didn't approve of. Luckily, there's a trick called combining credit card debt that can make things a whole lot easier.
What Does "Combining" Actually Mean?
Think of it like cleaning your closet. You've got shirts hanging everywhere, some crumpled on the floor, and a few stuffed in a shoebox. Combining your debt means taking all those scattered balances and rolling them into one tidy package, usually through something called a balance transfer or a debt consolidation loan.
A Real-Life Example, Aunt Carol Style
My Aunt Carol once told me she was paying interest on five different cards while barely making dent on any of them. She finally moved everything onto one card with a zero-percent intro APR for 18 months. Within a year? She paid off the whole pile—without stress-eating at midnight.
Must Read
The Balance Transfer Route
This is the crowd favorite. You grab a new card that offers a low or zero introductory interest rate, and you transfer your existing balances over. It's like reserving a front-row seat at a concert instead of juggling multiple standing-tickets.
Just watch out for the transfer fee—usually around 3 to 5 percent. A five-percent fee on $10,000 costs $500, so do a little math before you jump. Still, it beats paying 20% APR every month forever.
 Self Debt Consolidation: Debt Consolidation Using Credit Cards
The Debt Consolidation Loan Approach
Another popular route is getting a personal loan specifically to pay off your cards. You end up with one fixed monthly payment, a set interest rate, and a clear payoff date. Think of it as replacing five noisy roommates with one calm, predictable one.
The beauty here is that the rate is usually fixed, so your payment never changes mid-year. No surprises, no juggling—just steady progress toward being debt-free.
What About Home Equity?
If you own a home, borrowing against your equity is another option. The interest rates tend to be low, which feels wonderful when you're used to credit card APRs sky-high enough to power a weather balloon. Just remember: your house is now involved, so treat that loan with extra care.
 What Is The Best Way To Combine Credit Card Debts? - Asian Family
How Do You Pick the Best Way?
Start by asking yourself three simple questions. How much do I owe? What's my credit score? And how much can I realistically pay each month?
If your credit is solid, a balance transfer card is often the quickest win. If you need structure and a timeline, a consolidation loan might feel more comforting—like a GPS telling you exactly when you'll arrive.
Why Should You Care?
Every month you're paying high interest, you're basically working overtime just to keep the lights on. Combining your debt lets you redirect that money toward actually getting ahead. It's not just about saving dollars—it's about reclaiming your peace of mind.
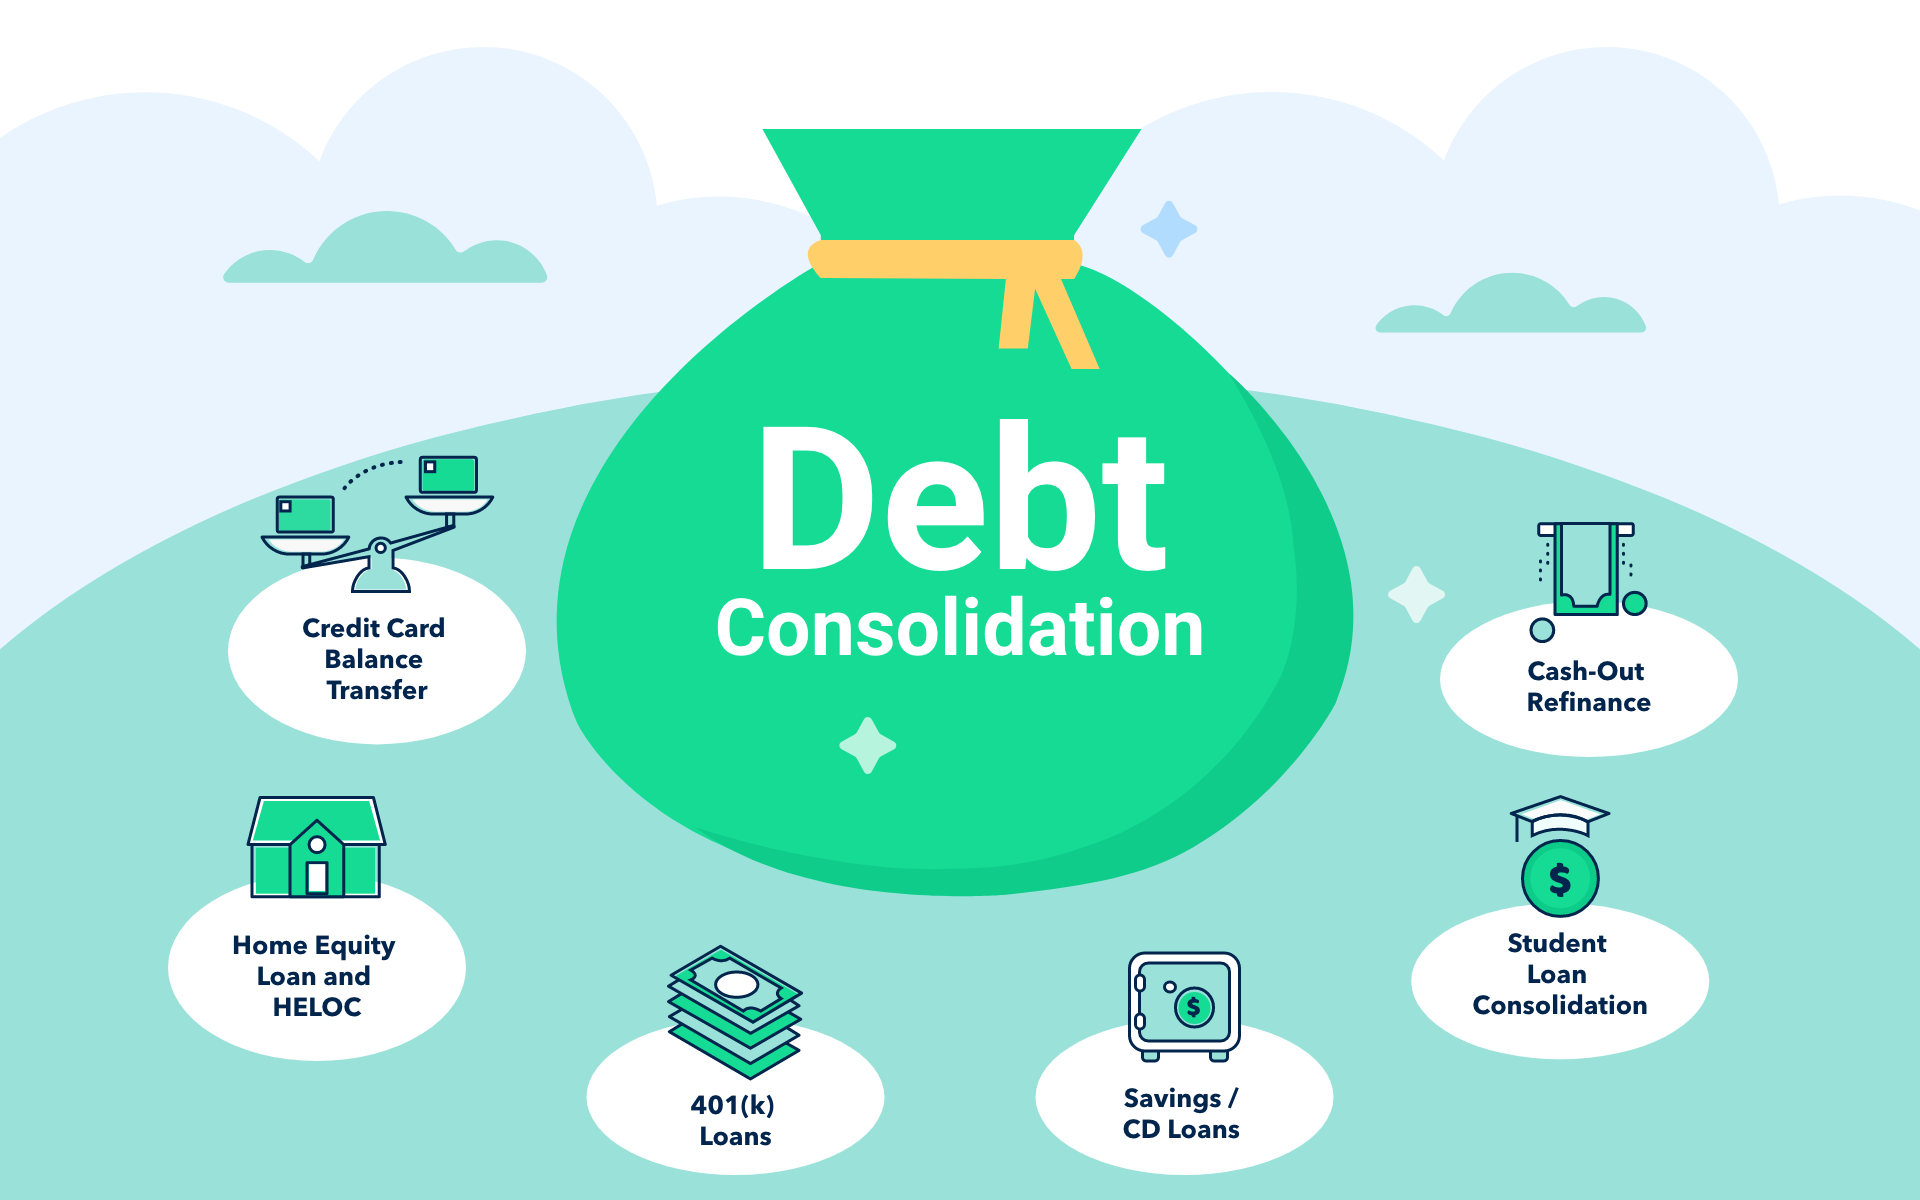 What is Debt Consolidation & How to Do It | Credello
Imagine checking your bank account without that tiny stomach clench. That feeling alone is worth every smart move you make today.
A Little Humor Goes a Long Way
Dealing with debt feels heavy, but it doesn't have to feel impossible. Think of combining your cards as giving your finances a fresh haircut—it doesn't fix everything, but you'll walk out feeling lighter. And sometimes, that shift in perspective is exactly what you need.
So go ahead, take a look at what you owe today. You might be surprised how quickly one simple strategy can bring the whole picture into focus. Your future self is already smiling.