Thinking about credit scores can feel like a mystery, but when you’re twenty, the numbers become surprisingly personal and useful. The average credit score for a 20‑year‑old gives a snapshot of how well young adults are navigating the world of borrowing, and it’s a topic that resonates with students, new workers, and anyone just starting to build a financial future.
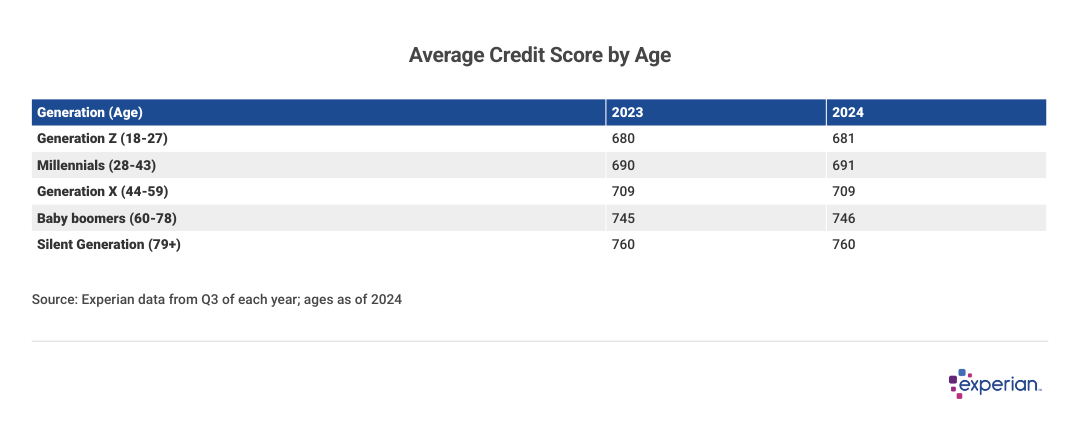
In the United States, most 20‑year‑olds fall somewhere between a 680 and 700 on the FICO scale, which translates to a good rather than excellent rating. This range typically reflects a mix of limited history, a few open accounts, and on‑time payments, showing that the foundation for a stronger score is already being laid.
The benefit of knowing this benchmark is twofold: it helps lenders assess risk more fairly, and it empowers young people to set realistic goals. For a college student, understanding that a score of 700 can unlock a better interest rate on a car loan encourages timely bill payments. For a fresh graduate, seeing a 680 as a starting point motivates strategies to push the number higher.
Must Read
Common variations you might notice include the “grad with a thin file” who scores in the low 600s because only one secured card is on record, while a “future‑go‑getter” who added a utility account may already sit at 710. These differences illustrate how small actions—like using a shared phone plan on time—can shift the average.
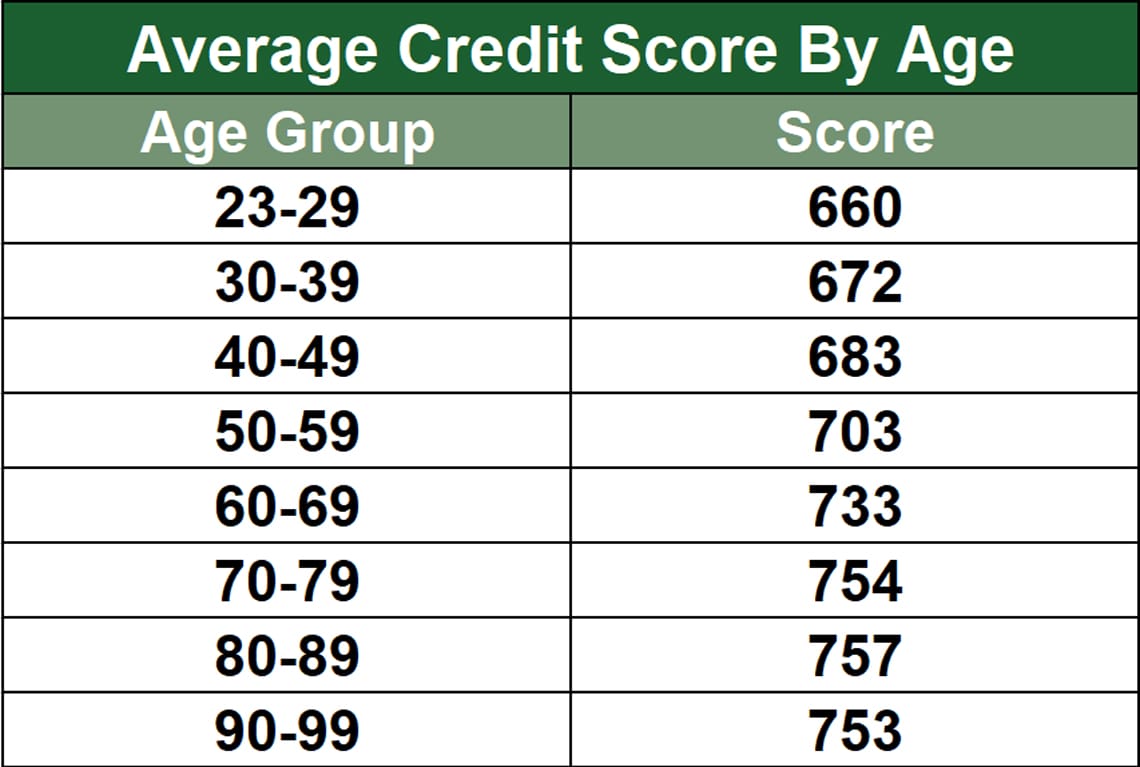 Credit Score Charts: Data & Trends - BadCredit.org
To move the needle, start by pulling a free credit report from each bureau, then follow these simple steps: pay every bill on time, keep credit utilization under 30 %, and consider a secured card if you’re thin on history. Reviewing your report quarterly lets you catch errors early and track progress as your score climbs.
By keeping these habits steady, most 20‑year‑olds can expect their average credit score to rise toward the mid‑700s within a few years, opening doors to better loans, lower insurance premiums, and a smoother path to financial independence.