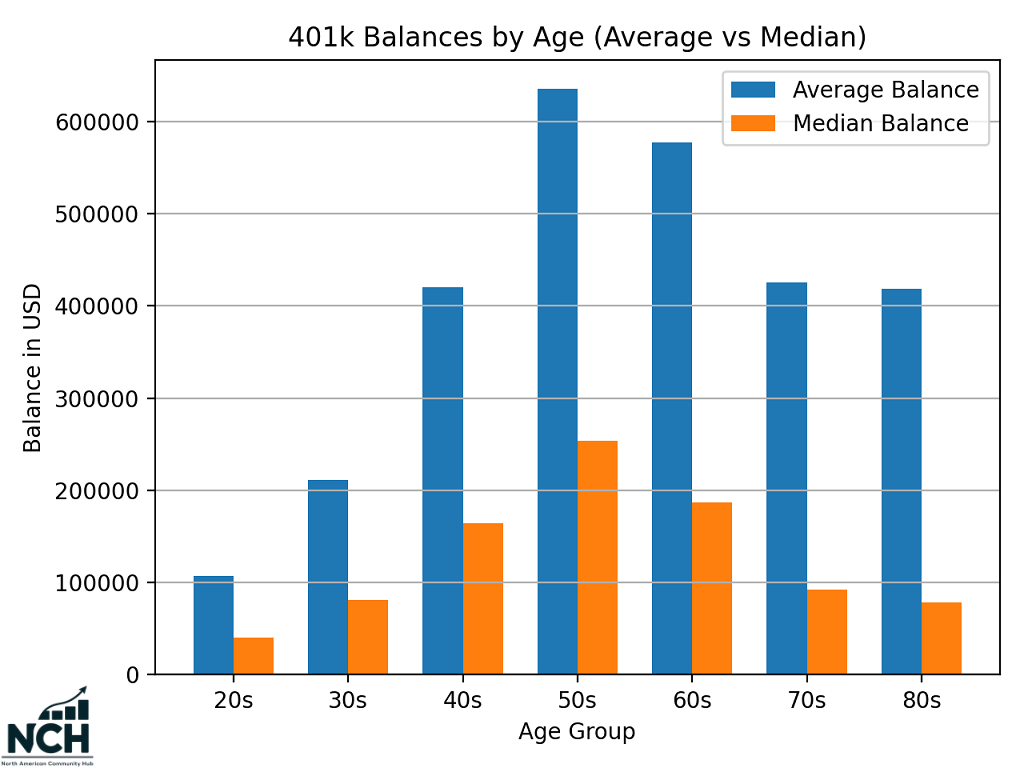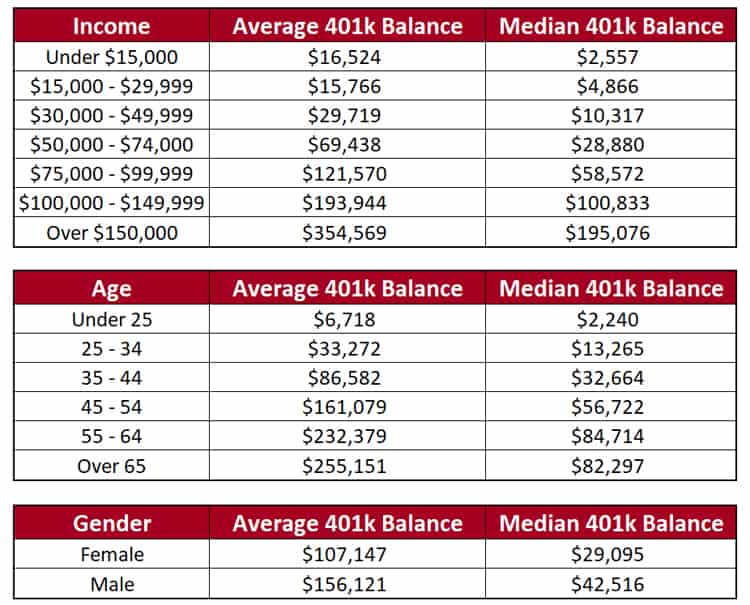
The average and median 401k balance by age is one of the most followed retirement stats out there — and for good reason. People love comparing themselves to where others stand because it gives them a snapshot of how they're doing financially. Whether you're 25 and just starting or 55 and winding down, these numbers are everywhere in retirement planning conversations.
Why does it matter so much? Understanding where you fall helps you set realistic goals. Knowing the average tells you what most people have, while the median gives a more honest picture by filtering out extreme values. Families use these benchmarks to decide how much to save, and communities benefit from more people taking retirement seriously.
For example, a 30-year-old might notice their 401k is below the median and decide to increase their contribution rate from 5% to 8%. A couple in their 40s might compare their combined balance to the median to see if they're on track. Even young professionals starting fresh use these numbers as motivation to begin saving early.
Must Read
Here's how you can use it practically: check your balance against your age group's median first — not the average, since it can be inflated by outliers. Set a target to stay above that median. If you're falling behind, explore employer matches, catch-up contributions, or automatic increases. Small steps add up fast.
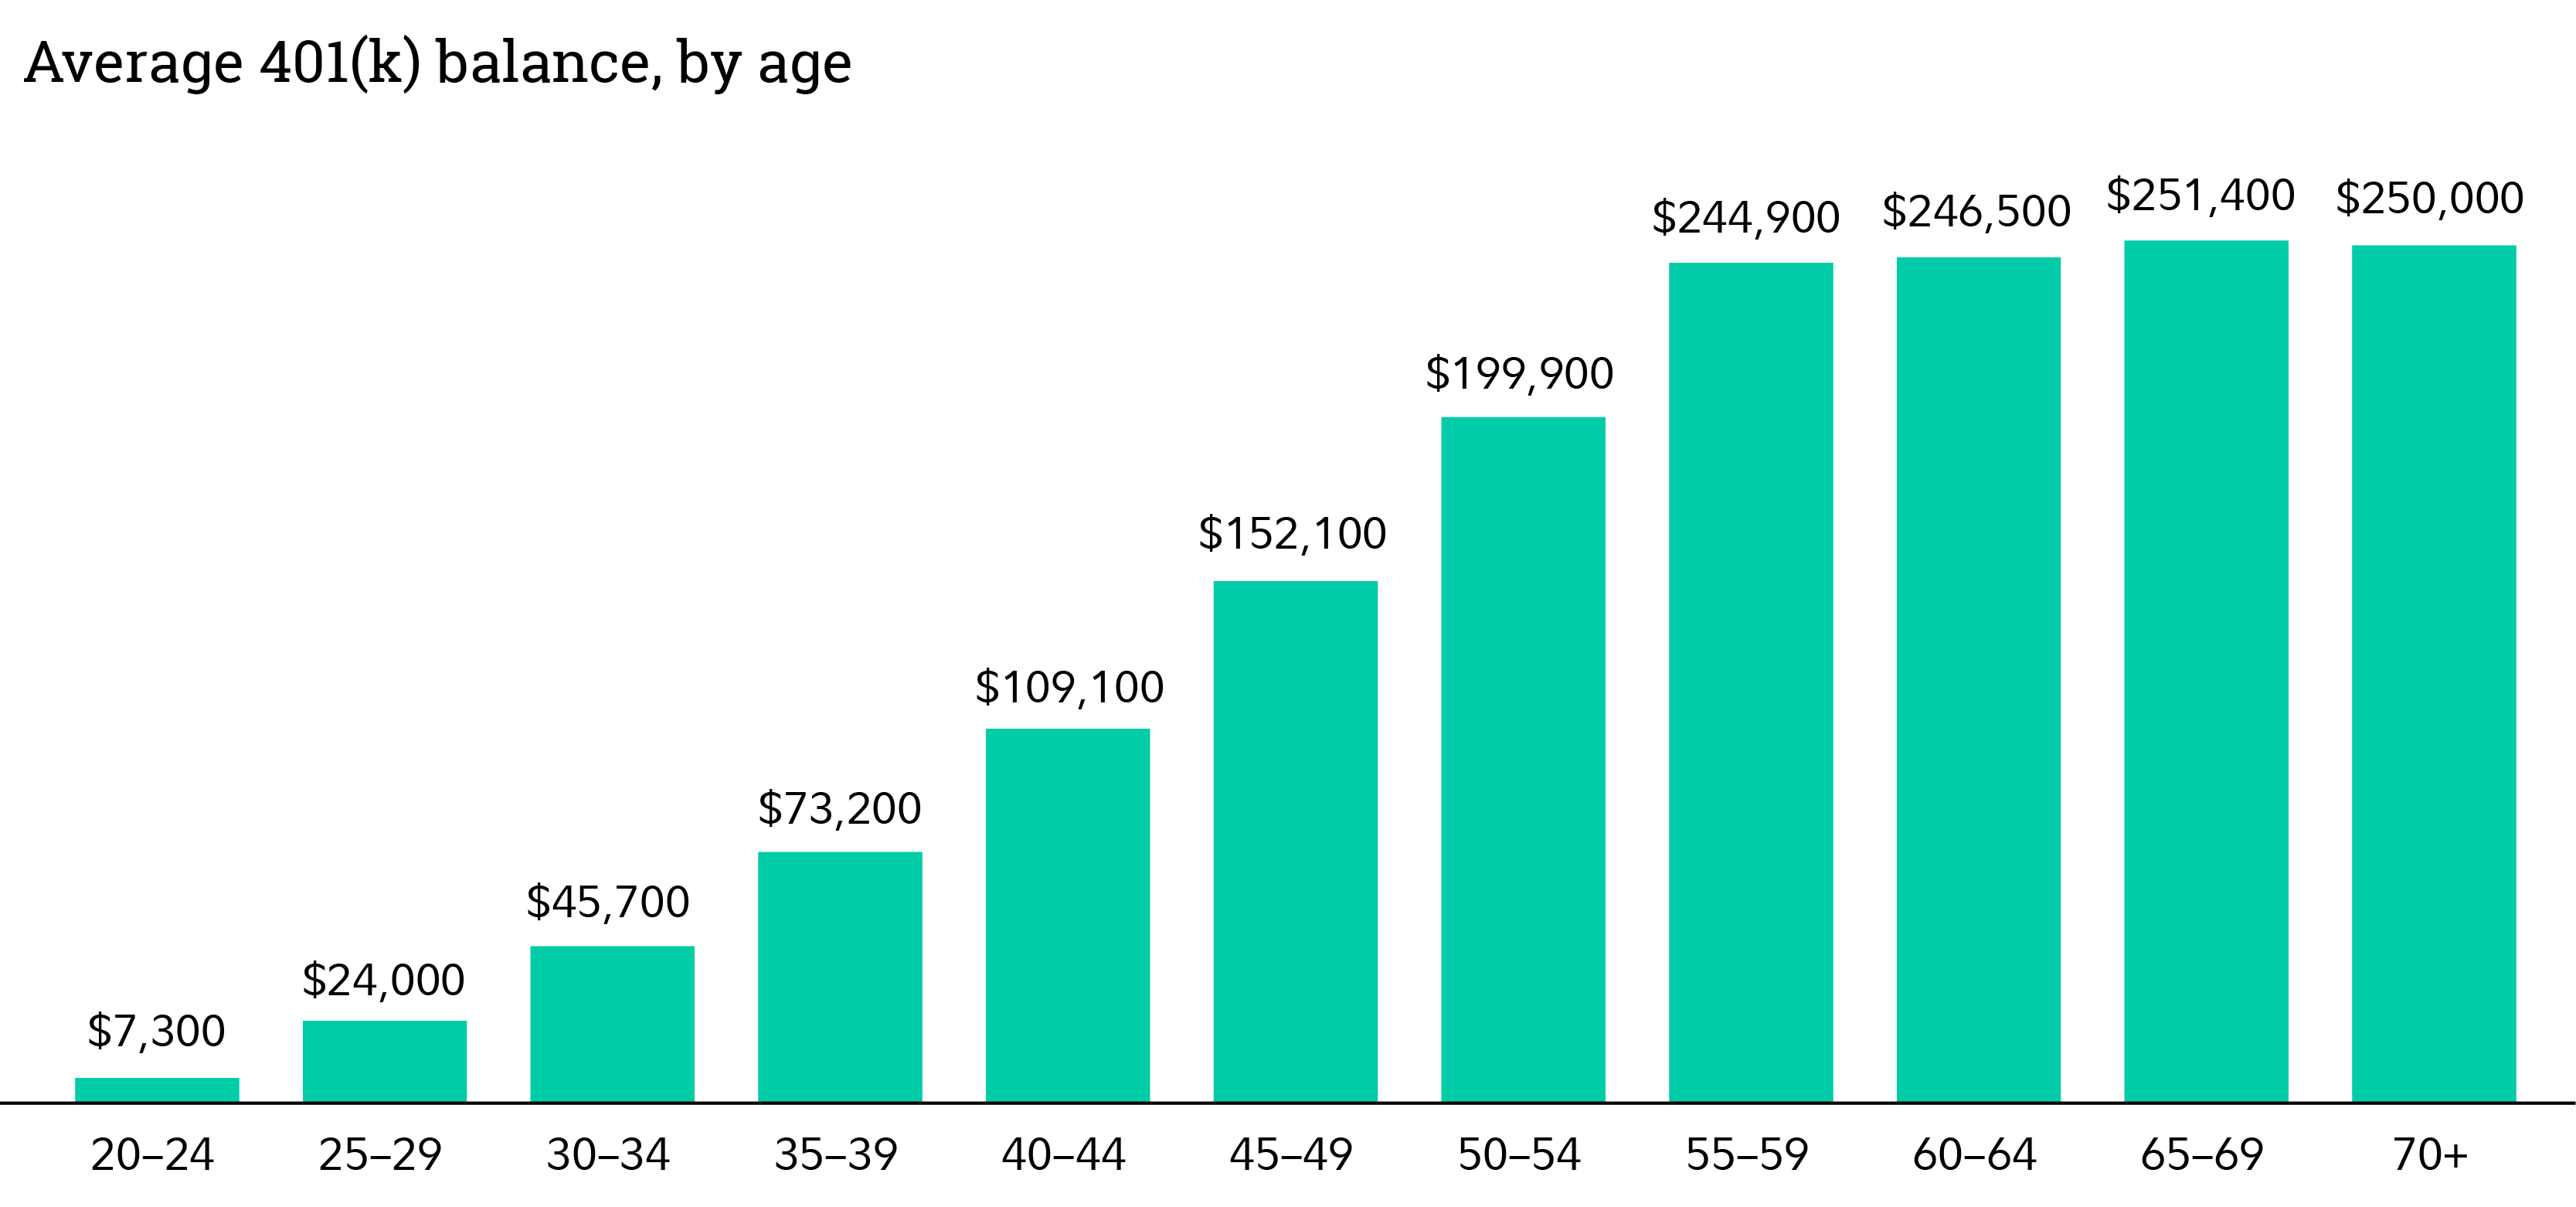 Are You on Track? Assessing Your Retirement Savings and Strategies to
On average, balances vary widely — younger workers naturally have less due to compounding time, while those in their 50s often peak before withdrawals begin. It's not a perfect science, but it's a solid starting point for anyone who wants to take their retirement seriously.
Bottom line? Knowing these numbers puts you in the driver's seat. They're not meant to shame anyone — they're there to inspire action. Keep saving, stay consistent, and let your 401k grow toward a comfortable retirement. You've got this.