If you’ve ever wondered whether your cat’s car—yes, a vehicle you let your feline ride in—can mess with your insurance rates, you’re not alone. It’s a surprisingly hot topic among pet owners who drive with their furry co-pilots. The short answer? Yes, it can, but it’s usually about behavior, not whiskers.
Here’s why it matters: a cat in the car can cause major distractions. A sudden meow, a leap onto your lap, or a paw on the steering wheel increases crash risk. Insurers see this as a claim risk, even if you’re the world’s most careful driver. For families, this means lower premiums if you prove you secure your pet, or higher ones if you don’t.
Imagine you’re driving Fluffy to the vet, and she darts under the brake pedal. You swerve, hit a mailbox, and file a claim. Your insurer might label it an “at-fault accident,” raising your rate. Conversely, using a pet seatbelt or a carrier shows you’re responsible—and some companies even offer discounts for that.
Must Read
For communities, this trickles down to safer roads. Fewer distracted pet-related crashes mean lower costs for everyone through shared risk pools. It’s a small win that adds up.
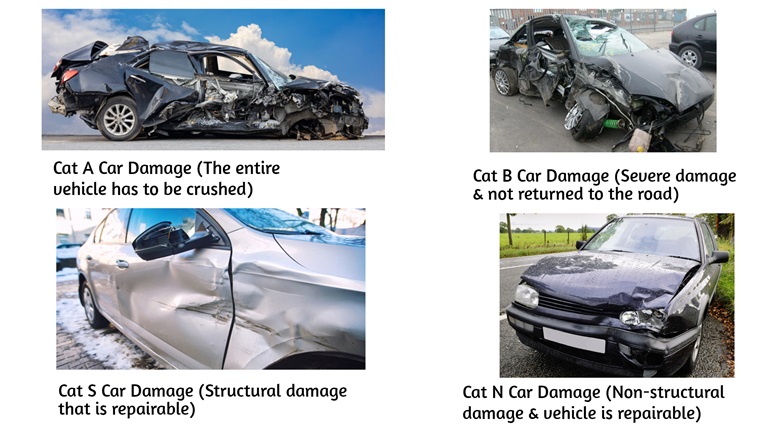
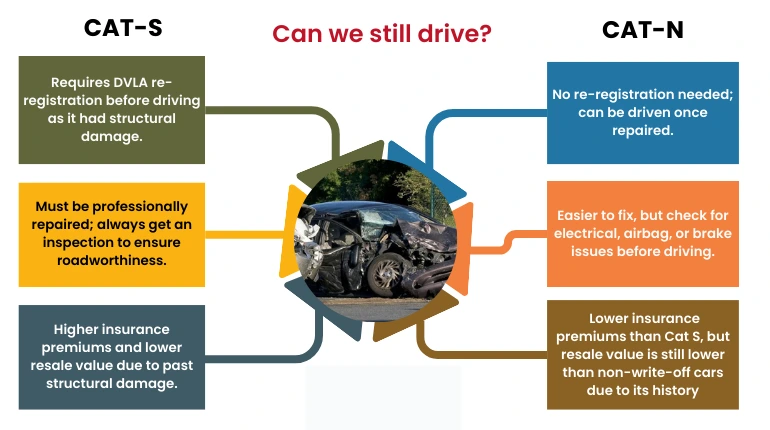 What are Cat S and Cat N write-off cars?
Want to protect your wallet? Always secure your cat in a crash-tested carrier or harness. Tell your insurer you do this—some, like Progressive or State Farm, don’t ask, but a quick call can clarify. Ask about pet-specific coverages to avoid surprises.
The bottom line? A cat in your car can affect your insurance, but it’s a factor you control. With a little prep, you keep your furry friend safe and your premiums steady. Drive smart, pet safe—it’s that simple.