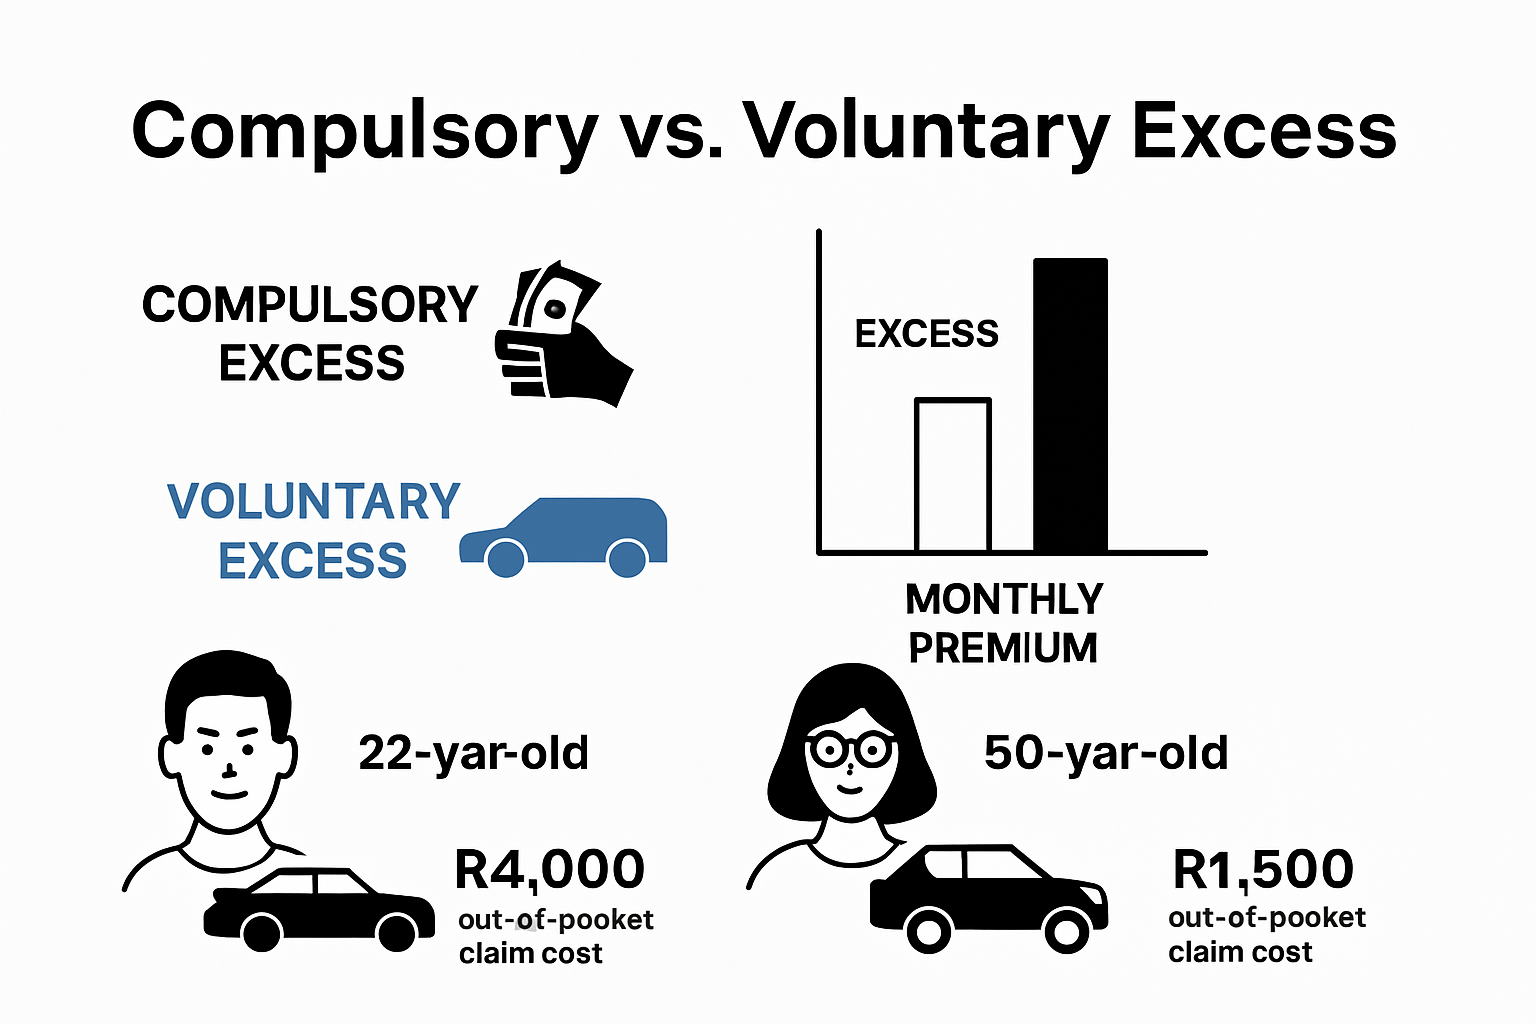
Let’s be honest: insurance isn’t exactly the most thrilling topic at a dinner party. But compulsory excess insurance is one of those practical gems that, once you understand it, makes you feel a little bit smarter about money. It’s widely appreciated because it takes the mystery out of what you’ll actually pay when you make a claim. No one likes surprise bills, and this is the policy part that sets clear expectations from the start.
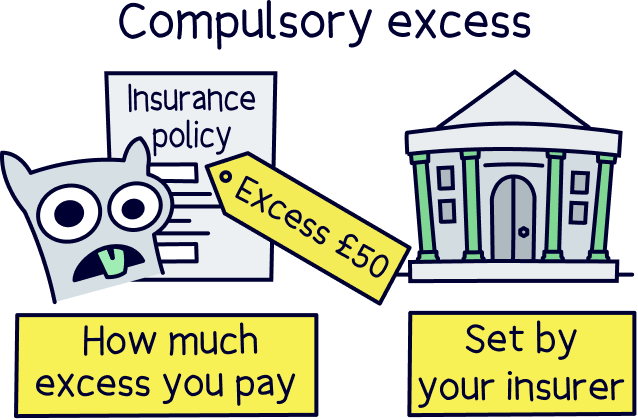
So, what’s its main purpose? Quite simply, it’s the fixed amount you agree to pay toward any claim before your insurer covers the rest. Think of it as your share of the risk. For example, if your compulsory excess is $500 and you have a $3,000 claim, you pay the first $500 and your insurer handles the remaining $2,500. This system actually lowers your premium because it shows you’re willing to take on some of the smaller costs yourself.
Different people benefit in different ways. A new driver opting for a higher compulsory excess can slash their monthly car insurance bill significantly. Meanwhile, a homeowner might choose a lower excess to avoid a big out-of-pocket surprise after a storm. Even renters benefit—common variations like “$100 compulsory excess” on contents insurance keep things affordable for everyday items like a laptop or bike.
Must Read
You’ll recognize compulsory excess in action when you see terms like “$200 excess for accident damage” on a car policy or “standard excess of $250” for home insurance. Some policies even have separate excesses for different events—like a higher amount for fire versus theft. Reading those small print details turns you from a casual policyholder into an informed shopper.
 What is Excess in Insurance? Understanding Its Role
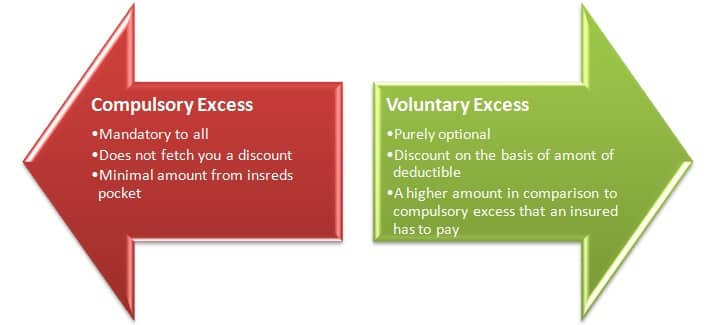
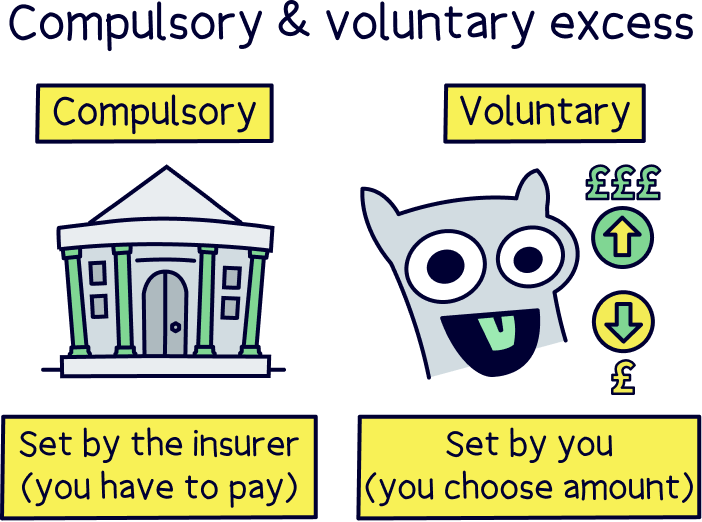
Here’s a simple tip to make the most of it: match your excess to your savings. If you keep $1,000 in an emergency fund, setting a compulsory excess of $500 or $1,000 is perfectly safe. But if you’re living paycheck to paycheck, a lower excess might be better—even if it means a slightly higher premium. Also, always check if your policy has a voluntary excess option, which you can add on top of the compulsory one—sometimes raising that can bring your monthly cost down even further.
Getting started is easy: compare at least three policies online. Look only at the compulsory excess amounts listed, not just the monthly price. A $30 premium with a $2,000 excess could be far more stressful than a $45 premium with a $200 excess. And remember, the compulsory excess is non-negotiable per claim—so choose wisely, and you’ll sleep better knowing exactly what your share will be.