So, picture this: you’ve just backed your car into a lamppost (we’ve all been there, right? The lamppost definitely deserved it). You’re fine, the car is… not fine. You call your insurer, and they start chatting about excess. Suddenly, you’re in a whirlwind of jargon. Let’s fix that, shall we? Grab a cuppa.
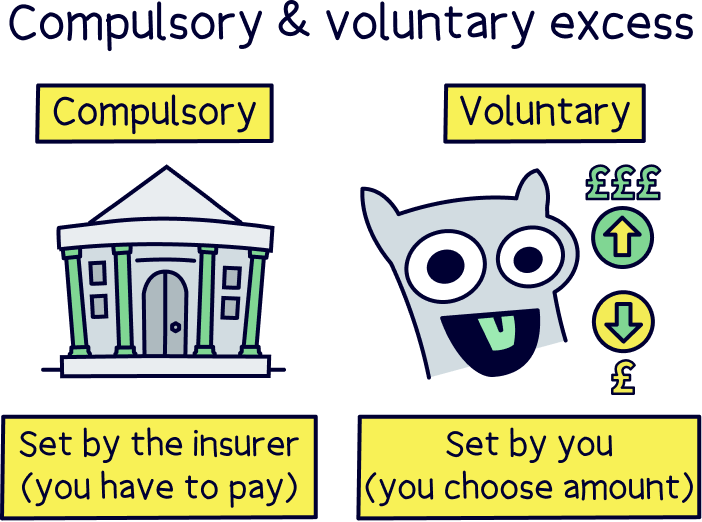
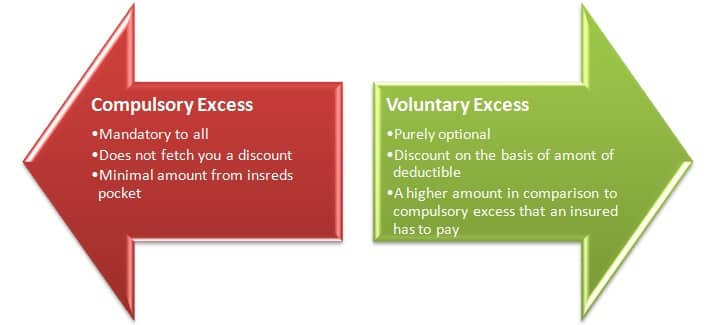
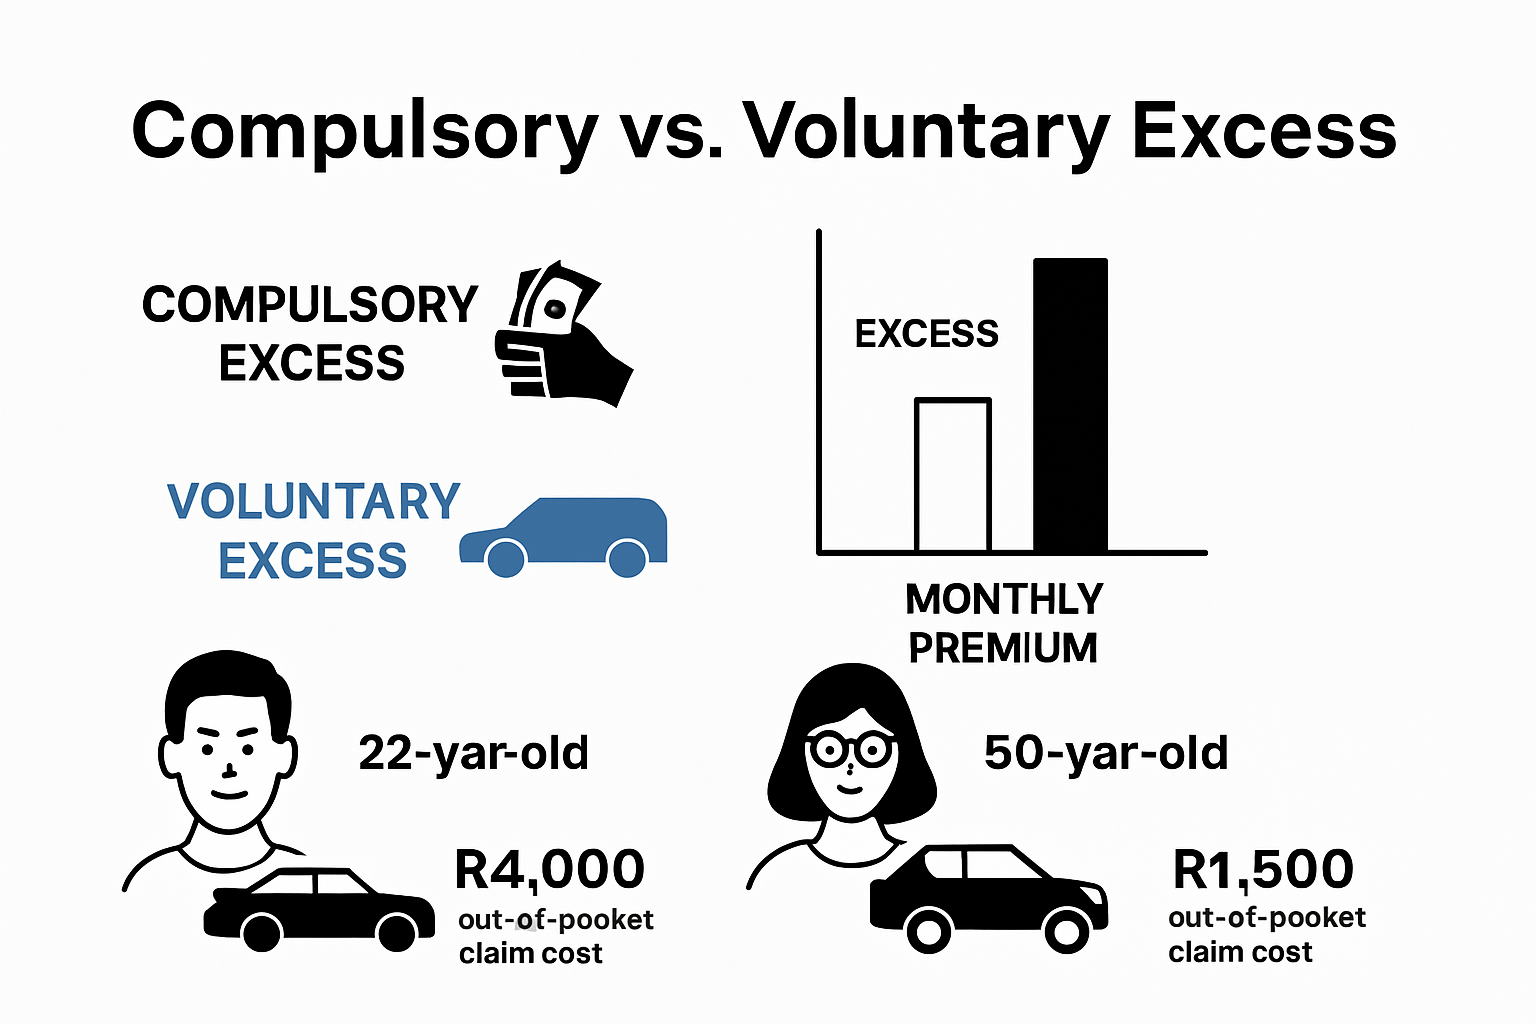
Think of compulsory excess as the non-negotiable part of your insurance party. It’s the amount your insurer always asks you to pay before they chip in. This fee is calculated based on your policy and risk factors—like your age or driving history. You can’t haggle it down. It’s set in stone. Imagine it as the cover charge to get into the club; you’re paying it no matter what (even if the DJ is terrible). The higher your risk to the insurer, the higher this number tends to be. Fun, right?
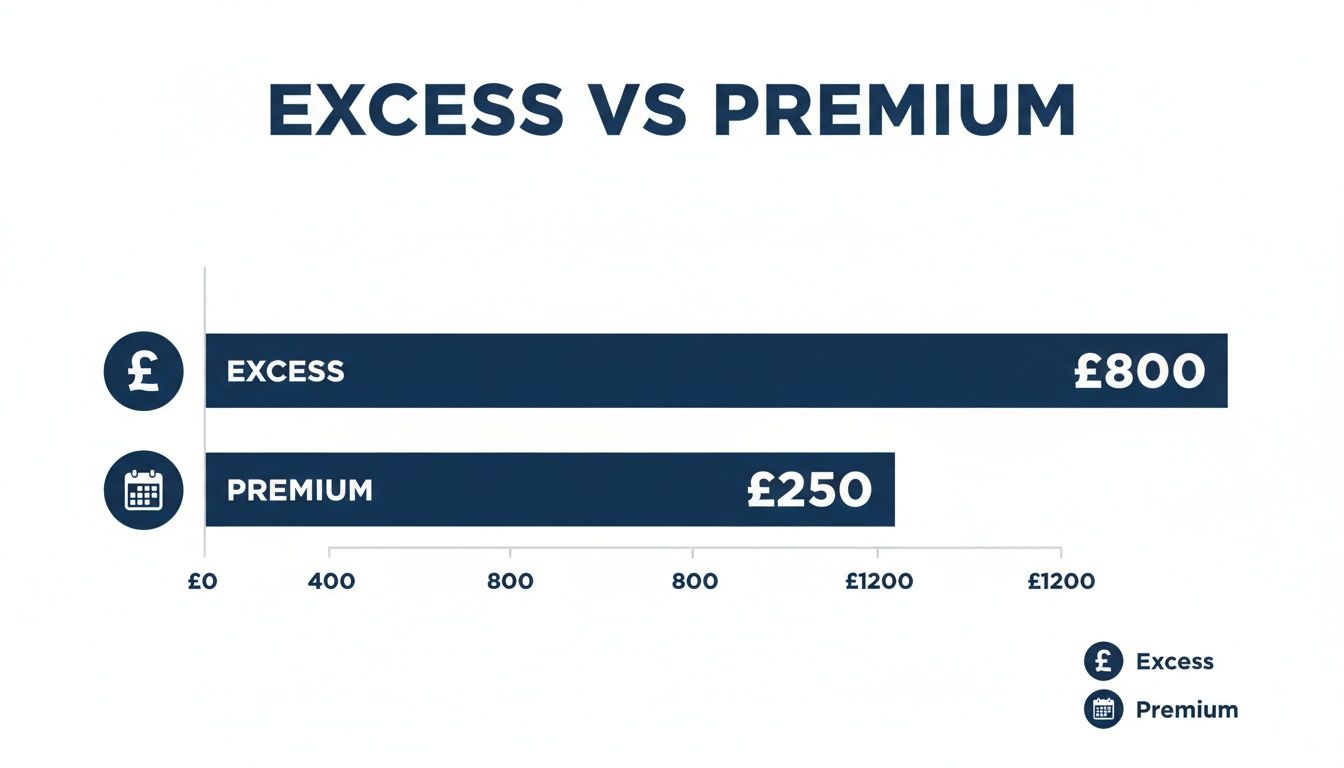
Then there’s voluntary excess. This is your choice, your little gamble. You decide to pay a higher amount upfront (say, £500 instead of £100) to lower your monthly premium. It’s like ordering the house wine instead of the fancy bottle—you’re betting that you won’t have a claim, so you save cash each month. Boom! But—and here’s the kicker—if you do crash into that lamppost again, you’re paying both excesses. Compulsory plus voluntary. Ouch. It’s a bit like betting you won’t need a snack, then paying double for a bag of crisps.
Must Read
So, the golden rule? Voluntary excess is great if you’re a safe driver and want lower monthly bills. Compulsory excess is just part of the deal. Just don’t let your ego (or your wallet) get too cocky. Stay safe, drive like a granny, and keep those premiums down!
Remember: insurance is just a safety net, not a trampoline. So go on, drive that lamppost-free life with a wink and a grin. You’ve got this! 🚗✨