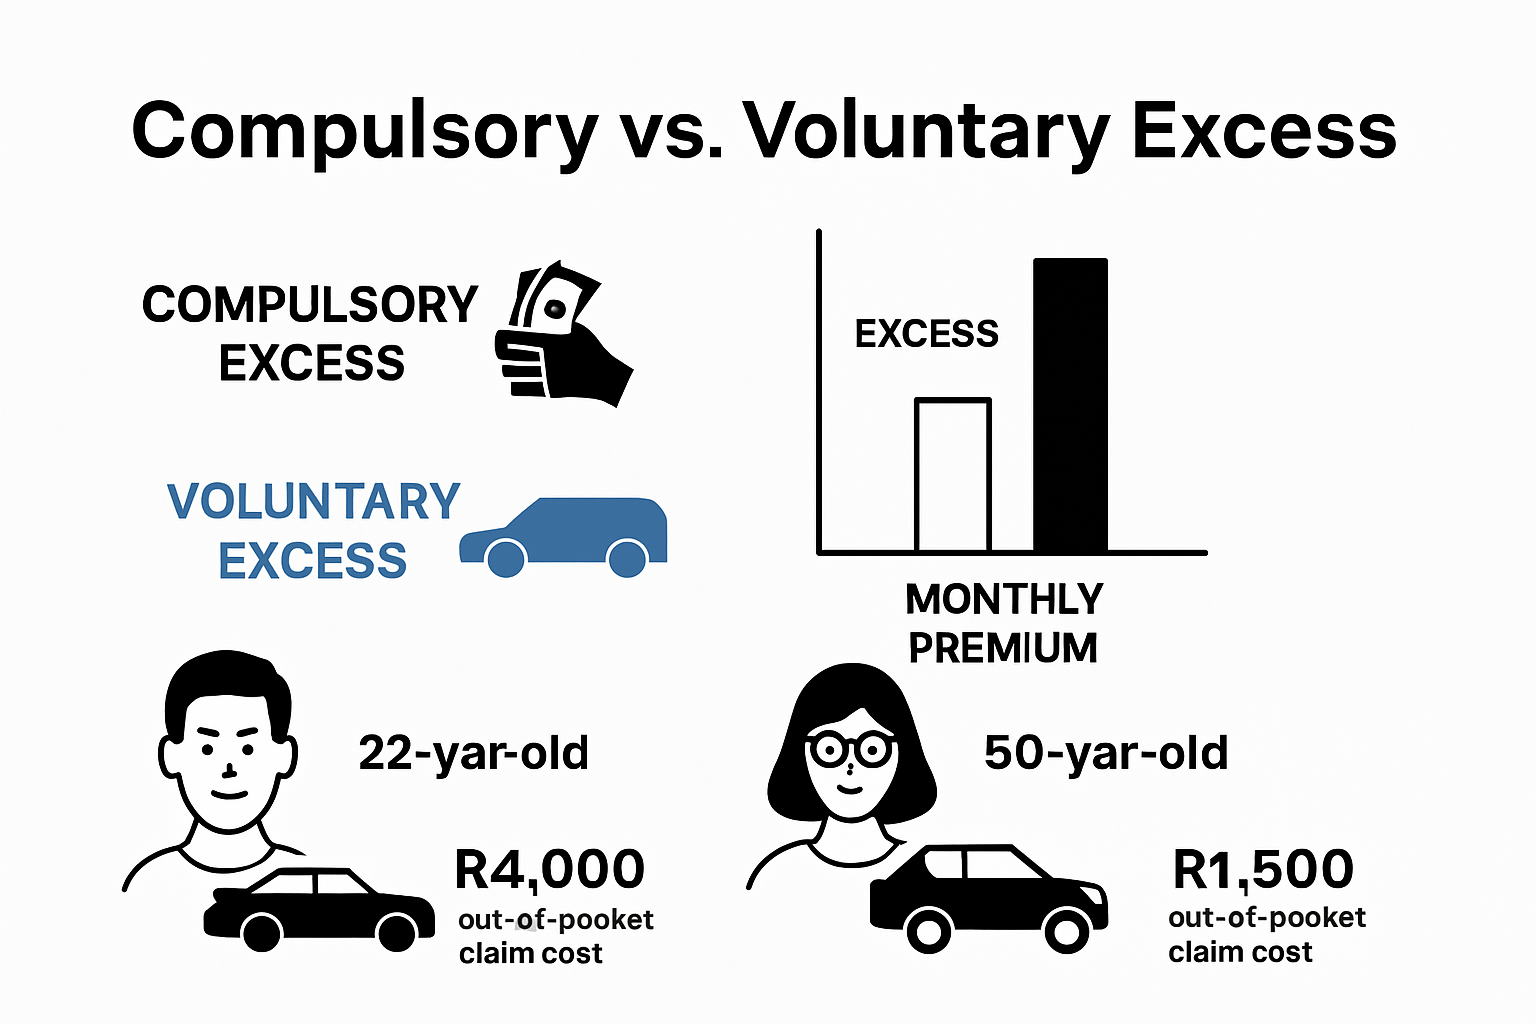
For many people, a sense of control over their finances and the ability to save money on everyday premiums is deeply satisfying. This is where understanding the difference between voluntary and compulsory excess becomes a valuable skill. Far from being a dry insurance term, it is a simple lever that allows you to balance risk with reward, putting you in the driver’s seat of your policy costs.
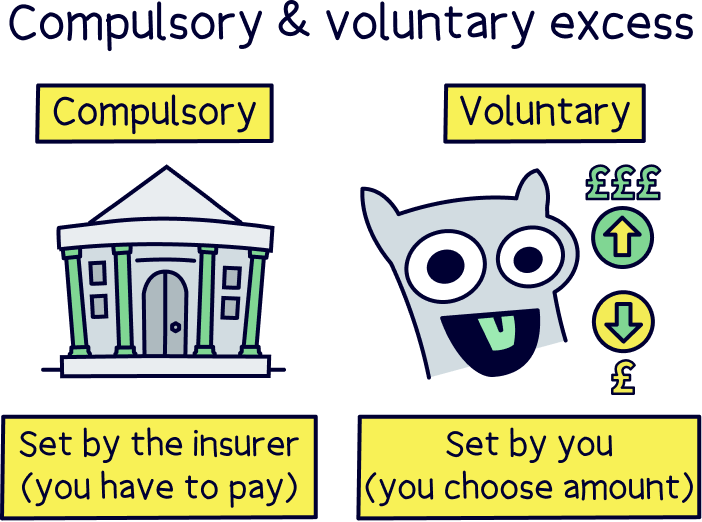
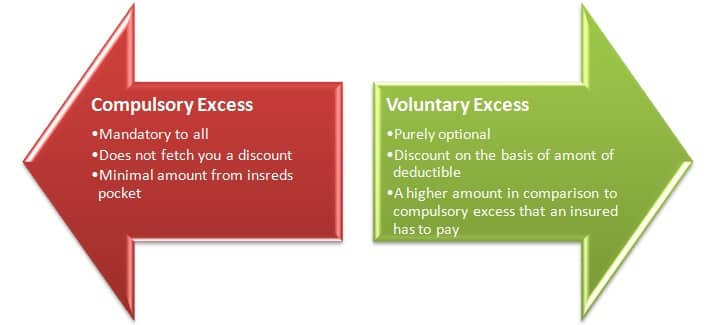
At its core, an excess is the amount you agree to pay towards a claim before your insurer covers the rest. A compulsory excess is fixed by the insurer and is non-negotiable. It is calculated based on your risk profile, such as your age, driving history, or the type of property you insure. This ensures that smaller, frequent claims don’t overwhelm the system, keeping overall premiums more affordable for everyone.
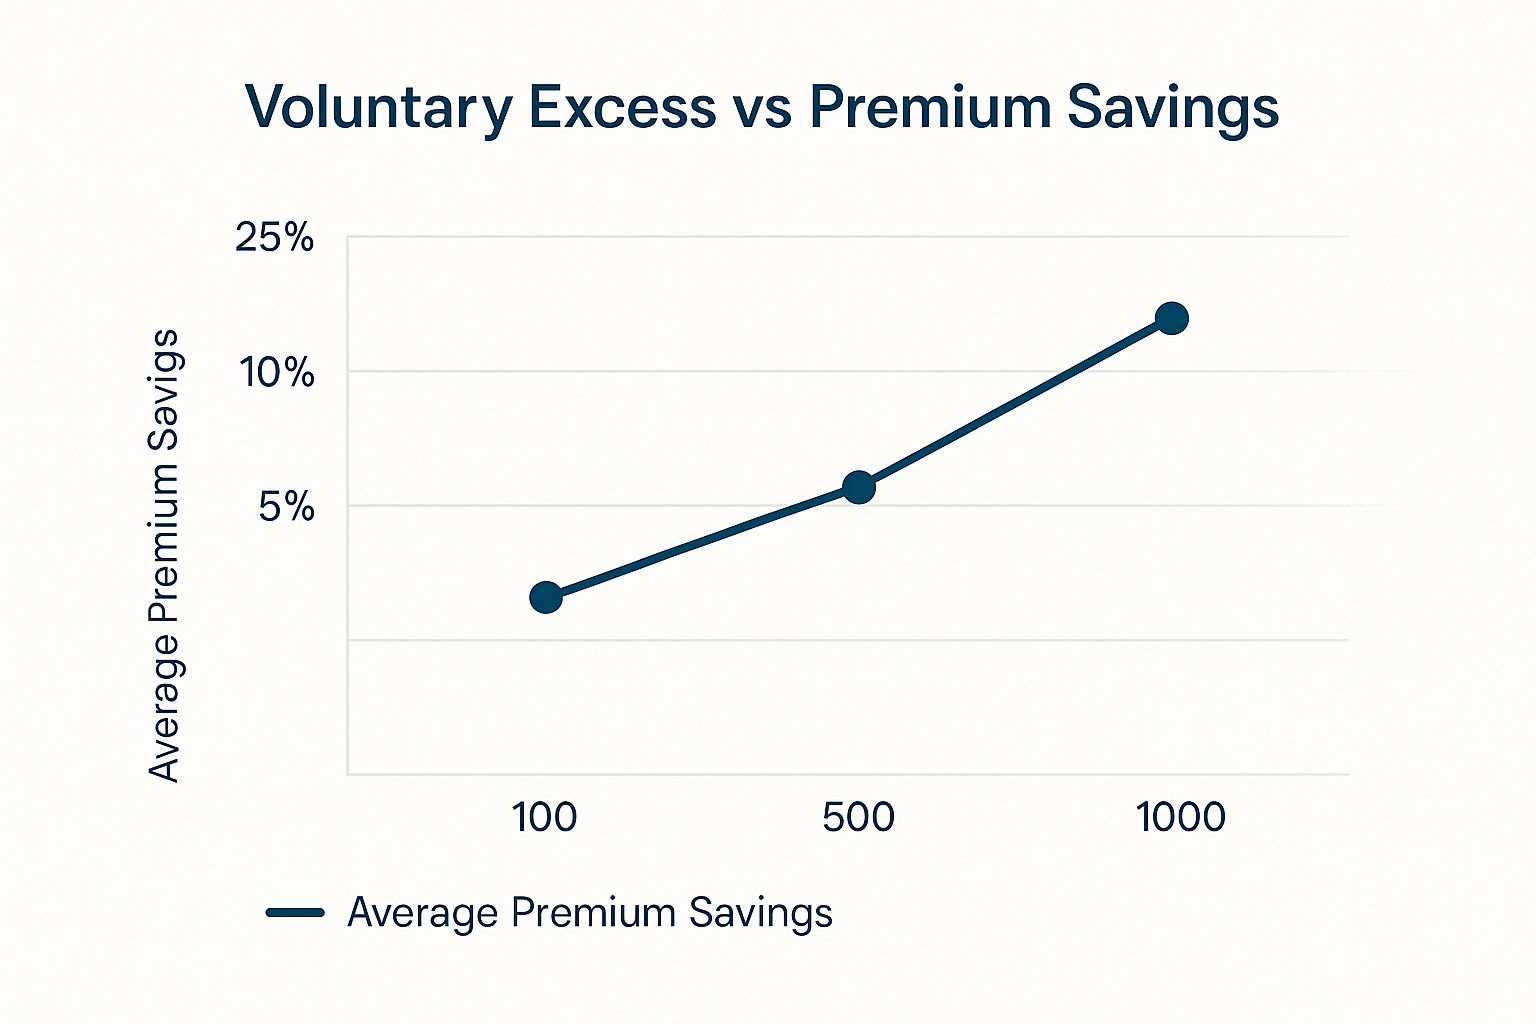
On the other hand, a voluntary excess is your choice. By increasing this amount, you effectively tell your insurer, “I will shoulder more of the initial cost if something happens.” The direct benefit is a lower premium—a monthly or annual saving that can be significant. For example, if you are a careful driver and park your car in a locked garage, you might choose a higher voluntary excess of $500 instead of $100, cutting your yearly car insurance cost by 15% to 20%.
Must Read
The real-world value becomes clear in a scenario: Imagine a minor dent in your bumper costing $400 to repair. If your total excess (compulsory plus voluntary) is $500, you might choose to pay for the repair yourself rather than file a claim. This protects your no-claims bonus and future premiums. Conversely, for a major accident costing $5,000, your excess is a small portion of a much larger claim. The key is to balance the risk of smaller claims against the ongoing rewards of lower premiums.
 What is Excess in Insurance? Understanding Its Role
To explore this yourself, start by comparing policies online. Notice how your premium drops when you increase the voluntary excess slider. Next, calculate your break-even point: how many months of lower premiums would it take to offset a single voluntary excess payment if you claimed? Finally, assess your risk honestly. If you live in a low-risk area or are an experienced driver, a higher voluntary excess is often a smart, empowering financial move.
In everyday life, this simple decision means you are not just a passive consumer of insurance; you are an active participant. It provides a clear pathway to saving money when you are confident in your ability to avoid claims, and it grants you the peace of mind that comes from knowing exactly what your financial commitment is when the unexpected happens.