So, you’ve just opened that shiny new credit card and now you’re staring at a credit limit that feels like a cruel joke. Maybe it’s $500, which is enough for a nice dinner or, oh I don’t know, exactly one tire for your 2008 Honda. Relax—you haven’t failed life. That sad little number is actually a very boring, very normal starting point.
What Is a "Normal" Limit, Anyway?
Here’s the dirty truth: there is no such thing as a universal normal limit. Banks don’t hand out numbers based on your good looks or your charming Instagram captions. They look at your credit history, income, and how much debt you’re already juggling.
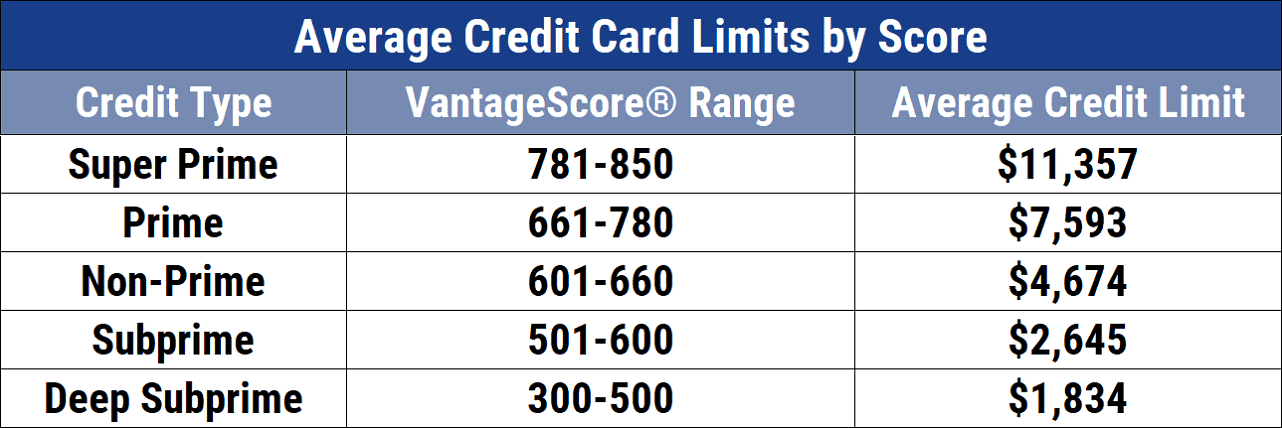
For a first-timer, $1,000 to $3,000 is the sweet spot of “meh.” If you’re a seasoned pro with a stellar score? You might see $10,000 or more—which, let’s be honest, is just a pile of money you shouldn’t spend on a single trip to Target.
Must Read
And here’s the kicker: your credit limit is not a suggestion. It’s a trap dressed up as a compliment. The bank is basically saying, “We trust you… a little… maybe.” Don’t let that trust turn into a late-night Amazon binge.
The Wild Math Behind the Magic Number
Banks use a secret formula involving things like your “debt-to-income ratio” and “credit utilization.” Translation: they want to see if you’re a responsible adult or a raccoon on a sugar high. A normal starting limit is often about 30% of your monthly income.
 What Do the Numbers on Your Credit Card Mean?
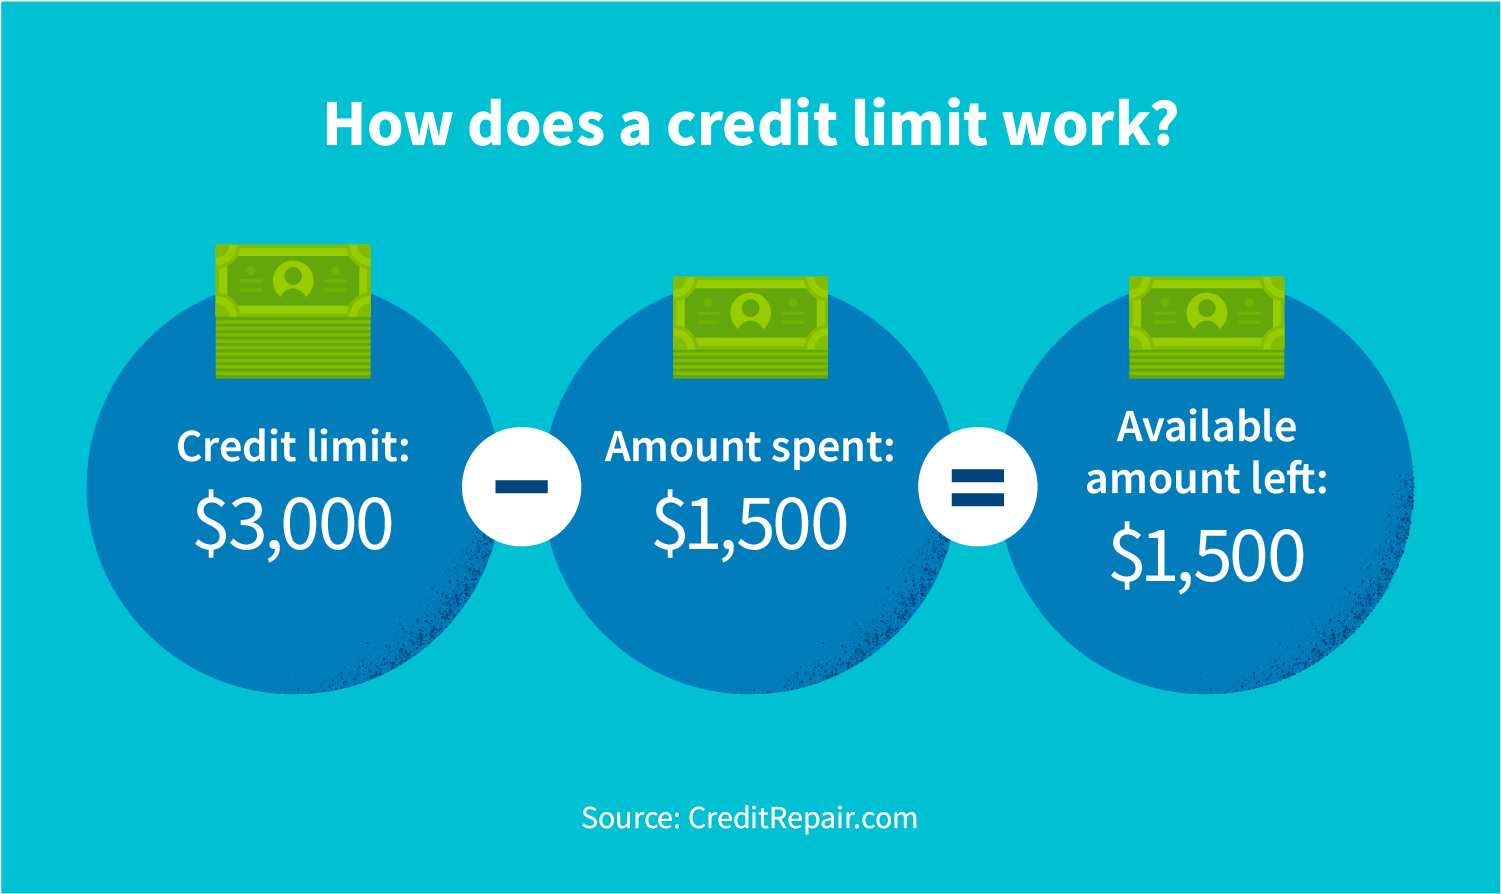
Surprising fact: if you have a $10,000 limit but charge exactly $3,000 each month, your credit score secretly high-fives you. That’s the utilization sweet spot—under 30%. It’s like the Goldilocks of debt: not too much, not too little, but just enough to prove you can handle hot cash without burning yourself.
On the flip side, maxing out a $500 limit on pizza and cat toys? That’s a red flag that says “I make responsible choices like a golden retriever with a credit card.” Don’t be that dog.
 Why You Should Use Credit Cards for Almost Everything
How to Escape the "Normal" Prison
If your limit feels insultingly low, don’t panic. Pay your bill on time for six months, and then ask for a credit increase. Banks love customers who are boringly consistent—like a cashier who always says “have a good one” without making eye contact.
Another sneaky trick: use the card for tiny purchases—a coffee, a pack of gum—and pay it off immediately. You’ll look responsible, and the bank will slowly increase your limit like a kid testing their bedtime boundaries. “Can I stay up to $2,000 now?” “Maybe, if you’re good.”
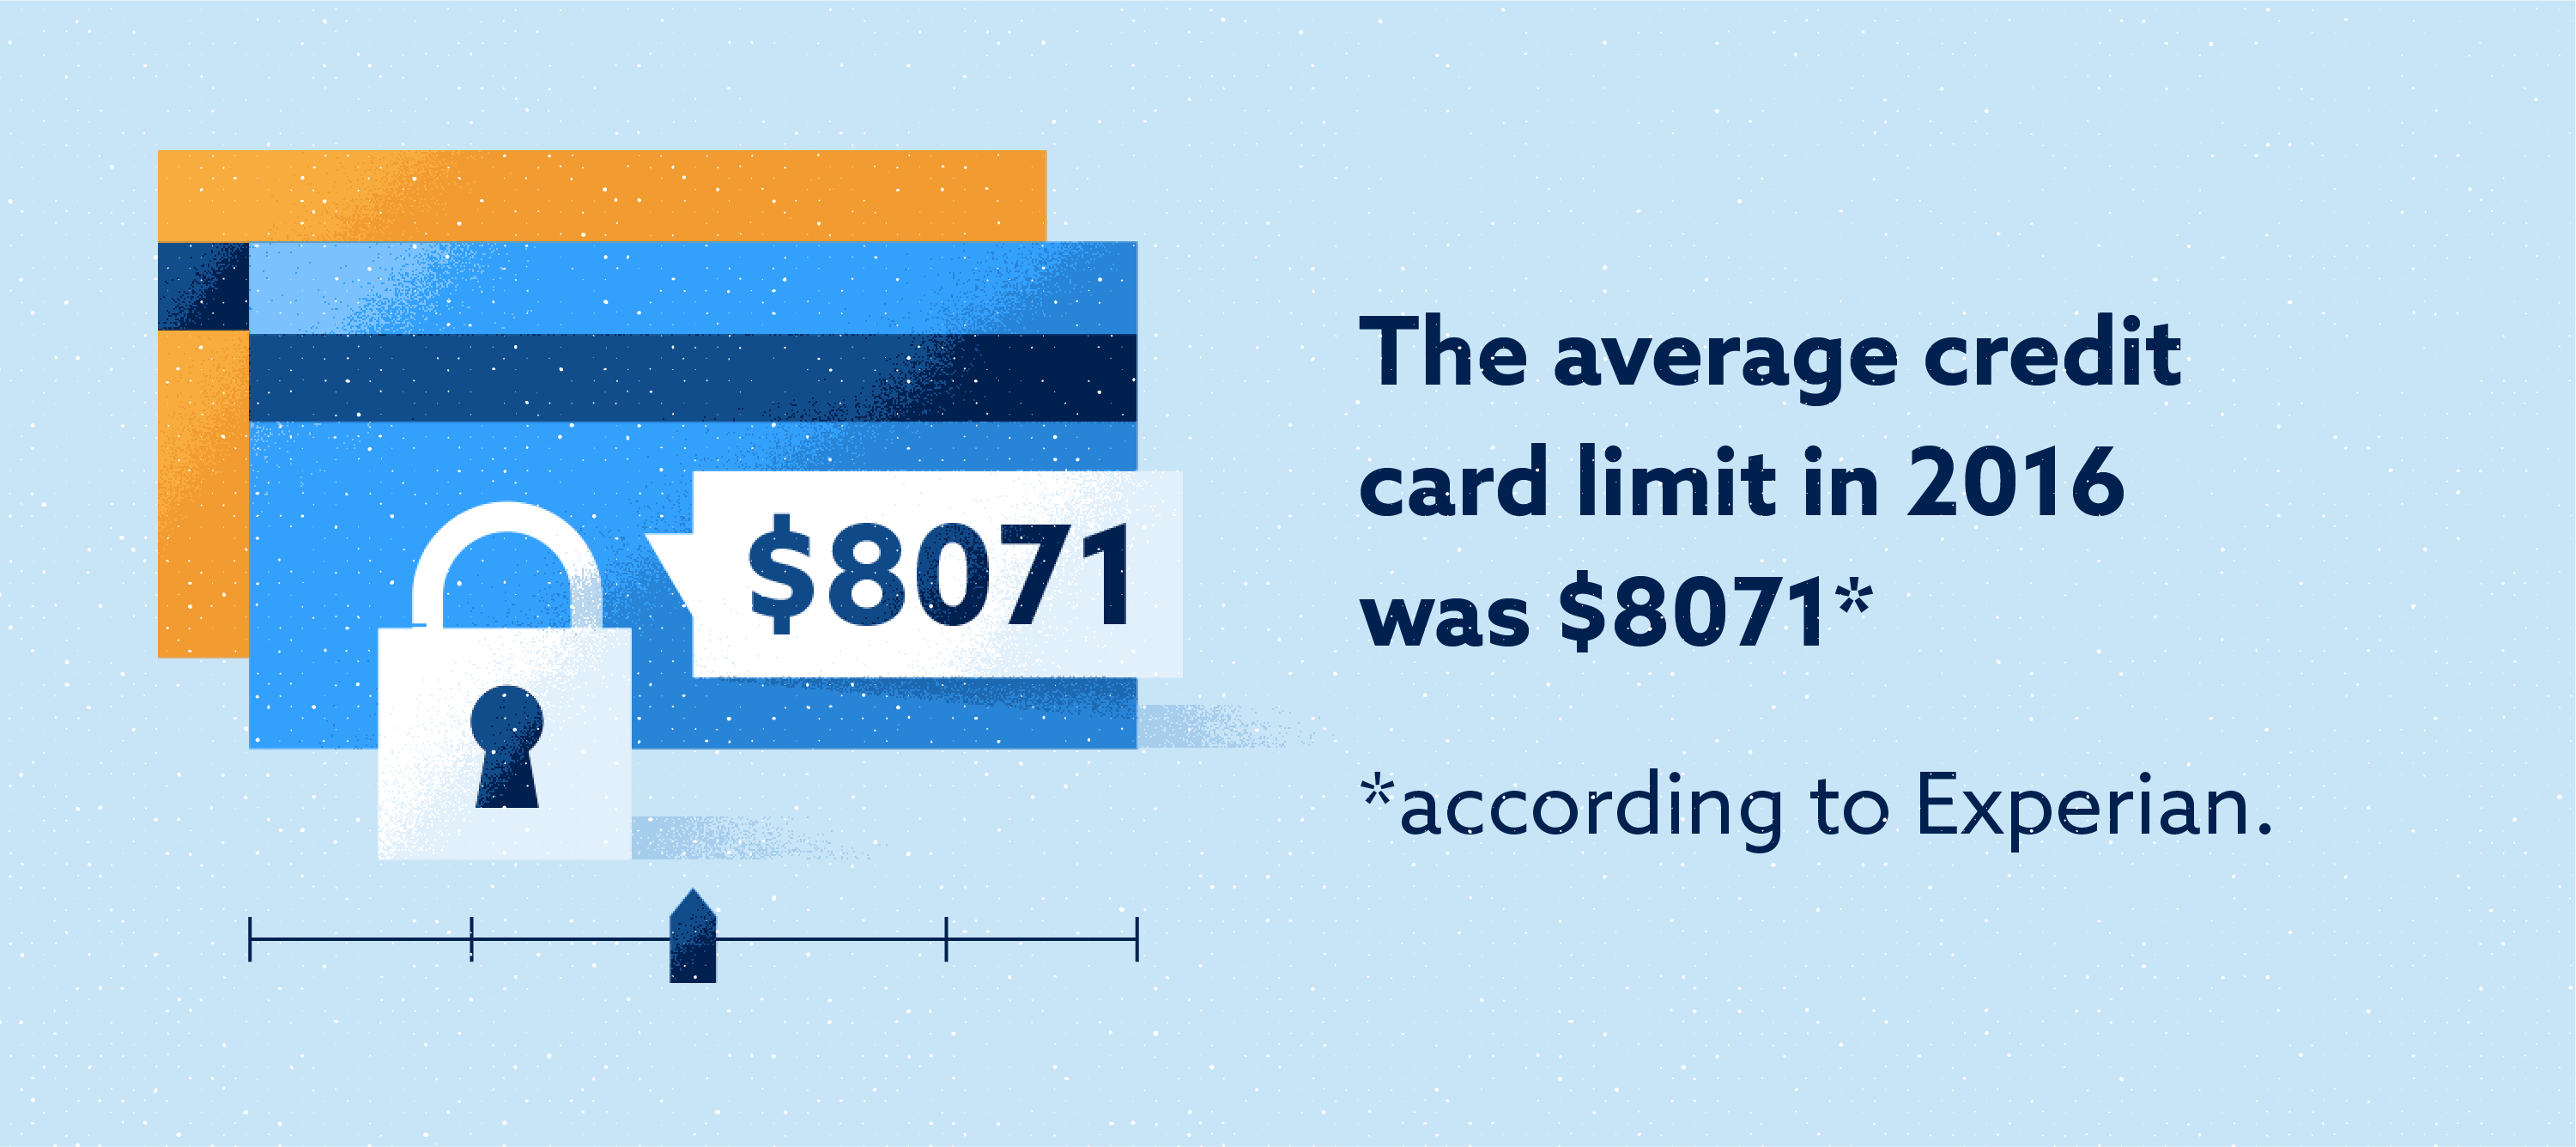 Credit Card Transaction Limit at Susan Lebrun blog
But here’s the real talk: a high limit is not a trophy. It’s a loaded Slurpee machine. Sure, it’s fun to have, but one wrong grip and everything’s sticky and regretful.
The Joke’s on You (If You Abandon Logic)
Remember that a “normal” credit limit is just a tool—like a hammer or a really sharp cheese grater. Use it wisely, and you’ll build a castle of financial trust. Abuse it, and you’ll be grating your own fingers.
So go ahead: celebrate your $1,500 limit like it’s a chunky middle finger to your broke college self. Just don’t buy a jet ski with it. Yet. Wait until the bank actually laughs at your jokes.