There is perhaps no greater test of your patience and resilience than a 50/50 insurance claim. While it might sound like a fair compromise on the surface, this ruling—where both drivers are deemed equally at fault—can feel deeply unjust, especially when you were paying attention and the other driver was not. The key purpose of fighting this decision is to protect your future premiums and your driving record, which if left unchallenged, could cost you thousands of dollars over time. For everyday life, a clean record means lower costs and fewer headaches when you renew your policy.
Imagine this: you are stopped at a red light, and someone rear-ends you. By default, the other driver is usually 100% at fault. However, a creative insurance adjuster might argue that you could have prevented the accident by, say, not braking so suddenly. This is where the fight begins. You must understand that insurance companies use 50/50 to split liability—and costs—quickly, not because it is always accurate.
Your first move is to gather concrete evidence. A photo of the damage is not enough. You need context: skid marks, traffic light timing, and the final resting positions of both vehicles. If there were witnesses, get their contact information immediately. In a parking lot scenario, a 50/50 ruling often follows if both cars were backing up—but if one car was stationary, a photo proves the other driver was the only one in motion.
Must Read
Next, you must challenge the adjuster’s logic in writing. Do not accept the first phone call offer. Instead, write a formal letter questioning why your driving actions—like maintaining a safe speed or signaling—were considered contributory. Use the phrase “preponderance of the evidence” to show you understand the legal standard. Insurers are more likely to reconsider if they sense you will escalate to a state insurance department or an attorney.
Fighting a 50/50 claim also benefits your everyday life by teaching you strategic communication. You learn to remain calm and factual, never emotional, when disputing a fact-based decision. For example, if snow was falling, do not argue about who is at fault for the weather—argue that the other driver failed to adjust speed accordingly, while you did.
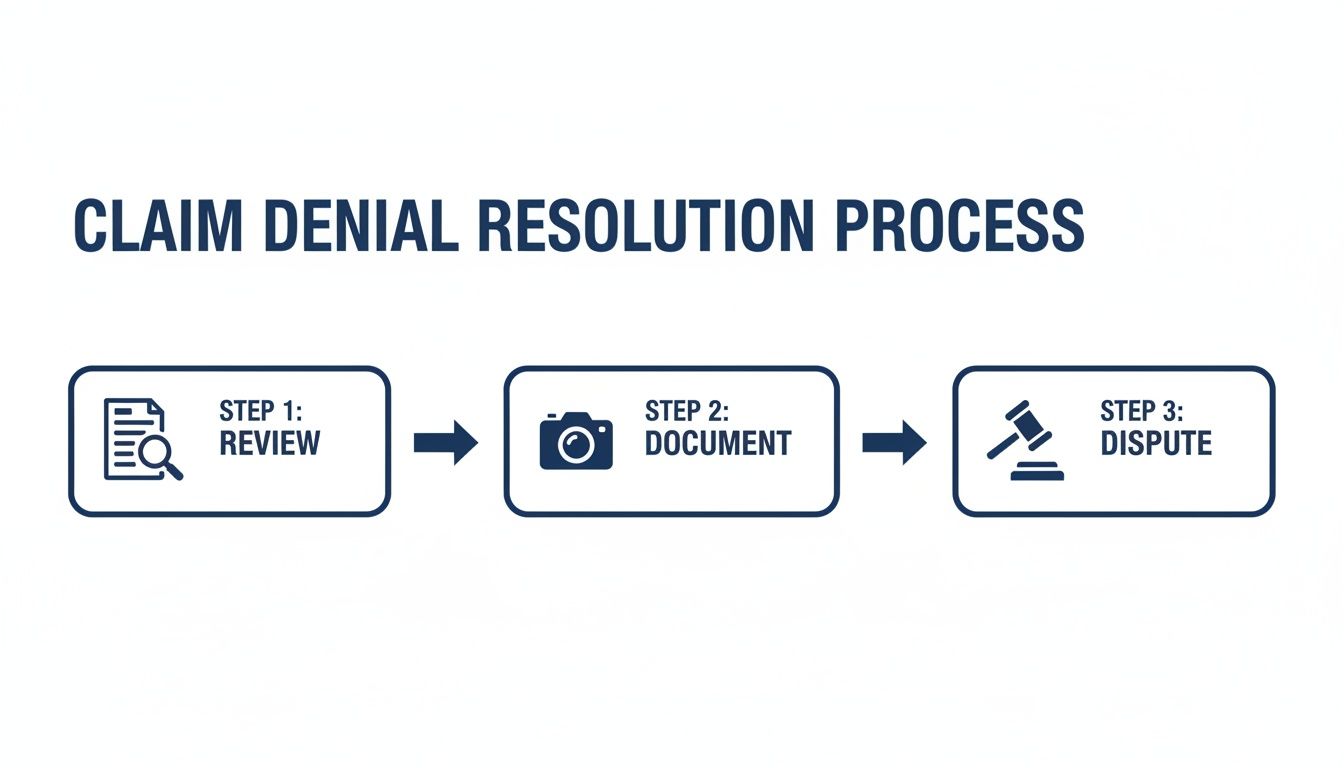
 Claim Dispute: How To Fight A Denied Insurance Claim And Win
Finally, consider a simple tip: reconstruct the timeline on paper. Draw a diagram showing exactly where each car was, second by second, before the impact. When you present this to the adjuster, they see a clear, logical story instead of two competing claims. If they still insist on 50/50, ask for the arbitration clause in your policy. The mere mention of this process often convinces them to offer a better settlement.
Ultimately, fighting a 50/50 claim is about protecting your financial future and demanding fairness. With clear evidence and a patient approach, you can often turn an unfair ruling into a victory that keeps your insurance costs low and your record clean.