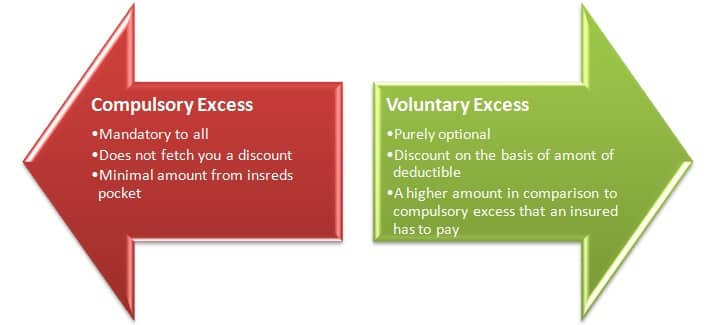
Let’s be honest—nobody wants to pay for extra car insurance, but a compulsory excess has quietly become a lifesaver for millions of drivers. It’s the portion you agree to pay out-of-pocket when making a claim, and it’s essential for keeping premiums affordable for everyone.
Why does it matter? For families, a compulsory excess means lower monthly payments—freeing up cash for school fees or groceries. For individuals, it discourages trivial claims (like a scratched bumper), which keeps insurance pools stable and premiums from skyrocketing. And for communities, it reduces fraud: people think twice before filing a fake claim if they must pay the first $500 themselves.
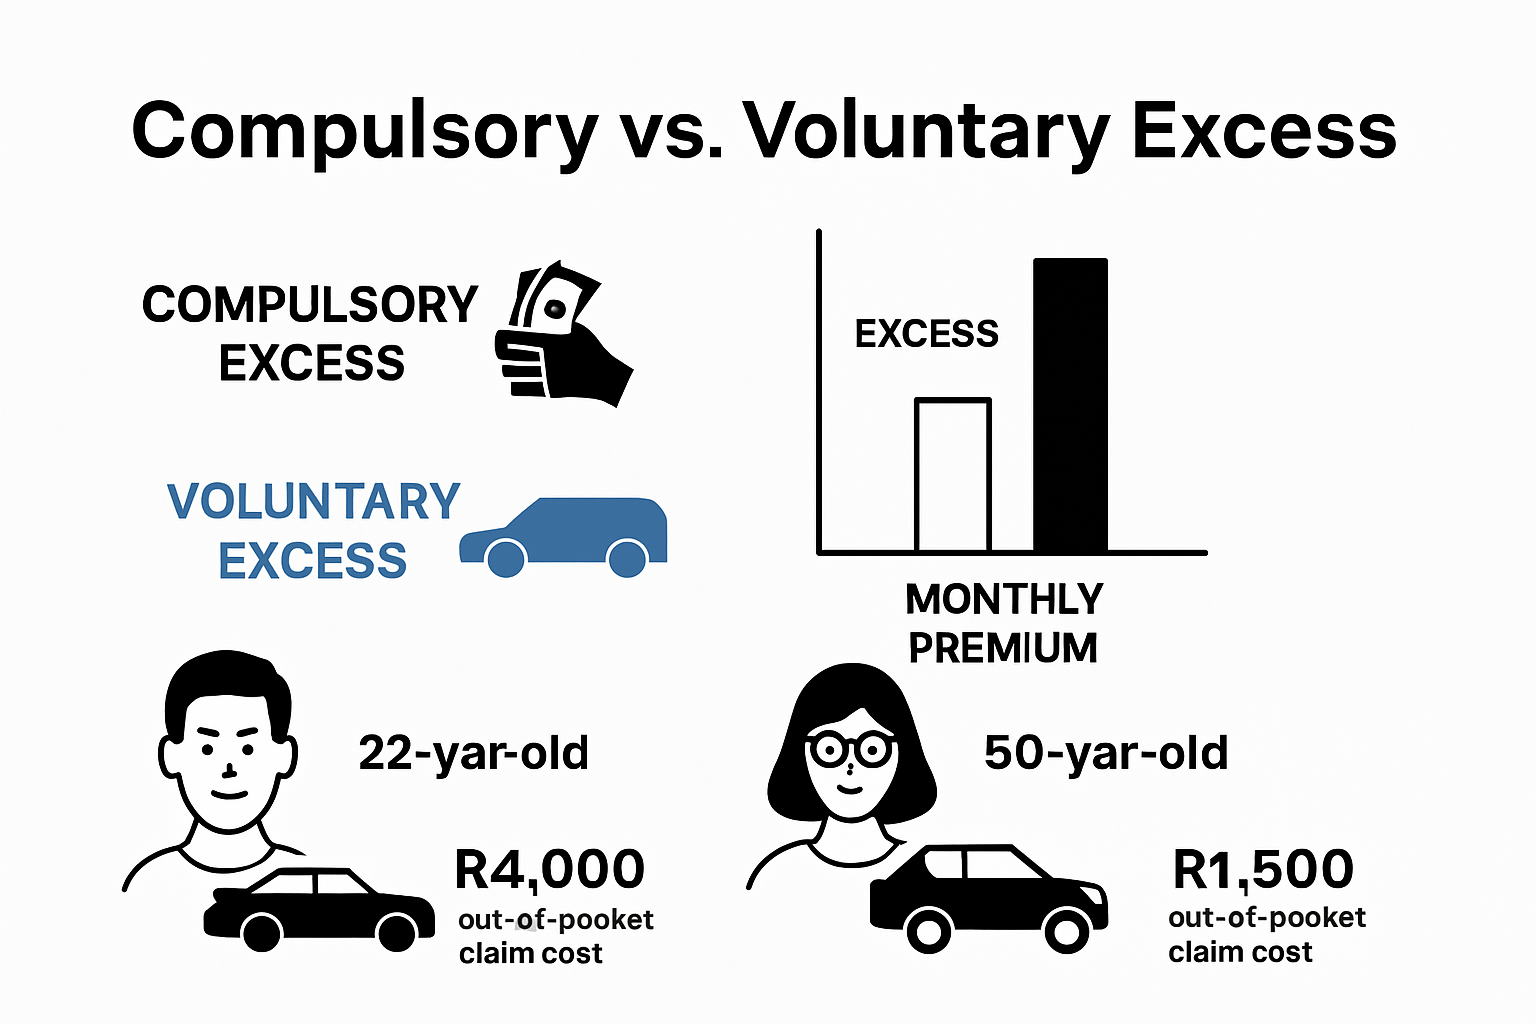
Take Sarah, a young driver. She chose a $1,000 compulsory excess and saved $300 a year. When a hailstorm dented her car, she paid the $1,000 but her insurer covered the rest—and her rates barely budged. Or consider the Johnson family: they raised their excess to $2,500 and used the savings to cover their teenager’s first car.
Must Read
To apply this easily, start by checking your policy’s excess amount. If you have an emergency fund, increase the excess to lower your premium—aim for an amount you could comfortably pay in one go. Compare quotes online; a $500 increase often saves 15%.
Remember, a compulsory excess isn’t a penalty—it’s a smart trade-off. You pay less monthly, take on manageable risk, and help keep insurance fair for all. In a world of rising costs, it’s one small choice that makes a big difference for your wallet and your community.