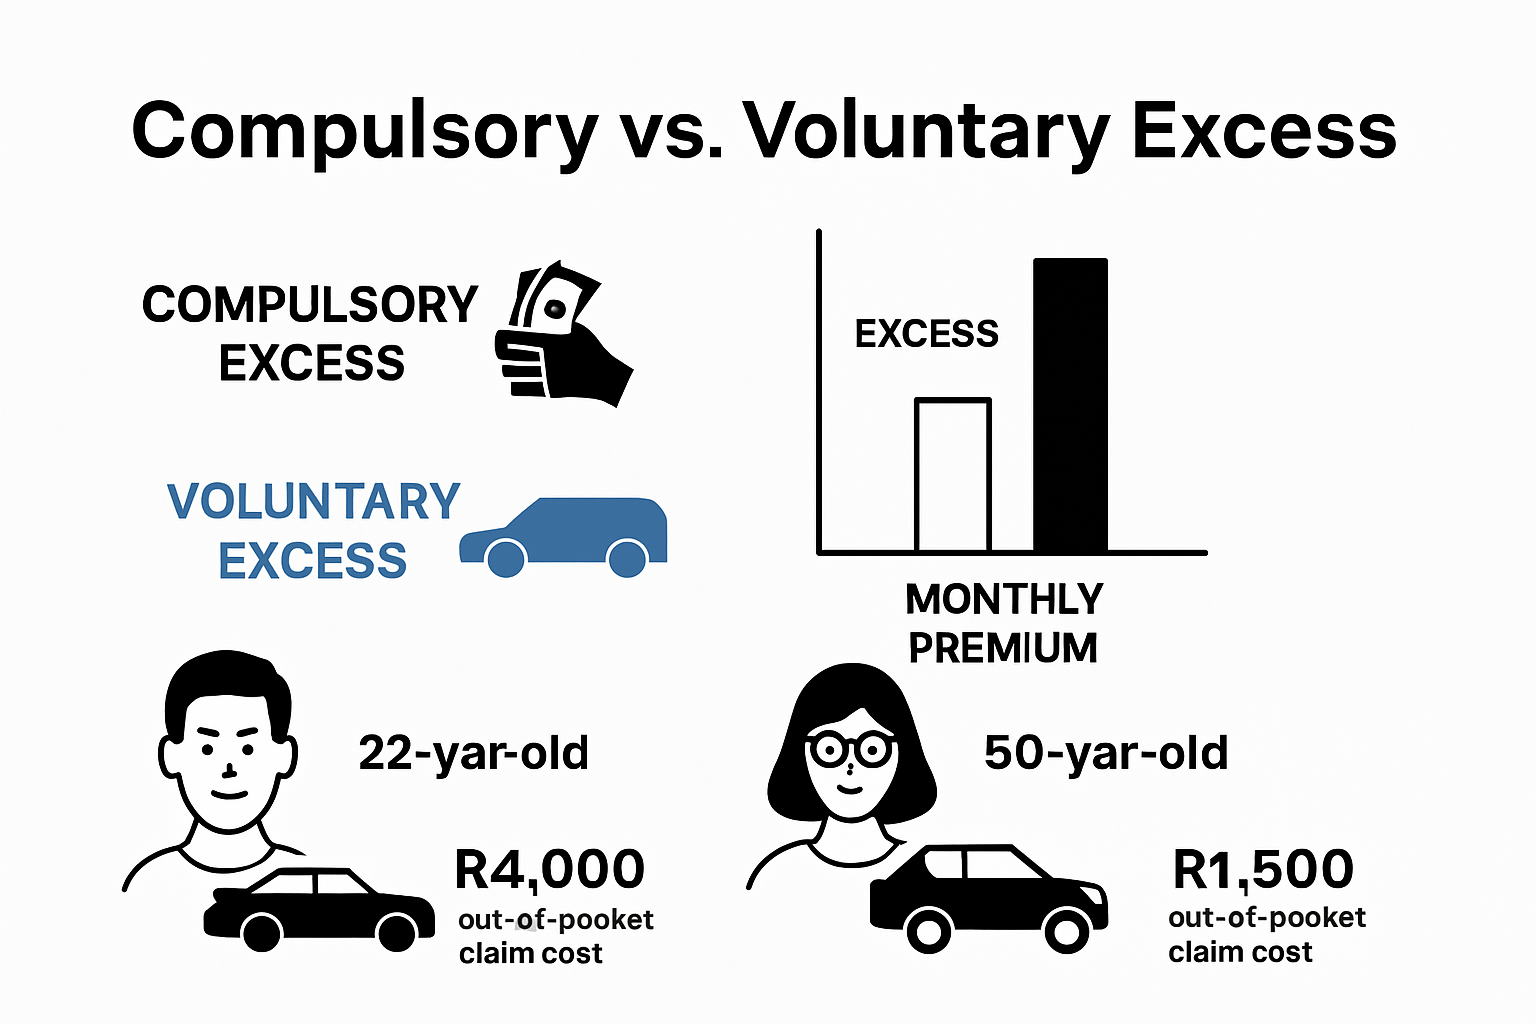
Let’s be honest—insurance paperwork isn’t anyone’s idea of a good time. But understanding compulsory and voluntary excess can actually save you money and a few headaches, making it a surprisingly practical topic. At its core, the concept is simple: it’s the amount you agree to pay out of pocket before your insurer chips in. The purpose is to keep premiums lower for everyone, and the benefit is that you get more control over your policy. For drivers, homeowners, or even pet owners, mastering this can mean the difference between a fair deal and a nasty surprise.
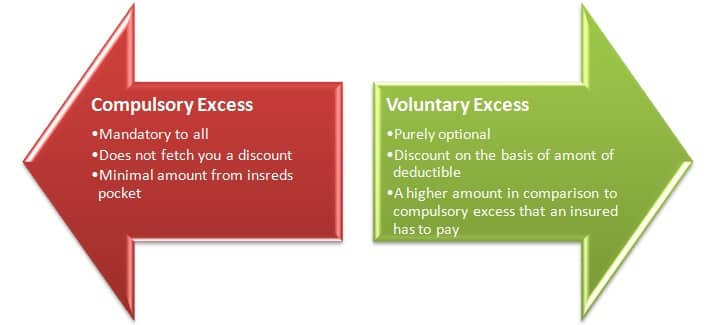
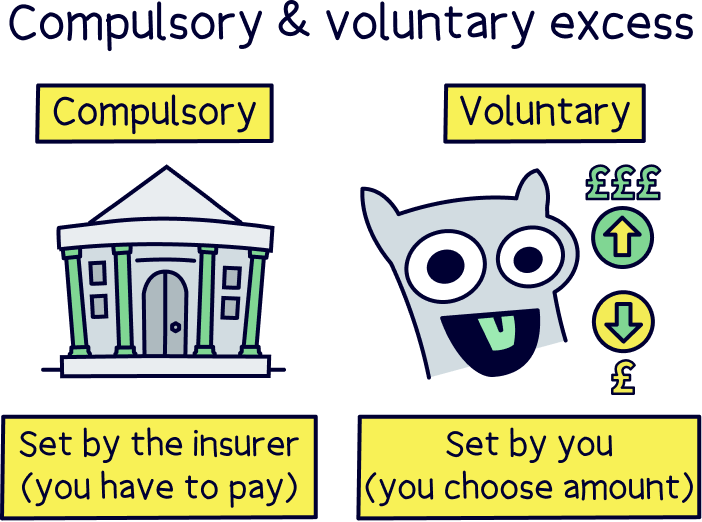
Here’s the breakdown. Compulsory excess is the fixed amount set by your insurer—no negotiation allowed. It’s based on your age, driving history, or the type of policy. For example, a young driver might have a compulsory excess of £500 because they’re seen as higher risk. This protects the insurer from small claims. On the other hand, voluntary excess is your choice—you decide to pay extra if you make a claim, usually between £100 and £500. Want lower premiums? Bump up your voluntary excess. The trade-off is you’re on the hook for more if something goes wrong.
Common variations include policies with a split excess—a separate amount for theft versus accidents. Some insurers let you set voluntary excess to zero, but your premium will jump. Imagine you’re insuring a car: a low compulsory excess (say £250) combined with a high voluntary excess (£500) could cut your yearly cost by 15–20%. It’s a balancing act between upfront savings and potential outlay.
Must Read
To get started, grab your policy documents and check the compulsory excess listed. Then, ask yourself: can I easily afford this amount if I crash tomorrow? If yes, consider raising your voluntary excess to lower your premium. For example, if you’re a safe driver with a good no-claims bonus, a voluntary excess of £300 might save you £50 a year. Always read the fine print—some policies penalize high voluntary excess on windscreen claims.
 What is Excess in Insurance? Understanding Its Role
For maximum benefit, match your excess to your savings. Keep enough cash aside to cover the total excess (compulsory + voluntary) without stress. And remember, don’t choose a voluntary excess just to get a cheap quote—pick one you’d genuinely be okay paying. A practical rule: if you drive a low-value car, a higher voluntary excess often makes sense. For a new vehicle, stick lower.
In short, excess isn’t a penalty—it’s a tool. Use it wisely, and you’ll turn a boring insurance detail into a savvy financial move. Start small: check your current policy, play with the numbers online, and see how a little adjustment can put more cash in your pocket. That’s the kind of practical magic everyone can appreciate.