
Hey there, homeowner! Ever felt like your home's got a secret stash of cash, just waiting for you to tap into it? Well, that's kind of what a Home Equity Line of Credit (HELOC) is all about. It's like your home's very own piggy bank, and today, we're gonna chat about how to find the best HELOC rate.
First things first: What's a HELOC?
Alright, imagine you've got a credit card, but instead of maxing out your plastic, you're maxing out your home's equity. That's basically a HELOC in a nutshell. It's a line of credit that uses your home's equity as collateral. Sounds fancy, right?
Now, let's talk rates. Why are they so darn important?
Picture this: You're at the grocery store, and you've got two carts full of goodies. One cart's got a 3% interest rate, and the other's got a 6% interest rate. Which one's gonna cost you more in the long run? Exactly. That's why finding the best HELOC rate is like finding the golden ticket in Willy Wonka's factory.
Must Read
But here's the thing, folks. HELOC rates aren't one-size-fits-all. They depend on a whole bunch of factors, like your credit score, your loan-to-value ratio, and even the current market conditions. So, let's dive in and see what makes a HELOC rate tick.
Credit score: The magic number
Your credit score is like your financial report card. The higher it is, the better your HELOC rate will be. It's all about trust, baby. Lenders want to know you're a responsible borrower, so they're more likely to give you a lower rate.
But don't worry if your score's not perfect. There are still options out there for you. It's just that you might have to kiss a slightly higher rate goodbye. Think of it as a little extra interest in exchange for a second chance.
Loan-to-value ratio: The equity game
Your loan-to-value ratio (LTV) is like your home's equity cheerleader. It's the percentage of your home's value that you've borrowed against. The lower your LTV, the better your HELOC rate will be. Why? Because lenders love it when you've got skin in the game.
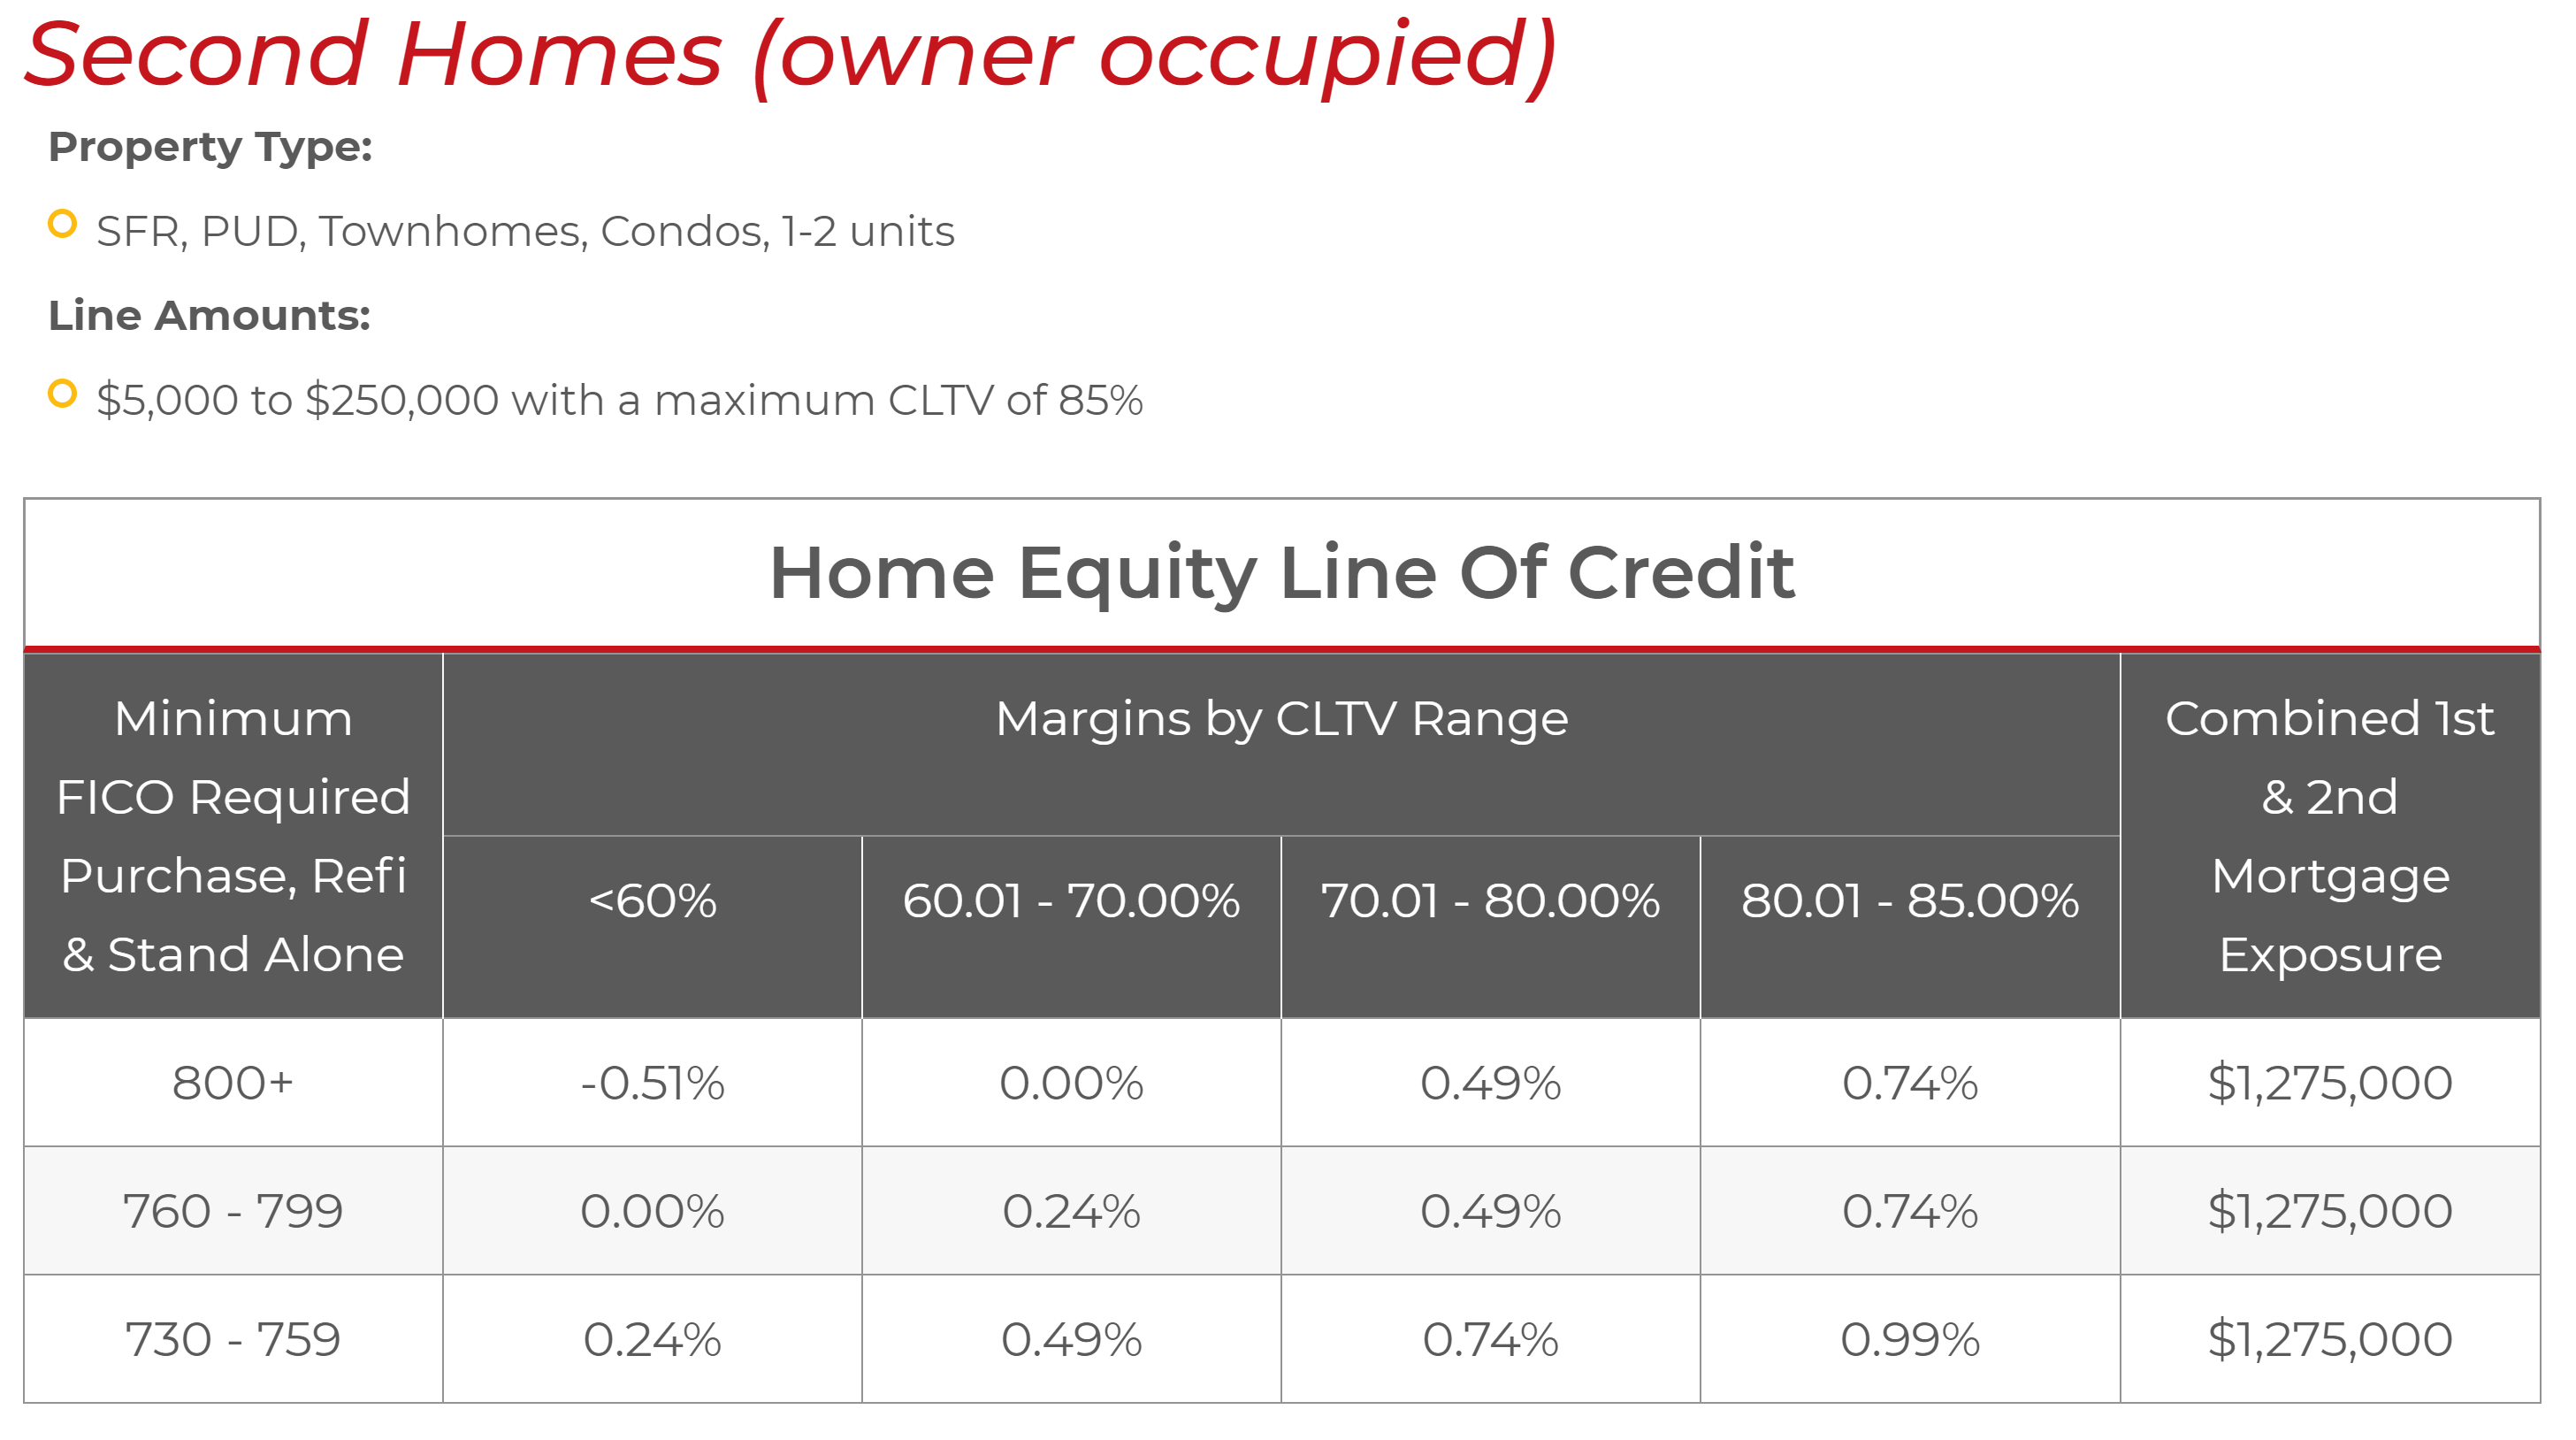 Vacation Homes and Home Equity Loans | Pacific West Lending
So, if you've got a home worth $300,000 and you've paid off $200,000 of it, your LTV is 33%. That's like telling the lender, "Hey, I've got a $100,000 stake in this. I'm not gonna skip town on you."
Market conditions: The rate rollercoaster
HELOC rates are like the stock market. They go up, they go down, and sometimes, they do the Macarena. Okay, maybe not that last one. But you get the picture.
Interest rates are influenced by the Federal Reserve, and they change based on the economy's health. So, if you're thinking about snagging a HELOC, it might be a good idea to keep an eye on the market. You never know when that golden ticket rate might pop up.
Now that you're a HELOC rate expert, what's next?
Alright, so you've got the lowdown on HELOC rates. You're ready to take on the world (or at least your local lending scene). But before you dive in, remember to shop around. Don't just go with the first lender who winks at you. Compare rates, ask questions, and make sure you're getting the best deal.
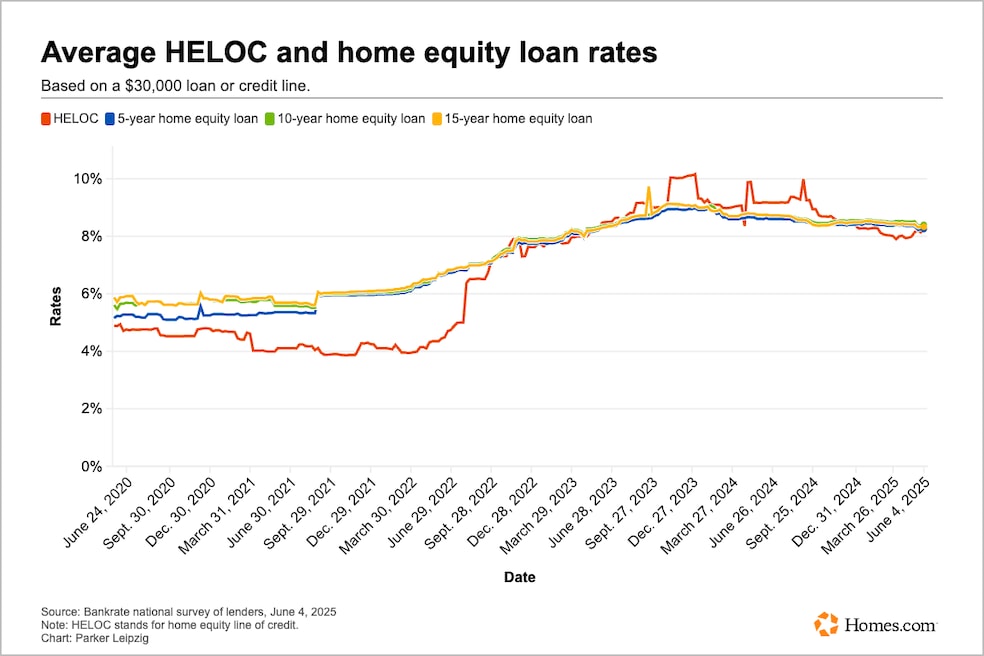 Chart of the day: Rates on home equity loans and lines of credit rise
And hey, if you're feeling a little overwhelmed, don't be afraid to ask for help. There are plenty of financial advisors out there who'd be happy to lend a hand (pun intended).
So, are you ready to tap into your home's secret stash?
Finding the best HELOC rate might feel like a treasure hunt, but it's totally worth it. Whether you're looking to renovate your kitchen, pay for your kid's college, or start that dream business, a HELOC could be your golden ticket.
So, go forth, homeowner. May the odds be ever in your favor. And remember, your home's piggy bank is waiting. You just gotta find the right key.
Until next time, happy borrowing!